Hi everyone,


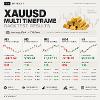
I’ve been testing the same XAUUSD breakout/expansion EA across multiple strategy timeframes using the exact same parameters and strategy logic.


Backtest period:January 2026 → Till Date


Timeframes tested:• M3• M5• M15• M30• H1


Results:


M3  → -$972.53 | PF 0.91 | 1,412 tradesM5  → +$792.50 | PF 1.16 | 599 tradesM15 → +$1,187.11 | PF 1.16 | 1,043 tradesM30 → -$170.10 | PF 0.99 | 2,316 tradesH1  → +$1,073.30 | PF 1.36 | 369 trades


Initial deposit: $1,000Risk per trade: 0.5%


The objective of this test was not optimization. I wanted to see how the exact same strategy behaves when only the strategy timeframe is changed.


Interesting observation:H1 produced the highest Profit Factor (1.36), while M15 produced the highest net profit with lower drawdown than the other profitable timeframes.


I’m sharing the results for discussion and feedback.


What timeframe would you consider more robust for further validation — M5, M15, or H1?


Backtest screenshot attached.


Lampiran:

Consistency before scale.