




US Inflation Data and US-Iran Deal Hopes Keep the Dollar in Focus | 10th November, 2026

CPI Day Tests Dollar
Global currency markets are waiting for today's US October CPI report while mixed signals over a US-Iran deal keep the US Dollar Index consolidating near 101.70 after a pullback from Friday's payrolls-driven highs. WTI has fallen below $85.50 on diplomacy hopes, the Pound steadies below 1.3450, the Euro slips to near 1.1220 on French political instability and reports of an early Lagarde departure, the New Zealand Dollar holds near 0.5630 after its biggest one-day gain since April on the election outcome, and USD/CAD edges up to 1.4120 as lower oil weighs on the Loonie. Traders are watching the US CPI release at 13:30 GMT, Friday's US PPI, Fed commentary with December hike odds near 84%, and US-Iran negotiations for fresh direction.
US Dollar Index (DXY) Forecast
Current Price and Context
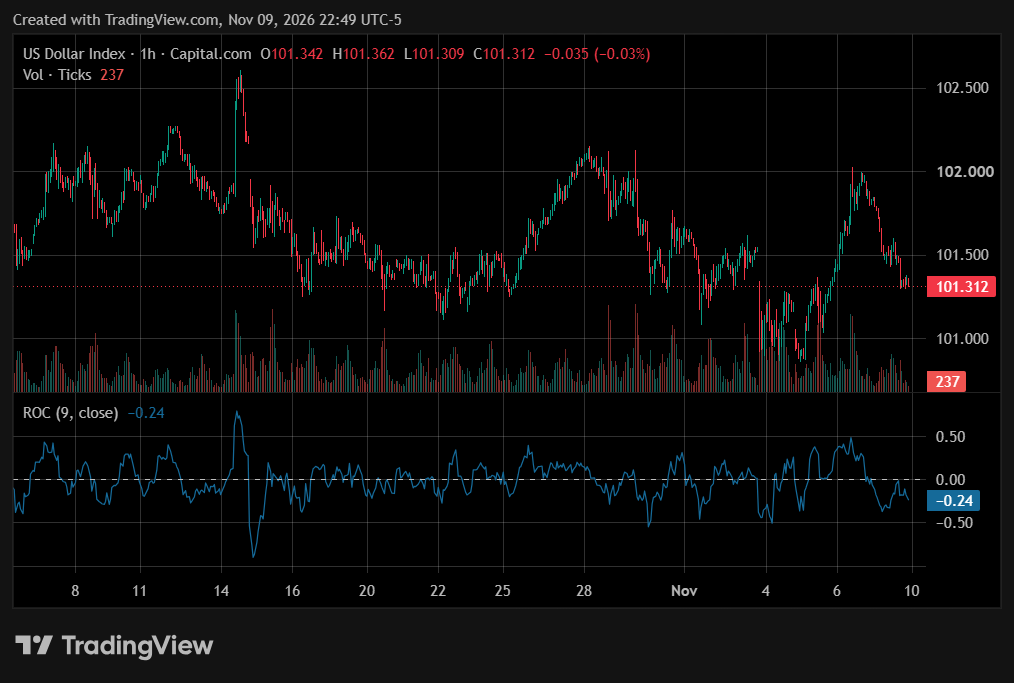
The US Dollar Index (DXY) consolidated around 101.70 during the Asian session on Tuesday, 10 November 2026, after closing Monday near 101.91 as easing US-Iran tensions pulled the index below the 102.00 level. Bulls are waiting for the US CPI report before placing fresh bets, with Fed hike bets of about 84% for December and mixed signals over Iran peace talks keeping the geopolitical risk premium in play.
Key Drivers
• Geopolitical Risks: Mixed signals over US-Iran peace talks, including Trump saying strikes may not be necessary while keeping the US locked and loaded, keep the safe-haven Dollar supported but capped.
• US Economic Data: Today's October CPI, expected at about 0.2%-0.3% month on month for the headline and 0.2% for core, could reinforce December hike bets if it surprises higher or reverse part of Friday's Dollar gains if softer.
• FOMC Outcome: December Fed hike odds near 84%, backed by Deutsche Bank's call for 25 basis point hikes in December and March, keep policy expectations supportive of the Dollar unless inflation cools.
• Trade Policy: China's extension of its 24% tariff suspension eases US-China trade tensions, although no new US trade-policy catalyst featured in today's reporting, so tariff changes would act as an indirect risk through growth and inflation expectations.
• Monetary Policy: Hawkish moves by the BoE, ECB and RBA could narrow the Dollar's relative yield advantage, although Brown Brothers Harriman says robust US activity and sticky inflation keep rate differentials supportive of the Dollar.
Technical Outlook
• Trend: The index holds a mildly bullish bias above the 101.65-101.70 former resistance now acting as support and above the 50-day EMA, although it remains below Friday's 102.11 close.
• Resistance: Resistance appears at Friday's 102.11 close and 102.26, followed by the 102.49 cycle high and the October 14 high just under 103.00.
• Support: Initial support is 101.70-101.65, followed by 101.50 and the 50-day EMA near 101.21.
• Forecast: The DXY could retest 102.11 if CPI surprises higher and supports December hike bets, whereas a soft print and further Iran deal progress could push it toward 101.50.
Sentiment and Catalysts
• Market Sentiment: Sentiment is cautious, with bulls waiting for CPI while speculative positioning is already heavily long the Dollar, which makes rallies harder to sustain.
• Catalysts: Today's US CPI, Friday's US PPI, Fed speakers and US-Iran negotiations could determine the index's next directional move.
NZD/USD Forecast
Current Price and Context
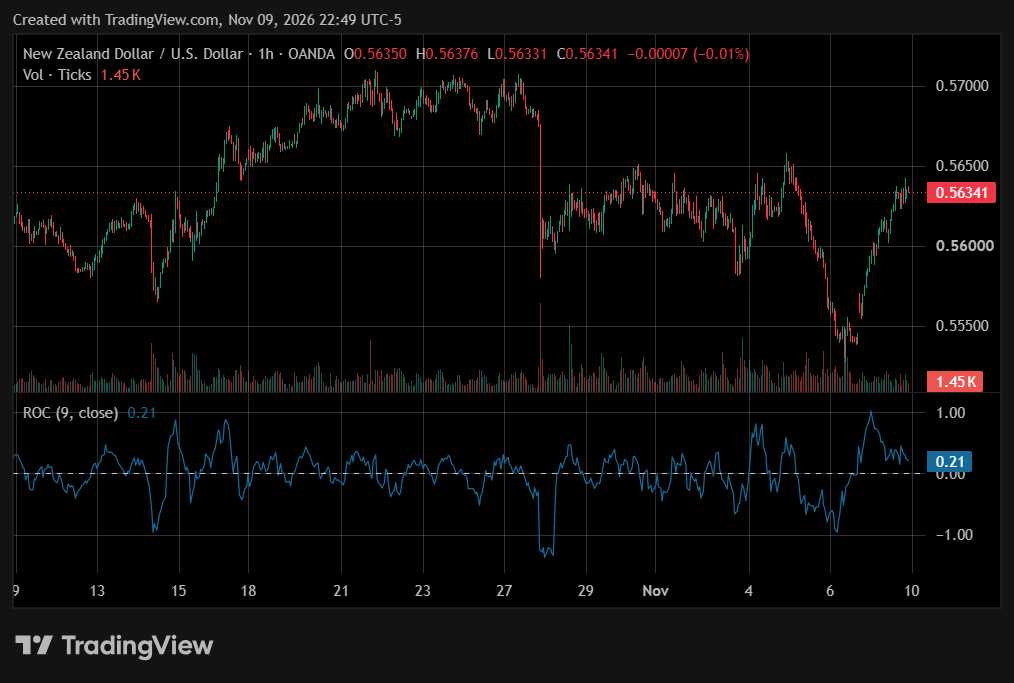
NZD/USD held flat around 0.5630 during Asian hours on Tuesday, 10 November 2026, after posting its biggest one-day gain since April on Monday as preliminary election results gave the ruling National-led coalition a path to remain in power. The rally followed a drop to around 0.5527 on Friday, a seven-month low, and gains are limited as the US Dollar holds firm ahead of CPI and the RBNZ trails other central banks after its 4-3 hold at 2.75%.
Key Drivers
• Geopolitical Risks: Hopes for US-Iran diplomacy support risk appetite and the kiwi, although the failure of Iran talks to lift NZD/USD further shows that safe-haven Dollar demand can return quickly if talks falter.
• US Economic Data: Today's US CPI could strengthen the Dollar and limit NZD/USD gains if hotter, while softer data could extend the kiwi's recovery.
• FOMC Outcome: December Fed hike odds near 84% keep the Fed-RBNZ rate gap at least 1.00 point and could cap NZD/USD even if risk sentiment improves.
• Trade Policy: No specific trade-policy catalyst featured in today's reporting, but China's tariff suspension extension supports demand sentiment for New Zealand's largest export market, which could indirectly help the kiwi.
• Monetary Policy: The election outcome reduces the prospect of Labour's proposed dual-mandate change at the RBNZ, but the RBNZ's 4-3 hold at 2.75% and soft labor market keep it trailing other central banks before the 9 December meeting.
Technical Outlook
• Trend: NZD/USD is consolidating after a sharp rebound from the 0.5527 seven-month low, with the 50-day EMA near 0.5700 still above the price.
• Resistance: Resistance appears at 0.5650, followed by the 50-day EMA near 0.5700 and the 200-day EMA just under 0.5800.
• Support: Initial support is 0.5600, followed by the 0.5550 October low and the 0.5527 seven-month low.
• Forecast: NZD/USD could test 0.5700 if CPI cools and risk appetite holds, whereas a hot US print could push it back toward 0.5600.
Sentiment and Catalysts
• Market Sentiment: Sentiment toward the kiwi has improved after reduced political uncertainty, although dovish RBNZ pricing and a firm Dollar keep gains measured.
• Catalysts: Today's US CPI, final New Zealand election results due on 27 November, US-Iran headlines and the RBNZ's 9 December meeting could determine the pair's next move.
GBP/USD Forecast
Current Price and Context
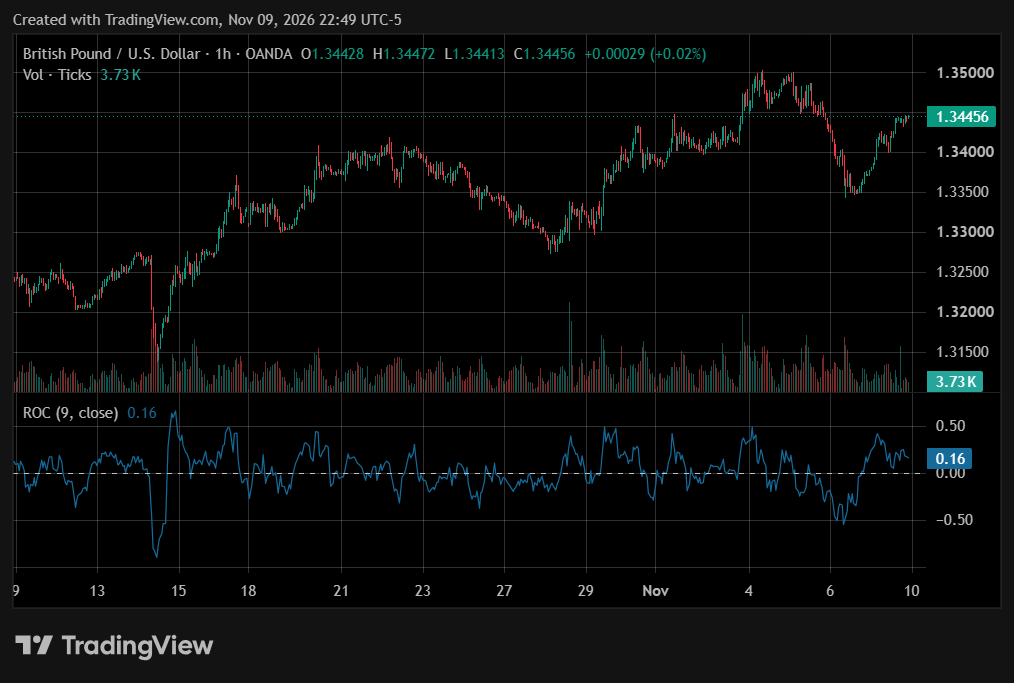
GBP/USD flatlined near 1.3445 in the early Asian session on Tuesday, 10 November 2026, after gaining about 0.5% on Monday as easing US-Iran tensions weakened the US Dollar. Traders see 84% odds of a December Fed hike, and the headline US CPI is expected to rise 0.3% month on month in October with core at 0.2%.
Key Drivers
• Geopolitical Risks: Easing US-Iran tensions reduce safe-haven Dollar demand and support GBP/USD, although the US Navy blockade and claims that Hormuz is closed leave scope for renewed risk aversion.
• US Economic Data: Today's CPI could determine whether the Dollar's pullback extends, with a hot print likely to push GBP/USD below 1.3400 and a soft print supporting a retest of 1.3500.
• FOMC Outcome: December hike odds near 84% keep the Fed hawkish, so a repricing of those odds could drive GBP/USD more than UK data.
• Trade Policy: No specific trade-policy catalyst featured in today's reporting, so changes in UK trade arrangements or tariffs would affect GBP/USD only indirectly through growth expectations.
• Monetary Policy: The BoE's recent hike to 4.00% with markets pricing further tightening supports the Pound, although analysts see a shallower path ahead.
Technical Outlook
• Trend: GBP/USD keeps a modest bullish bias above the 100-day SMA and the Bollinger middle band, with the RSI near 57 supporting constructive momentum.
• Resistance: Resistance appears at the 61.8% retracement near 1.3467 and the 1.3500 level, with the upper Bollinger band just above current price.
• Support: Initial support is the 200-day SMA near 1.3421, followed by 1.3400 and the 1.3359 cluster of moving averages.
• Forecast: GBP/USD could retest 1.3500 if CPI cools and the Dollar slips, whereas a break below 1.3400 would expose 1.3359.
Sentiment and Catalysts
• Market Sentiment: Sentiment toward the Pound is constructive on the BoE's tightening stance, although traders could stay on the sidelines until the US CPI result.
• Catalysts: Today's US CPI, UK data, BoE commentary and US-Iran headlines could determine the pair's next move.
EUR/USD Forecast
Current Price and Context
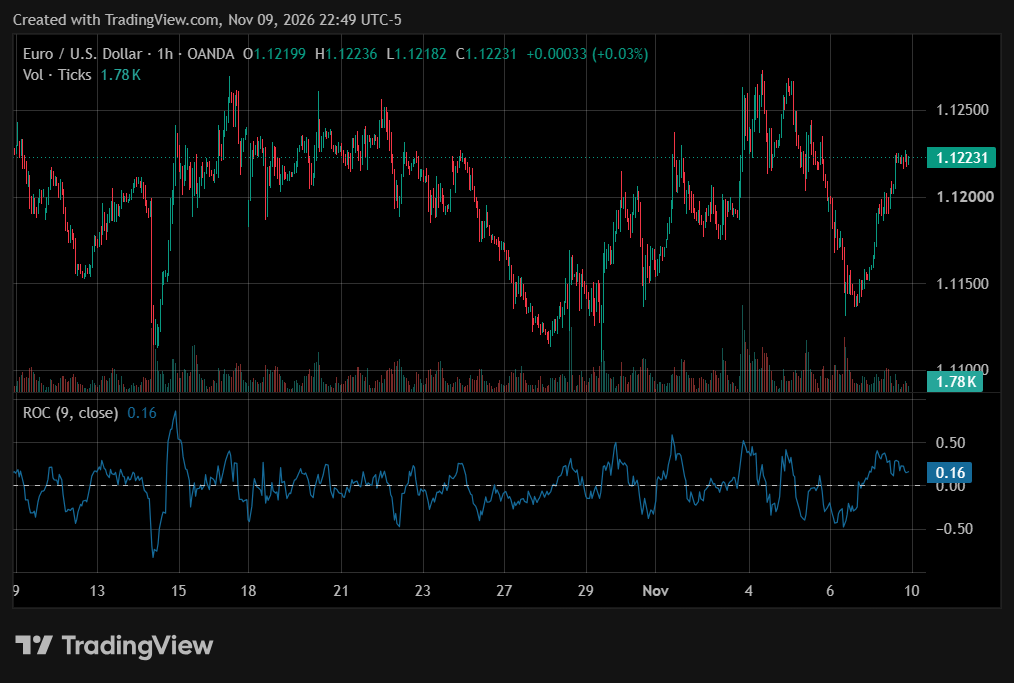
EUR/USD slipped to around 1.1220 during Asian hours on Tuesday, 10 November 2026, after modest gains on Monday, as the US Dollar gained ground ahead of US CPI despite growing speculation of a US-Iran deal. The Euro faces headwinds from political and fiscal instability in France and uncertainty over reports of ECB President Lagarde's potential early departure, although falling crude oil prices and stabilizing markets could offer underlying support.
Key Drivers
• Geopolitical Risks: A US-Iran deal that lowers energy prices would support the Euro as a net energy importer, while renewed escalation or failed talks could lift oil and weigh on EUR/USD.
• US Economic Data: Today's US CPI could reset Fed hike expectations, with a hot print likely to push EUR/USD toward 1.1130 and a soft print likely to support a move above 1.1250.
• FOMC Outcome: December Fed hike odds near 84% and Deutsche Bank's call for hikes in December and March keep the Fed hawkish, which could cap EUR/USD even as oil falls.
• Trade Policy: No specific trade-policy catalyst featured in today's reporting, so changes in tariffs or trade restrictions affecting euro area exports would influence EUR/USD only indirectly through growth expectations.
• Monetary Policy: Uncertainty over Lagarde's possible early departure and ECB leadership could undermine confidence in the ECB's policy path, although earlier hawkish ECB commentary pointing to a December hike remains a support.
Technical Outlook
• Trend: EUR/USD keeps a bearish tone on the daily chart despite its rebound from lows near 1.1130.
• Resistance: Resistance appears at 1.1250-1.1265, followed by the 1.1270 level.
• Support: Initial support is the 1.1163 pivot level, followed by the 1.1130-1.1135 zone and the 1.1100 psychological level.
• Forecast: EUR/USD could retest 1.1250 if CPI cools and oil keeps falling, whereas a hot CPI print would expose 1.1163 and 1.1135.
Sentiment and Catalysts
• Market Sentiment: Sentiment toward the Euro is cautious because French instability and ECB leadership uncertainty offset the benefit of lower energy prices, although Ebury expects a medium-term euro rebound.
• Catalysts: Today's US CPI, French political and fiscal developments, ECB leadership headlines and US-Iran talks could determine the pair's next move.
USD/CAD Forecast
Current Price and Context
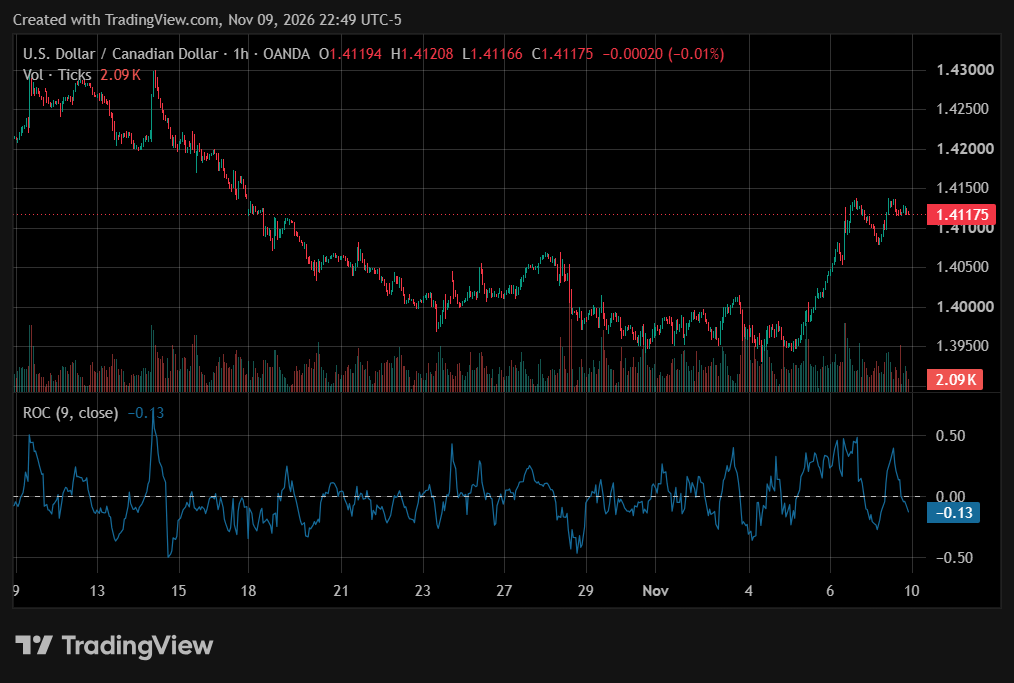
USD/CAD inched higher to around 1.4120 during Asian hours on Tuesday, 10 November 2026, after minor losses on Monday, as the commodity-linked Canadian Dollar struggled with lower oil prices. The US Dollar is gaining ground despite speculation about a US-Iran deal, with WTI falling below $85.50 and traders waiting for US CPI.
Key Drivers
• Geopolitical Risks: Rising US-Iran deal bets are pushing oil lower, which weighs on the commodity-linked Canadian Dollar, although a collapse in talks could lift oil and support the Loonie.
• US Economic Data: Today's US CPI could keep Fed hike expectations elevated and support USD/CAD if hot, while a soft print could pull the pair lower.
• FOMC Outcome: December Fed hike odds near 84% and a hawkish Fed bias keep rate differentials supportive of the Dollar against the Loonie.
• Trade Policy: No specific US-Canada trade-policy catalyst featured in today's reporting, but US-China tariff easing improves global trade sentiment, while any US tariff shift on Canada would affect the Loonie through growth expectations.
• Monetary Policy: The Bank of Canada's recent hike to 2.50% supports the Loonie, although the Fed's hawkish stance and weaker oil limit the benefit.
Technical Outlook
• Trend: USD/CAD holds a constructive near-term bias above its nine-day and 50-day EMAs on the daily chart.
• Resistance: Resistance appears at the Bollinger middle band near 1.4140, followed by the upper band toward 1.4350 as an indicative level.
• Support: Initial support is the 1.4047-1.4080 area where the 100-day SMA and the October range top sit, followed by 1.4000.
• Forecast: USD/CAD could test 1.4140 if CPI is hot and oil stays weak, whereas a soft print could pull it back toward 1.4047.
Sentiment and Catalysts
• Market Sentiment: Sentiment toward the Loonie is weak on falling oil prices and a firm Dollar, although the BoC's tighter policy offers some support.
• Catalysts: Today's US CPI, oil prices tied to US-Iran talks, Fed commentary and Canadian data could determine the pair's next move.
Wrap Up
US CPI anticipation and mixed US-Iran deal signals are the main themes, with the Dollar consolidating near 101.70, oil sliding, the kiwi and Pound holding recent gains, the Euro pressured by French and ECB uncertainty, and USD/CAD supported by weaker crude. Today's US CPI at 13:30 GMT, Friday's US PPI, Fed speakers, December hike pricing near 84% and US-Iran negotiations are the principal catalysts. Traders should monitor whether inflation data confirms or fades Fed hike expectations and whether key technical levels hold, remembering that every scenario in this report is conditional.
Ready to trade global markets with confidence? Join Moneta Markets today and unlock 1000+ instruments, ultra-fast execution, ECN spreads from 0.0 pips, and more! Start now with Moneta Markets!
Sterling’s Rebound Faces US Inflation Hurdle
EURUSD plummeted from its high
Gold, GBPUSD, EURUSD
Easing US-Iran Tensions and US-China Trade Optimism Shape Global Markets | 9th November, 2026
US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026
The dollar saves the day
Tech Stocks Lead US Selloff Ahead of Payrolls