






Volatility after Bank of Japan tweaks policy

OVERNIGHT
Markets were volatile during the Asian trading session after the Bank of Japan unexpectedly tweaked its yield curve control (YCC) policy, with indications that it will be implemented more flexibly. Japanese 10-year bond yields rose and the policy move has added to speculation of eventual policy normalisation by the BoJ. The Bank kept its short-term interest rate at -0.1%. Otherwise, markets continued to digest yesterday’s ‘dovish’ hike from the ECB which weighed on the euro. Stronger than expected US Q2 GDP data yesterday also lifted US Treasury yields.
THE DAY AHEAD
There are no major UK data releases in today’s calendar. Next week’s focus will be the Bank of England policy decision on Thursday with interest rates expected to rise by at least 25bps to 5.25%, with markets attaching a sizeable risk of another 50bp increase to 5.5%. Today’s schedule is busier for the Eurozone and the US. Earlier this morning, France released its first estimate of Q2 GDP showing firmer than predicted quarterly growth of 0.5% after a downwardly revised increase of 0.1% in Q1. Spain also reported a rise of 0.4% for Q2. German and Eurozone Q2 GDP figures will be released on Monday. Indications so far point to a return to Eurozone growth in Q2 but business surveys indicate weakening demand which poses downside risks for the second half of the year.
France also released preliminary July CPI inflation earlier today which fell to 5.0% from 5.3% in June on the EU-harmonised measure, the lowest since February 2022. Germany will release its July inflation later today, preceded by the usual slew of regional CPI reports through the morning. As well as GDP, the Eurozone July flash CPI will also be released on Monday and we are looking for the headline rate to fall further from June’s 5.5%. Policymakers, however, will be watching core inflation closely, because it has been stickier than the headline rate.
There are some important US data releases today. We expect the June personal spending to increase by 0.5%, while the PCE deflator (the Fed’s preferred inflation measure) is expected to fall to 3.1% from 3.8% in May. The core measure is forecast to decline to 4.2% from 4.6%. The Q2 employment cost index is also closely watched by the Fed as a gauge of wage pressures. We expect it to show a rise of 1.2%q/q, matching the Q1 outturn. A weaker figure would increase the odds of the Fed holding rates in September.
MARKETS
The euro fell yesterday after the ECB indicated that it may pause at the next policy meeting in September. The US dollar was also boosted by a stronger outturn for Q2 GDP. Both EUR/USD and GBP/USD fell as a result. The Japanese yen was volatile overnight after the BoJ announced YCC tweaks.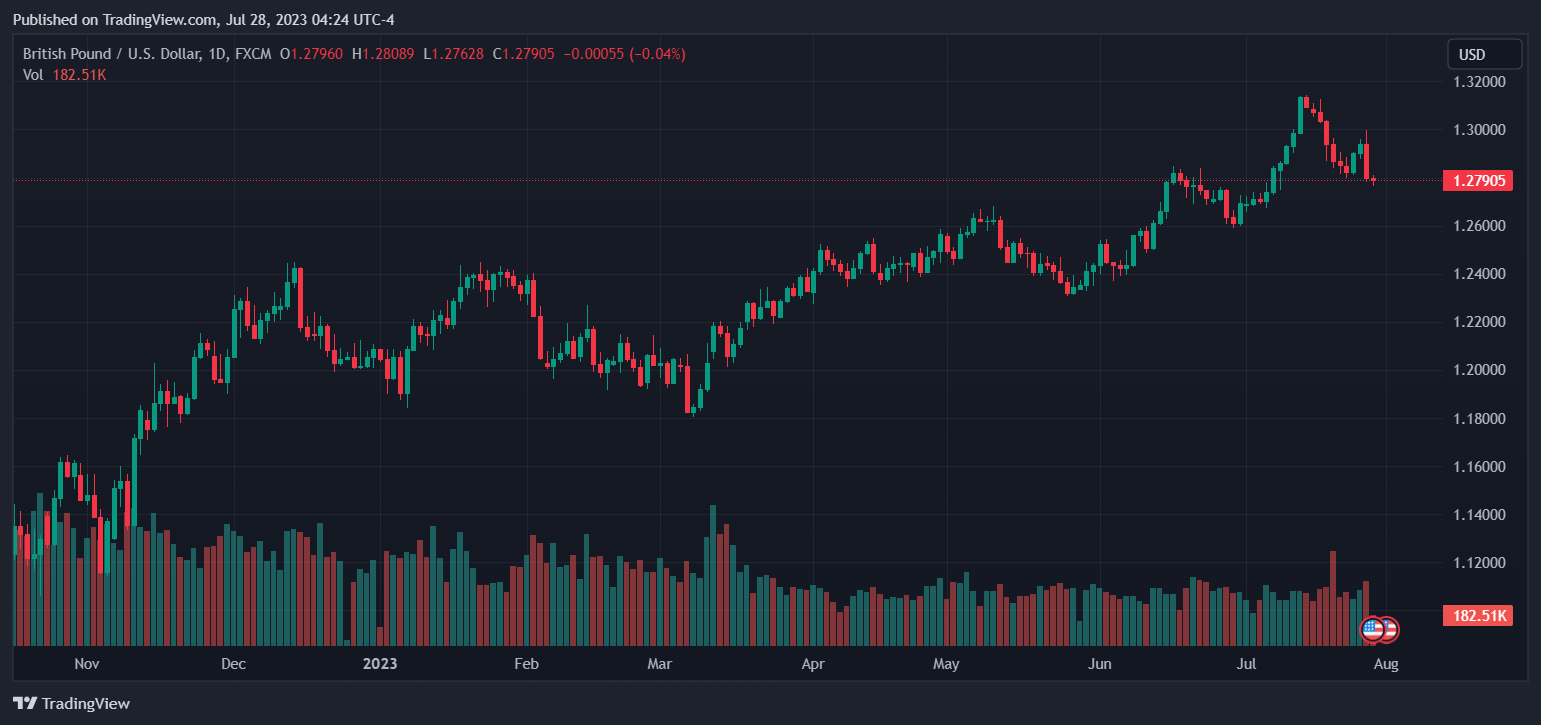


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

The euro has spread its wings

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback






