






BoE Governor to deliver keynote speech at BCC conference

OVERNIGHT
Equities were trading mixed across the Far East with most major indices trading lower, in keeping with the softer risk tone backdrop, albeit Japan stocks are up on the day following better-than-expected data. Japan’s economy expanded at an annualised pace of 1.6% in the first quarter – twice the rate expected by the Bloomberg consensus. The Q4 2022 outturn was revised lower, however, to -0.1% from +0.1% meaning that the Japanese economy experienced a recession in the second half of last year.
THE DAY AHEAD
Today’s economic calendar is light with no major releases due in the UK or Eurozone, while in the US the focus is limited to building permits and housing starts data for April. Nevertheless, US data should provide some insight into how the housing sector – one that is likely to be more acutely affected by the sharp rise in US interest rates – is faring in the current climate. Data for March showed a sizeable decline in permits issued on the month, which is likely to weigh on housing starts activity in April and we look for a 1.4% fall. More broadly, however, reports of low housing inventories and some signs of stabilisation in home sales and prices suggests that the recent pick up in underlying activity may have further to go and we look for building permits to have risen in April.
Elsewhere, the Eurozone CPI report for April is a final reading, which is not expected to be revised from the 7.0%y/y ‘preliminary’ outturn. Nevertheless, the additional detail that comes with the final print should provide further insight into the current drivers of underlying price pressures in the bloc. While goods price inflation has shown continued signs of moderation, the extent to which elevated price pressures are broad across the services sector will be closely watched for in the final release as an indication of how persistent above-target core inflation will prove to be.
A number of ECB officials are due to speak throughout the day and the outlook for inflation is likely to feature heavily in their commentary. Interest rate markets are factoring in a cumulative 47bp of rate increases over the coming months with a quarter-point rise at the June meeting seen with a c.90% probability.
In the UK, some attention is likely to be on Bank of England Governor Andrew Bailey’s keynote speech at the British Chambers of Commerce Global Annual Conference (10:50BST). The focus of the event is on discussing opportunities for growth, which is likely to touch upon a number of topics including the UK’s disappointing rate of productivity growth, as highlighted in yesterday’s labour market report.
MARKETS
US 2-yr Treasury yields rose above 4% yesterday as comments from a number of Fed officials, including Mester, Barkin, Bostic and Goolsbee indicated that the door to further interest rate rises in the US was far from closed especially if inflation continued to be stubborn.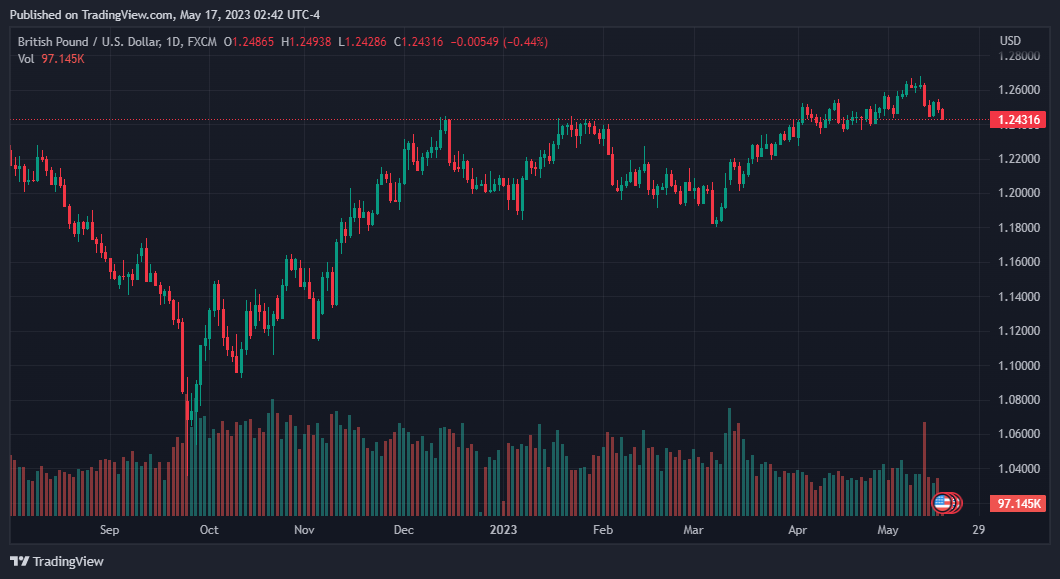


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






