






Central bank speakers in focus amid Middle East tensions

OVERNIGHT
Equities have started the week lower across the Asia Pacific, following on from losses seen across US and European markets on Friday as developments in Israel/Palestine continued to weigh on sentiment. Stocks are also lower across China despite the country’s central bank making the largest medium-term liquidity operation since 2020 in a bid to support the nation’s economic recovery. Meanwhile, exit polls and a partial vote count for the elections in Poland, indicate that the Civic Platform ‘opposition’ party, which is headed up by former European Council President Donald Tusk, is on track for a majority.
THE DAY AHEAD
It’s a relatively quiet start to what is an otherwise busy week for data releases, particularly in the UK. The lack of any major data prints means that the market’s focus will be on ongoing tensions in the Middle East as well as comments from major central bank members in the run up to the next round of policy announcements. Domestically, the Bank of England’s Chief Economist, Huw Pill, is scheduled to speak at an event organised by OMFIF at which he will deliver his latest views on the UK economic outlook. Last week’s UK GDP report showed a smaller than expected rise in output in August, alongside a downward revision to the July figure, and put the economy on track to record a weaker outturn for Q3 GDP overall. That is likely to be seen as providing further evidence that the rate hikes delivered so far (515bp worth since December 2021) are having the desired effect. Mr Pill was one of the 5 majority members that supported leaving rates on hold at the last meeting and markets will be watching his speech for clues that this still remains the case, particularly with the 2nd November meeting fast approaching.
Elsewhere, the focus will be ECB members Villeroy and de Cos, while in the US, the Fed’s Harker is due to speak – who is a voting member on the FOMC this year. Mr Harker has been one of a number of committee members that have suggested that interest rates may stay on hold next month, indicating that the rise in bond yields over recent weeks may have substituted for an actual policy rate rise.
Early tomorrow, the ONS will make a partial release of the monthly labour market data with earnings, vacancies and HMRC payrolls data provided but LFS data (including employment and unemployment) delayed until next week due to data quality issues. For wage growth, we look for signs that it is moving in the right direction (lower), but it will likely remain too high for comfort for BoE policymakers. Total pay growth is forecast to fall to 8.3% from 8.5%, while regular pay growth (excluding bonuses) is expected to be unchanged at 7.8%. However, we forecast private sector regular pay growth to edge lower for a second straight month.
MARKETS
Brent crude oil has held on to Friday’s sharp gain and continues to hold above $90pb. The US dollar is slightly softer, albeit GBP/USD continues to trade below 1.22.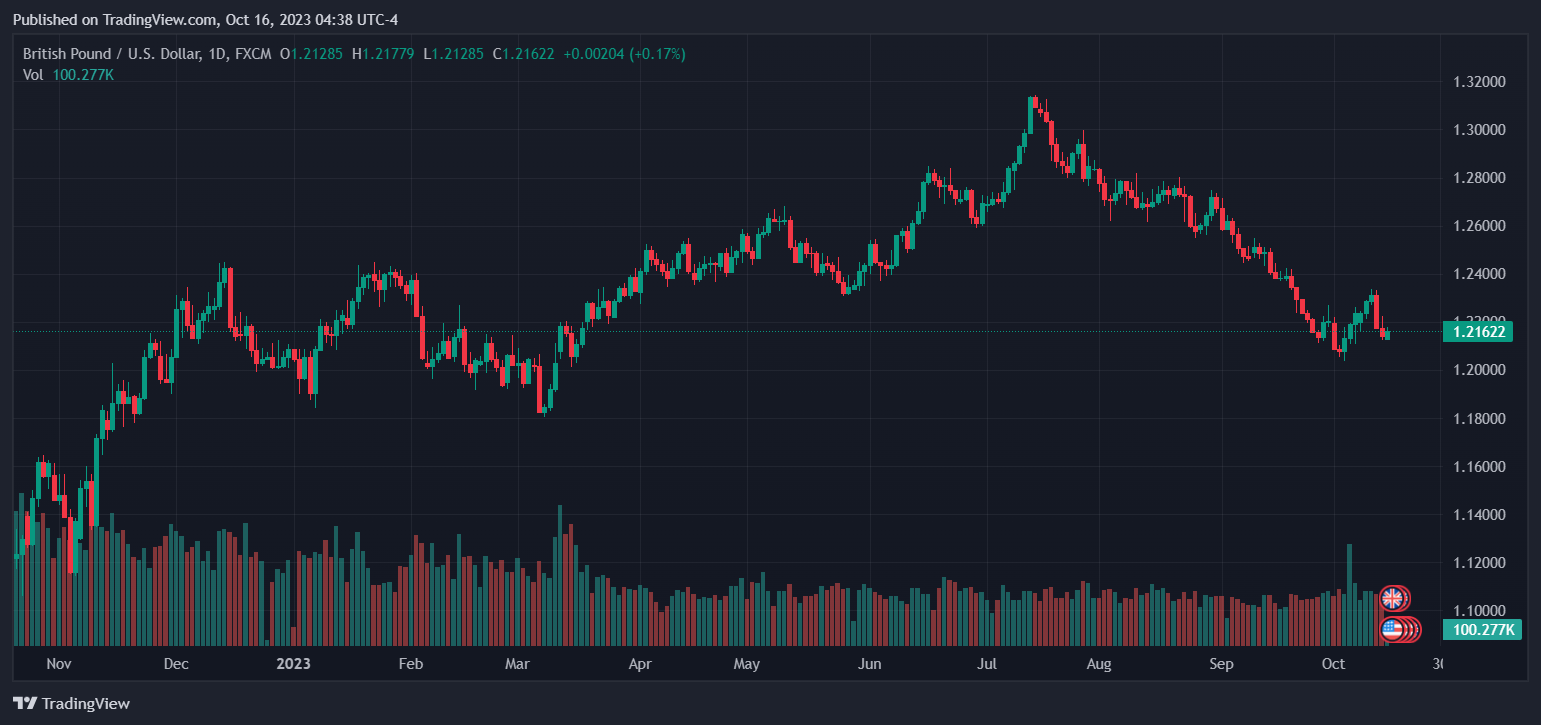


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






