






China stimulus measures hope buoy equities

OVERNIGHT
Equities across the Asia Pacific region were mostly trading higher, buoyed by hopes that the end of rate hiking cycles were in sight. Chinese stocks were particularly supported by the announcement from Beijing of further measures aimed at boosting consumption and supporting the nation’s property sector – further details are expected to be announced later today. The latest measures come amid further signs of a weakening in the country’s economic growth momentum. Earlier this morning, the ‘official’ China PMIs showed the manufacturing sector was in contractionary territory for a fourth consecutive month in July, while activity in the non-manufacturing sector rose at its slowest pace this year.
THE DAY AHEAD
Following as expected decisions from the US Federal Reserve and European Central Bank – where both raised policy rates by 25bp – the coming week’s focus will be on the Bank of England (BoE) latest policy decision. The outcome here is more uncertain with both markets and the consensus split between expecting a 25bp and 50bp increase, albeit both are currently leaning towards the former.
Ahead of the outcome, UK data prints are limited, although today’s Bank of England money and lending data will provide some food for thought. Mortgage approvals have fallen by a third since the BoE started raising interest rates. Indeed, a gauge of new buyer interest from the RICS dropped to its lowest since October 2022 last month (see chart), pointing to a further moderation in mortgage in the near term. That said, we think that mortgage approvals rose in June as borrowers scrambled to lock in fixed rates in response to the rise in wholesale borrowing costs. We look for 53.0k mortgages to have been approved in June, up from 50.5k in May.
Elsewhere, in the Eurozone, the first estimate of Q2 GDP and July CPI will be released later today. Partly reflecting surprisingly strong French GDP figures and despite flat German data already released, we expect the Eurozone economy to have expanded by 0.3%(q/q) in Q2 after the flat outturn in Q1. Business survey indicators, however, suggest demand is slowing which poses downside risks for the second half of the year. We also expect Eurozone July flash CPI to edge down to 5.3% in July from 5.5% in June, but look for a smaller fall in core CPI (excluding energy and food) inflation to 5.4% from 5.5%.
Early tomorrow morning, the Reserve Bank of Australia will provide its latest policy update. That decision looks likely to be finely balanced between a 25bp rise and no change after recent mixed economic data. Ahead of that, our latest Business Barometer will be published.
MARKETS
Market moves have been fairly limited, albeit the US dollar is marginally firmer overnight, while US yields are up slightly too. GBP/USD is broadly unchanged around 1.2850.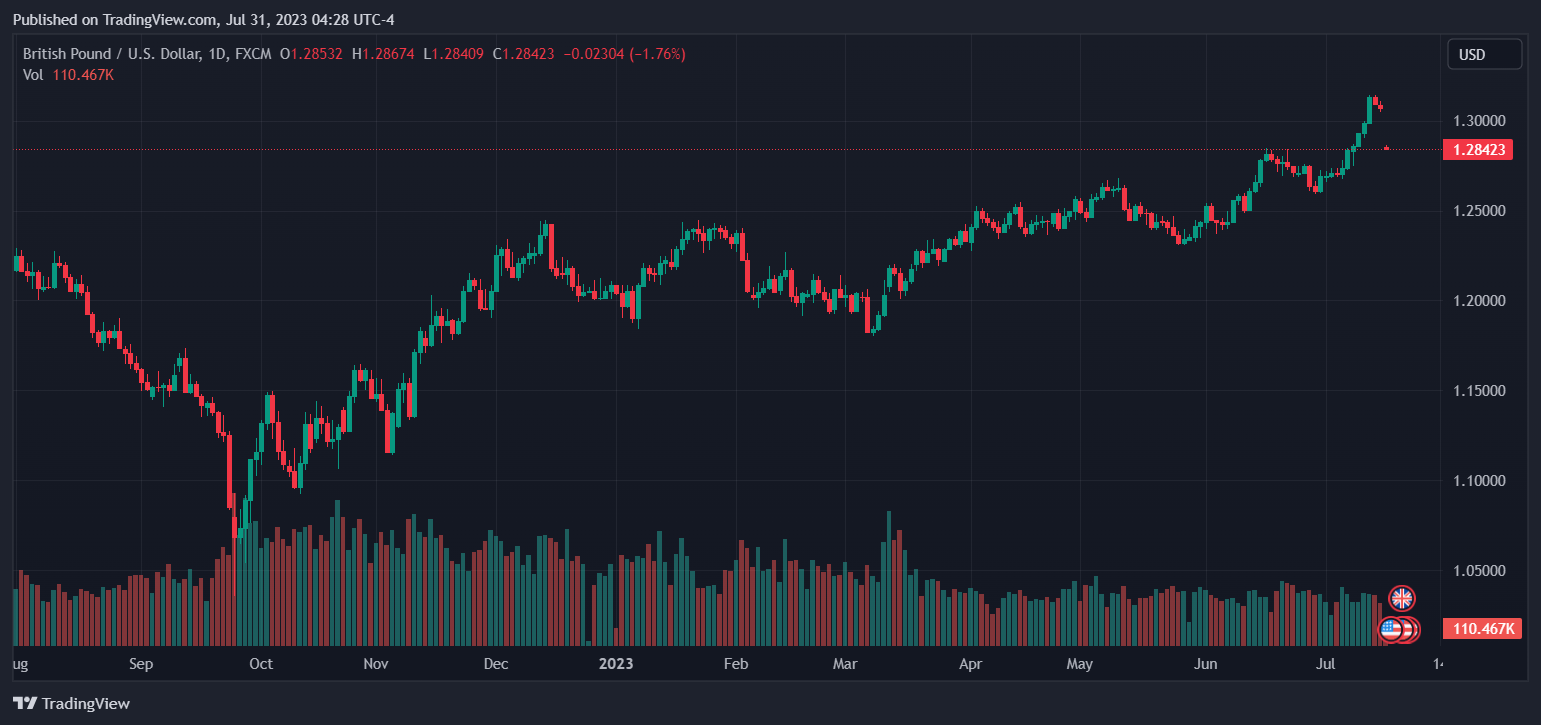


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






