






Dollar gains as risk-off reaction deepens

Market nervousness persists
Despite yesterday’s attempt by risk markets to overcome the initial geopolitics-induced risk-off reaction, momentum remains negative and extremely fragile. Expectations for a swift joint US-Israel operation are not being confirmed as President Trump talked about an operation that would last more than 4-5 weeks and Israeli PM Netanyahu stated that “action against Iran may continue for some time”.
This answers, to a certain extent, the main question of duration posed by investors. A repeat of the mid-June 2025 events would be the optimal scenario for risk takers, but if a regime change, along with eliminating Iran’s nuclear capabilities, is indeed the primary objective, the current hostilities might drag on longer than most would hope for, unless of course the Iranian regime is toppled over the next week, paving the way for a new administration.
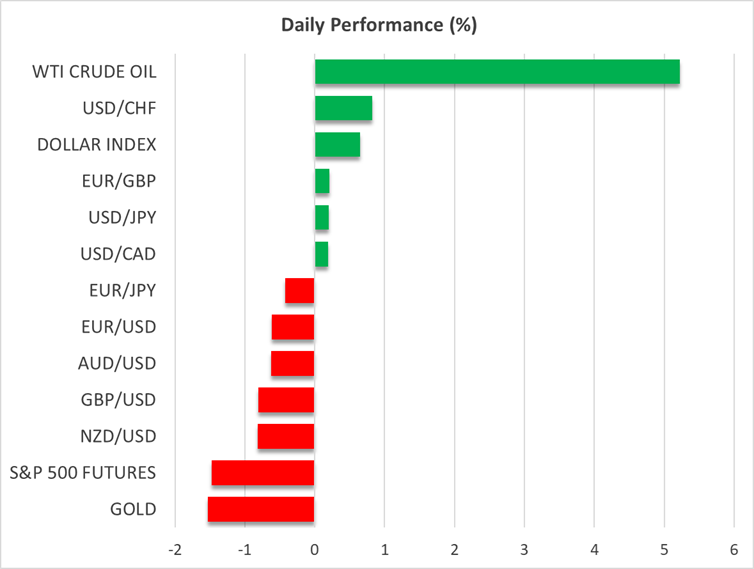
Consequently, economists have started to speculate about the damage done to the real economy, mostly due to the increase seen in oil prices, and the likely additional rises under the most adverse market scenarios. At the time of writing, WTI oil futures are trading north of $73, reacting to yesterday’s downward pressure. A move above $75 could open the door to a sustained rally towards the June 2025 high, when the previous Israel-Iran conflict caused an oil surge.
Rate cut expectations have taken a hit, with the market pricing in just 49bps of Fed easing during 2026, down from the high of 63bps posted in mid-February. Similarly, BoJ rate hike bets have gotten boosted, with almost two rate hikes penciled in for 2026.
Weird market reaction
While all eyes remain on oil prices and on the newsflow regarding the possible closure of the Hormuz Strait, equity indices are in the red, led by European indices. This is a typical reaction as the Eurozone is extremely dependent on foreign oil and gas supplies, with the expected price hikes potentially significantly curtailing growth momentum.
However, things become confusing when putting together the moves seen in gold, US Treasury bonds and the dollar. Gold is losing ground after the initial rally above the $5,400 level, while US sovereign yields are rallying, with the 10-year US yield quickly climbing 16bps from Sunday’s lows to 4.09%. Most analysts attribute this rise to inflation fears, which should have caused a sustained rally in gold prices – the exact opposite of what is happening in gold at the moment.
Meanwhile, the US dollar is the key beneficiary of geopolitical developments, outperforming its major FX peers. A close below the 200-day simple moving average (SMA) at 1.1665 in euro/dollar could open the door for an eventual test of the lower boundary of the current wide rectangle at 1.1475. Interestingly, the SNB probably intervened yesterday, helping the euro/Swiss franc pair rise from its multi-decade low.
The aforementioned moves, with investors switching to dollars but shunning both equities and gold, create interesting questions: do they feel more comfortable remaining liquid? Are they potentially preparing for an even harsher risk-off reaction, aiming to enter the US equity markets at lower levels?
Volatility traders are probably the most pleased at this stage. There has been a marked increase in one-month implied volatilities across the board, with oil, pound/dollar and DAX 40 index volatility jumping to the highest level of the past 30 days. Interestingly, gold, silver and the Nikkei 225 index volatilities have posted the smallest jumps.
Light data calendar, rich Fedspeak
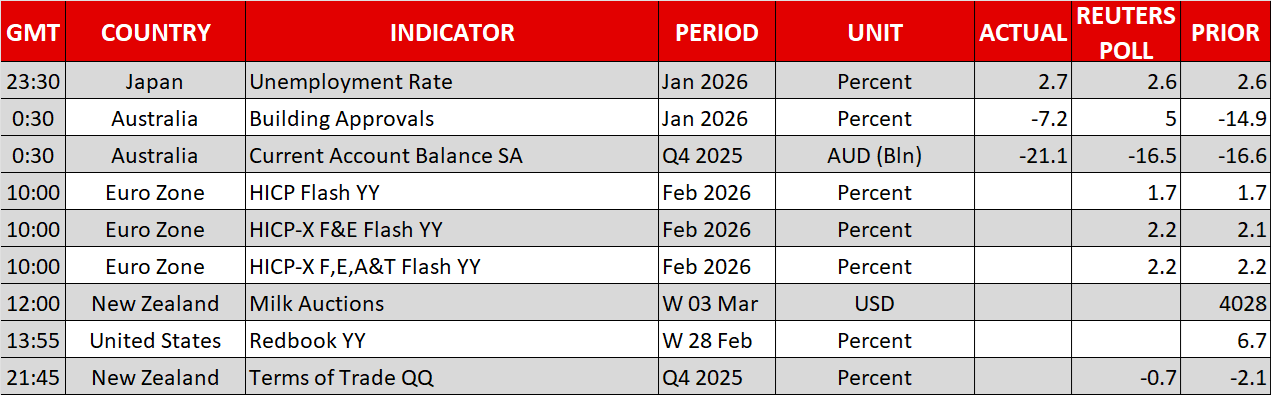
Amidst the unravelling events in the Middle East, the data calendar is rather light today, with investors mostly focused on tomorrow’s Eurozone final HCOB Services PMIs, the pivotal ADP employment report and the ISM Services PMI figures. That said, Fedspeak is rich today, with New York’s Williams, Kansas City’s Schmid and Minneapolis’ Kashkari speaking, and Q&A sessions mostly centred on the impact of geopolitics on monetary policy.


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






