






ECB central bank conference kicks off in Sintra

OVERNIGHT
Equities across the Far East are mostly trading lower this morning, as concerns around the pace of growth in China continues to weigh on regional sentiment. US and European equity futures, however, have edged up and point to gains on their open. Despite reports of a failed coup attempt in Russia over the weekend there has not been a material shift in market risk sentiment, though Brent crude oil prices have stabilised following last week’s ~4% decline.
THE DAY AHEAD
Today’s German IFO survey for June will provide some further insight into trends across the Eurozone’s largest economy, following Friday’s PMI updates. That data showed the manufacturing sector fall deeper into contractionary territory (41.0 vs 43.2 in May), while the pace of service sector activity slowed more sharply than expected (54.1 vs 57.2 in May). Having posted a second successive quarter of contraction in Q1, signs of moderation in survey measures of business activity raise the risk that the German economy also failed to expand in Q2. We forecast the current conditions (93.3 vs 94.8) and expectations (87.4 vs 88.6) components to print lower versus the previous month, consistent with a further cooling in German activity.
Elsewhere, ECB President Lagarde will deliver opening remarks at the start of the ECB’s central banking conference in Sintra. In the face of moderating activity, inflation across the Eurozone remains sticky. It seems unlikely that the coming week’s Eurozone inflation data will seriously question this because, while we forecast a sizeable fall in annual headline inflation (to 5.5% from 6.1% in May), we also expect a modest rise in the core rate to 5.5% from 5.3%. Overall, those outturns seem unlikely to leave ECB policymakers any less worried about the inflation outlook. We expect this concern to be reflect in Ms Lagarde’s comments later today. Ahead of that, ECB member Villeroy is due to speak at a separate event (08:15 BST).
In the UK, Bank of England external member Swati Dhingra is set to deliver a speech this morning at a ‘UK Women in Economics’ network. Ms Dhingra was one of two members of the MPC that voted against the latest increase in interest rates, to 5%, preferring to keep them at 4.50%. However, as she is clearly in the minority, her comments may be seen by markets as less indicative of how much further the committee may hike in coming months.
On the UK data front, following hot on the heels of last Friday’s ‘official’ ONS update for May, the CBI’s survey-based measure of retail sales will provide insight into June trends. While the headline reported sales balance is expected to edge up to -8 from -10 in May, that would still be a second consecutive print in negative territory.
MARKETS
Following gains last week, the US dollar is relatively unchanged in early trading. GBP/USD continues to hold above the 1.27 mark, albeit it is off the highs made last week following the Bank of England’s unexpected decision to raise interest rates by 50bp and not 25bp.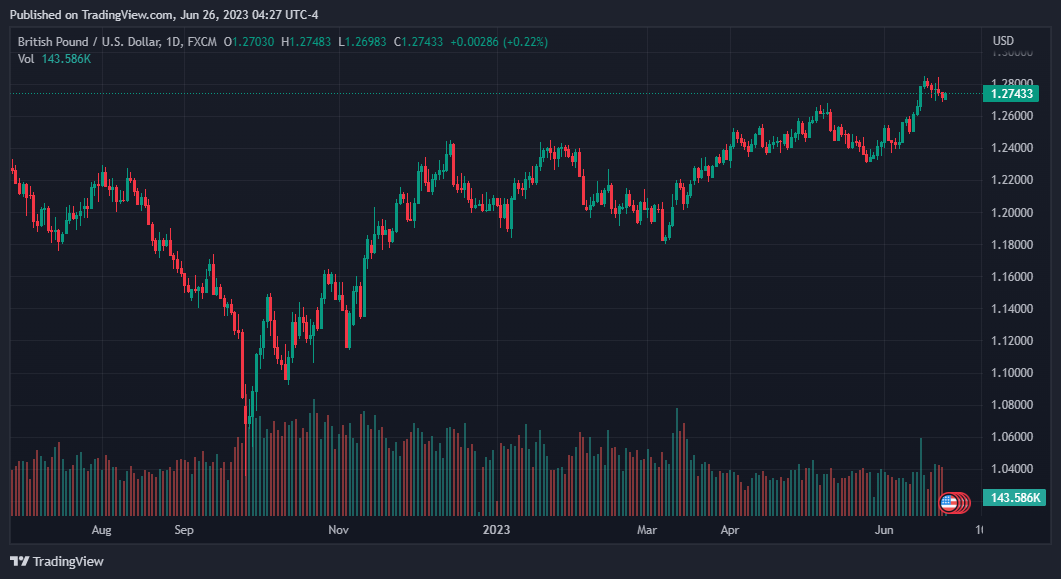


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






