




First indications of Eurozone inflation due

OVERNIGHT
Asian equity markets were mixed despite the positive close in the US, with fluctuations attributed to profit-taking at the end of the quarter. There was little news on the economic front to drive markets. As a result, currencies and US Treasury yields remained within narrow ranges. Comments yesterday from the ECB’s Schnabel attracted some attention: she said there has been a shift from overnight deposits into time deposits but the ECB had not seen a general outflow of deposits from banks.
THE DAY AHEAD
With no major UK data today, the domestic focus will be on early tomorrow morning’s releases. The ONS is expected to confirm flat quarter-on-quarter GDP growth in Q4 last year. There will be an update on the household saving ratio to assess the degree of precautionary savings and therefore prospects for consumer spending. The ratio jumped up to 9.0% in Q3 but that was largely a result of technical factors related to the gilt yield spike on pension entitlements. A more up-to-date view on economic conditions will be revealed tomorrow in our own Lloyds Bank Business Barometer for March with confidence having trended higher since last November’s low point.
Later today, the first indications of Eurozone March inflation will be revealed by German and Spanish data ahead of the Eurozone flash estimate on Friday. French inflation is also due early Friday. Markets will be looking for signs of a sharp fall in headline inflation due mainly to energy price base effects. Germany’s EU-harmonised inflation measure is forecast to fall to 7.5% from 9.3%. Core inflation, however, is expected to remain elevated. The Eurozone economic sentiment survey will also be released today.
The latest iteration of US Q4 GDP is expected to be unrevised at 2.7% (annualised). US weekly jobless claims are due as usual on Thursday and are expected to remain low, suggesting little evidence in the data so far of anecdotal reports of layoffs in parts of the economy. US attention will be on Friday’s PCE deflator, the Fed’s preferred inflation gauge.
In Asia early Friday, Tokyo CPI for March will be released before the national data for Japan as a whole. It is expected to fall to 3.2% from 3.4% on the headline measure and to 3.1% from 3.3% for the core measure excluding fresh food. The BoJ under new Governor Ueda is not expected to immediately change the yield curve control policy. China’s March PMIs will also be closely watched for further signs of economic rebound after the zero-Covid policy was aborted. That could have an impact on global inflationary pressures, including on commodity prices, but it may also ease global supply pressures.
MARKETS
Currencies remained in narrow ranges overnight with GBPUSD up marginally. UK 10-year gilt yields closed higher for a third day, while US 10-year Treasury yields were little changed in Asia. Markets await inflation data particularly from the US and the Eurozone in the remainder of the week.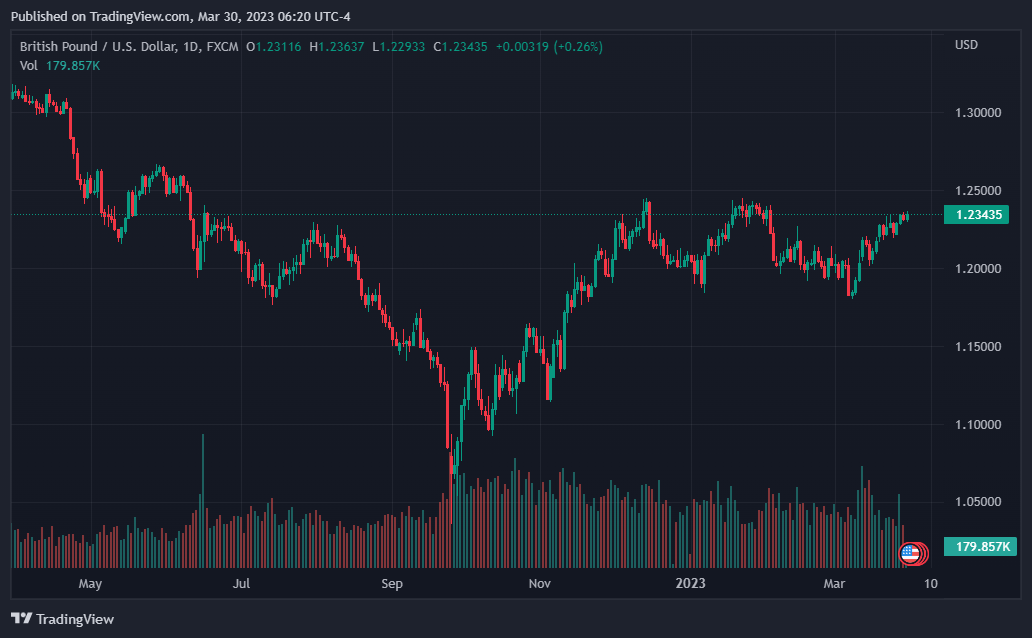
US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026
The dollar saves the day
Tech Stocks Lead US Selloff Ahead of Payrolls
GBPUSD bull run: Can the pair smash through 1.3565?
Democrats' Midterm Victory Sends Dollar and Oil Lower
US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback
US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026