






Focus on central bank speakers

OVERNIGHT
Stocks across the Asia-Pacific region were trading mixed as market participants continue to debate whether further interest rate increases were forthcoming or not, particularly following last Friday’s mixed US labour market report. In Germany, the latest read on industrial activity showed output fell by 1.5% m/m in June, a much bigger fall than the 0.5% drop expected. The outturn follows a string of weak activity readings from Germany and means that the level of industrial output was the lowest since December. Meanwhile, the latest results of the REC/KPMG jobs survey provided some further signs that the UK labour market is loosening. Recruiters reported a jump in the number of people looking for work and a drop in demand for staff.
THE DAY AHEAD
Following recent updates from the US Federal Reserve, ECB and Bank of England – at which each raised policy interest rates by 25bp – there is now a sizeable time gap to the next set of policy updates from mid-September onwards. All three central banks have kept their policy options open by saying that any further hikes are ‘data dependent’. That guarantees a particularly close focus by markets on data releases over the current holiday period. For now, markets are attaching about an 85% probability to a September rise from the BoE, while the prospect of September moves from the ECB and Fed are seen as much less likely at 36% and 16% respectively.
Datawise, the key release of the week will be the July US CPI report on Thursday. Ahead of that, today’s calendar offers little in the way of major distractions, but comments from Fed members Bowman and Bostic should attract some interest, especially the former who is a voter on the FOMC this year. Speaking over the weekend – and one of the few that have after Friday’s mixed US labour market report – Bowman indicated that more rate hikes were likely needed to bring inflation to 2%, suggesting that she is likely to favour another quarter-point increase at the September meeting. Bostic, on the other hand – who also spoke after Friday’s labour market report – said that he didn’t see any need for additional hikes (albeit he is a non-voter on the FOMC this year).
Elsewhere, the Eurozone Sentix investor confidence survey is expected to have dropped for a fourth consecutive month, to -24.5 in August from -22.5 in July. Domestically, comments from Bank of England chief economist Huw Pill will be closely watched for clues on the prospect of a further rise in interest rates next month. Speaking on Friday, Mr Pill noted that there were greater risks that inflation will persist in the UK, in keeping with the market’s view that the BoE is not yet done raising interest rates.Overnight, the British Retail Consortium’s sales measure will provide an early indication of domestic retail spending in July.
MARKETS
The US dollar is trading higher on the day, reversing some of the fall seen in the aftermath of Friday’s US jobs report. GBP/USD is edging towards 1.27.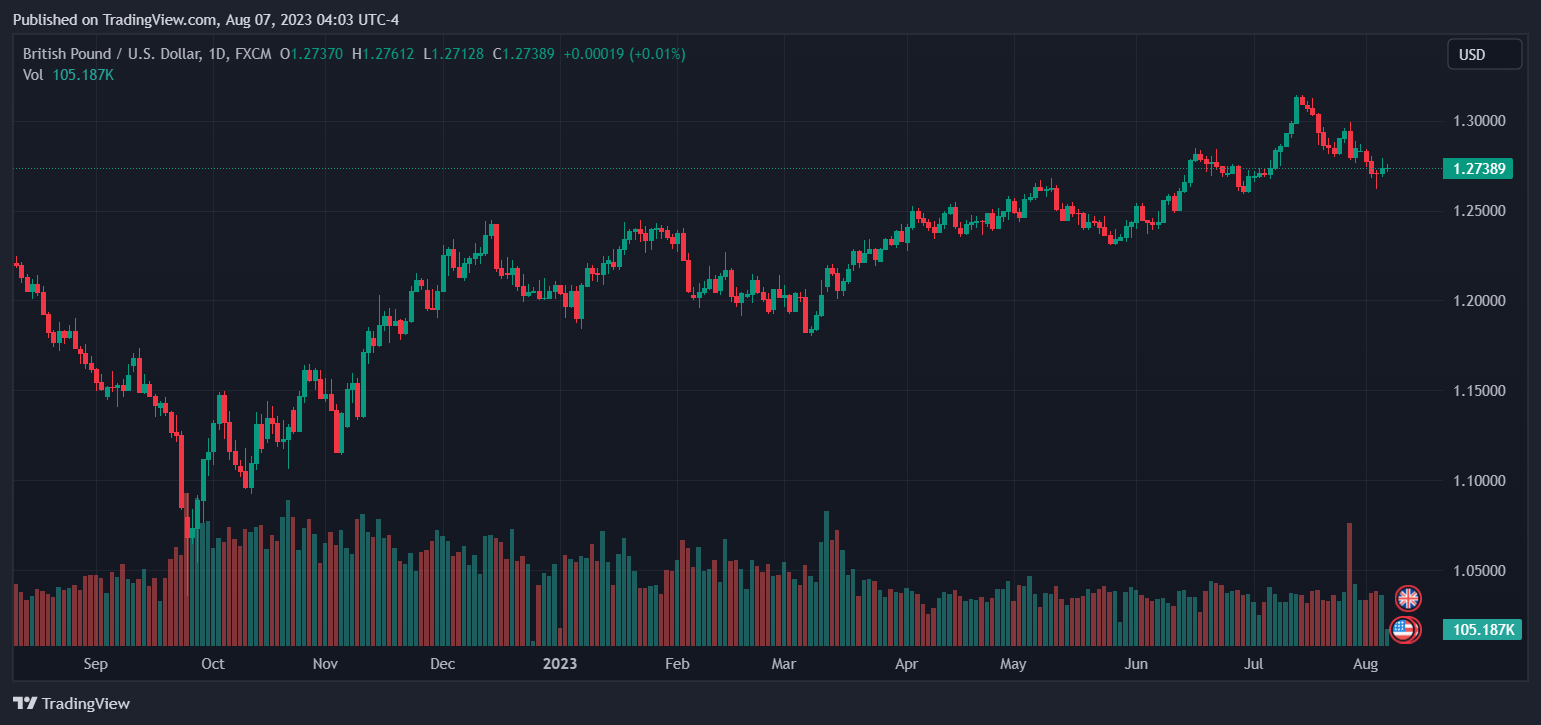


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






