






Inflation risks weigh on global risk appetite

OVERNIGHT
Asian equity markets remain under pressure after yesterday evening’s Fed minutes of the July meeting pointed to inflation risks and the possibility of further interest rate hikes. Concerns about China’s economic prospects, including its property sector, also persist. Australia’s unemployment rate, meanwhile, rose more than forecast to 3.7% in July from 3.5% in June. Markets currently attach a low probability to a September Fed hike, but US interest rates are expected to remain in restrictive territory for a while, with interest rate cuts not priced in until next spring at the earliest.
THE DAY AHEAD
In the absence of major UK data today, the domestic focus turns to early Friday releases of the August GfK consumer confidence survey and official retail sales figures for July. We have already seen key labour market and CPI inflation reports earlier this week which revealed upside surprises to wage growth and services inflation, increasing conviction levels of another rise in Bank of England interest rates next month. The UK economy, moreover, has also held up better than expected in the first half of the year.
There are concerns, however, that the impact of interest rate increases in the UK will be seen more in the second half of the year. July retail sales may be seen as an early indicator of that and we predict a 1.5% monthly decline which would be equal to the biggest drop seen in the past two years. Retail sales prints, though, are notoriously erratic. That outturn would only be the second monthly fall in the last seven months and may partially reflect unseasonably wet weather. Nevertheless, the data may raise concerns. We also expect a rise in the August GfK confidence measure but one that would only partially reverse July’s drop. The data overall seem unlikely to shake market convictions that another interest rate rise is likely in September.
Ahead today, Norway’s central bank this morning is widely expected to increase interest rates by 25bps to 4.00%. US releases this afternoon include the Philadelphia Fed manufacturing survey as well as the latest weekly jobless claims figures.
MARKETS
US 10-year Treasury yields moved up through 4.30% this morning, the highest level this year. The UK 10-year gilt yield closed higher for a fourth day in a row, at 4.65%. In the currency markets, the US dollar is broadly supported and remains the outperformer this week with the exception of the UK pound. GBP/USD has stayed above 1.27 while GBP/EUR has risen to 1.17, driven by expectations for higher UK interest rates.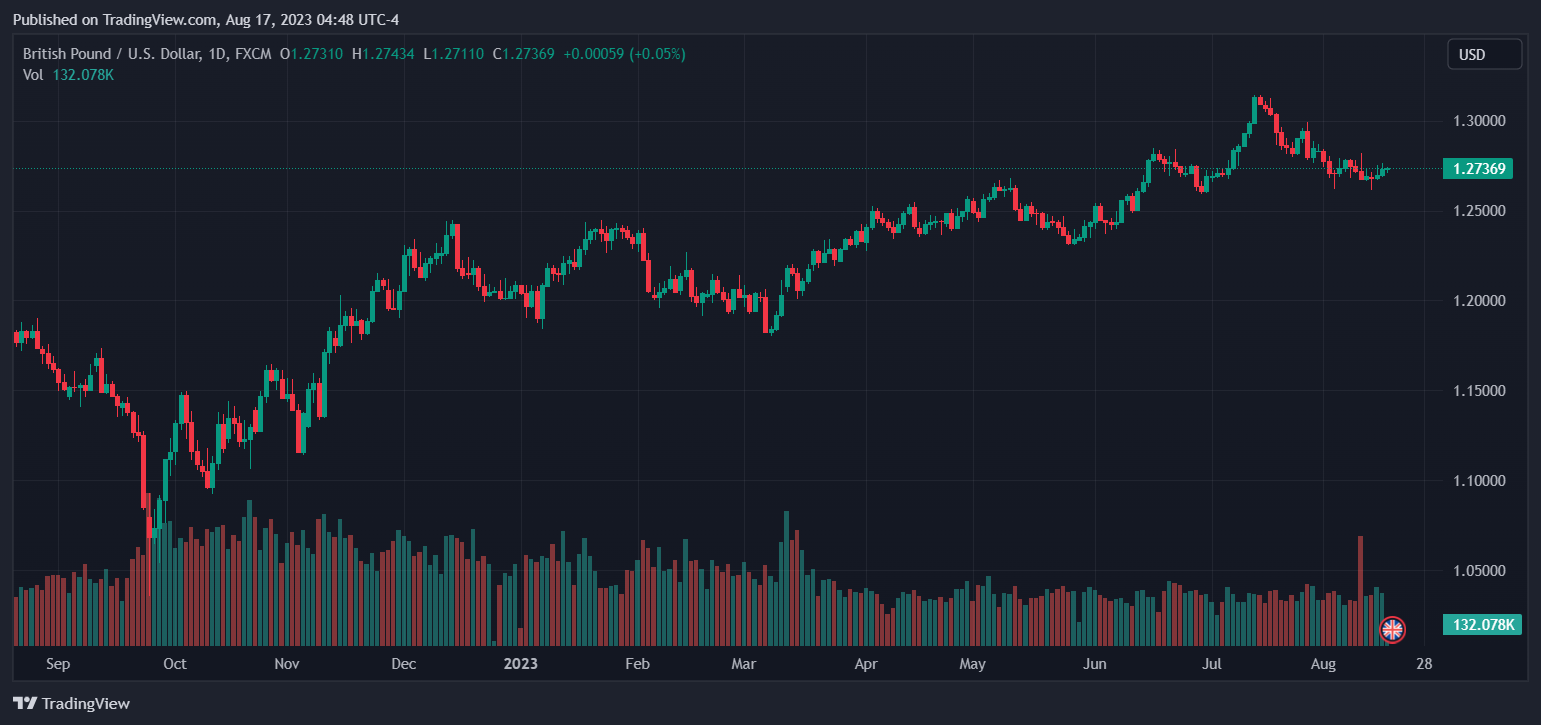


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






