






Interest rate expectations remain volatile

OVERNIGHT
Asian equity markets are mostly up this morning despite declines in European and US markets yesterday. A signal of stronger growth in China, with the unexpected rise into positive territory of the Caixin manufacturing PMI, may have provided a boost. Sentiment may also have been lifted by the vote for the Federal debt ceiling deal passing in the lower chamber of Congress. The Senate will vote today. Also in the US, two Federal Reserve policymakers voiced their support for skipping an interest rate increase at the June policy meeting.
THE DAY AHEAD
With only two weeks to go to the next European Central Bank monetary policy announcement, today’s Eurozone CPI inflation data for May is very timely. Already released outturns for the biggest economies in the region point to a larger than expected fall. As a result, we have revised down our forecast for headline inflation to 6.1% from 7.0% in April. Overall, this primarily reflects annual energy price base effects, with the ‘core’ inflation rate expected to be stickier. We expect that to have fallen only modestly to 5.5%, from 5.6% in April.
The ECB seems set to raise rates again in June but what happens after is less clear. Markets are giving a high probability to the chances of another hike in July, however, comments from ECB policymakers suggest that they are divided on how far rates need to rise. So, comments from the minutes of the last policy meeting, which will be released today, on the potential peak interest rate may be revealing.
Today’s UK money supply and bank lending numbers, together with the results of the latest Bank of England Decision Makers Panel, may provide some insight into how much further UK interest rates need to rise. Particularly interesting in the former will be any signs on the extent to which mortgages and other forms of lending are slowing. We expect mortgage approvals to have fallen on the month but expect them to still be above their levels at the start of the year. The DMP will be watched for any signs of easing wage and/or price expectations.
May PMI manufacturing for the UK and the Eurozone are second readings that are not expected to be revised. The first estimates showed manufacturing activity continuing to run well behind that in the service sector. The US ISM manufacturing measure for May is new information. It is also expected to show the sector under pressure, with another reading well below the 50-expansion level. However, an upward surprise would add to concerns that US interest rates may have further to rise.
MARKETS
Bond yields in the Eurozone, the UK and the US all fell yesterday as markets continued to weigh up the chances of further interest rate increases across all three economies. In currency markets, sterling moved higher against the US dollar and touched its highest level of the year against a faltering euro.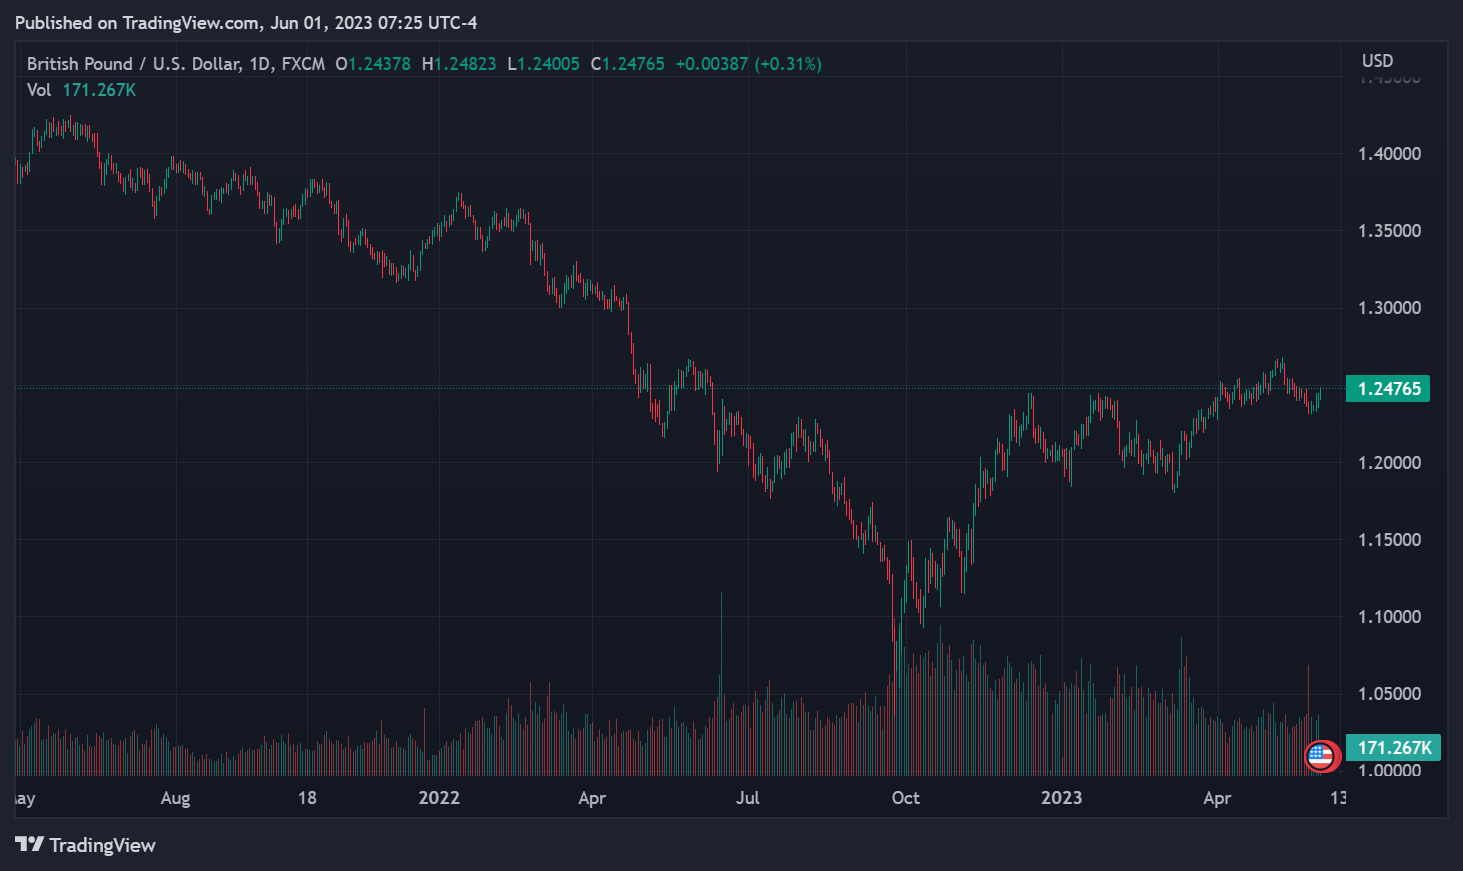


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






