






Markets prepare for a busy week of key central bank meetings

OVERNIGHT
Equities across the Asia-Pacific region are mostly trading higher, having initially opened lower – particular across Chinese stocks – in response to the softer-than-expected China CPI and PPI releases over the weekend. However, signs that investors were ‘buying the dip’ have seen most indices move back into the green. Early on Saturday, China reported that consumer prices had moved further into deflationary territory with CPI dropping to -0.5%y/y in November from -0.2% the prior month. In tandem, China producer price data fell 3.0% y/y, pointing to softer price pressures further back in the supply chain.
THE DAY AHEAD
With financial markets strong anticipating significant cuts in interest rates next year, the messaging from three of the major central banks - the Bank of England, European Central Bank and the US Federal Reserve - will be watched closely. While none of them are expected to make an immediate change to interest rates, their guidance on next year’s policy actions will command attention. Policymakers from all three central banks have made attempts to row back against recent market moves but so far with only limited effect. Markets now see about a 60% probability of an ECB rate cut by March and see two 25 basis point cuts as likely by June and around a 125bp reductions in total for 2024. Expectations for the US similar with almost two 25bp reduction priced by June and around five in all by year end.
For the UK, rate cut expectations continue to be less aggressive with a first 25bp reduction not fully priced until June but still over 75bp of Bank Rate reduction fully priced by year end. However, even that degree of easing seems at odds with the rhetoric from BoE policymakers that still suggests cuts are a long way off.
The lack of any major data releases and events today (both in the UK and elsewhere) means that there is nothing that is likely to offer markets new food for thought. However, early tomorrow morning (07:00 GMT), the ONS will release some labour market data, albeit this will be limited and not the usual full set of employment and unemployment numbers given ongoing data issues. Nevertheless, job vacancy numbers will provide indications of the strength of the labour market, and we expect those to fall again. Earnings growth is also expected to have eased with annual regular pay growth in the three months to Octobers down to 7.4% from 7.7% previously.
MARKETS
The dollar edged up further in early Asian trading, building on the overall gains made on Friday following the stronger-than-expected US labour market report. Tomorrow’s US CPI report marks the next major data release for markets, which is likely to play a part in the tone adopted by the Federal Reserve when it makes its next policy announcement on Wednesday.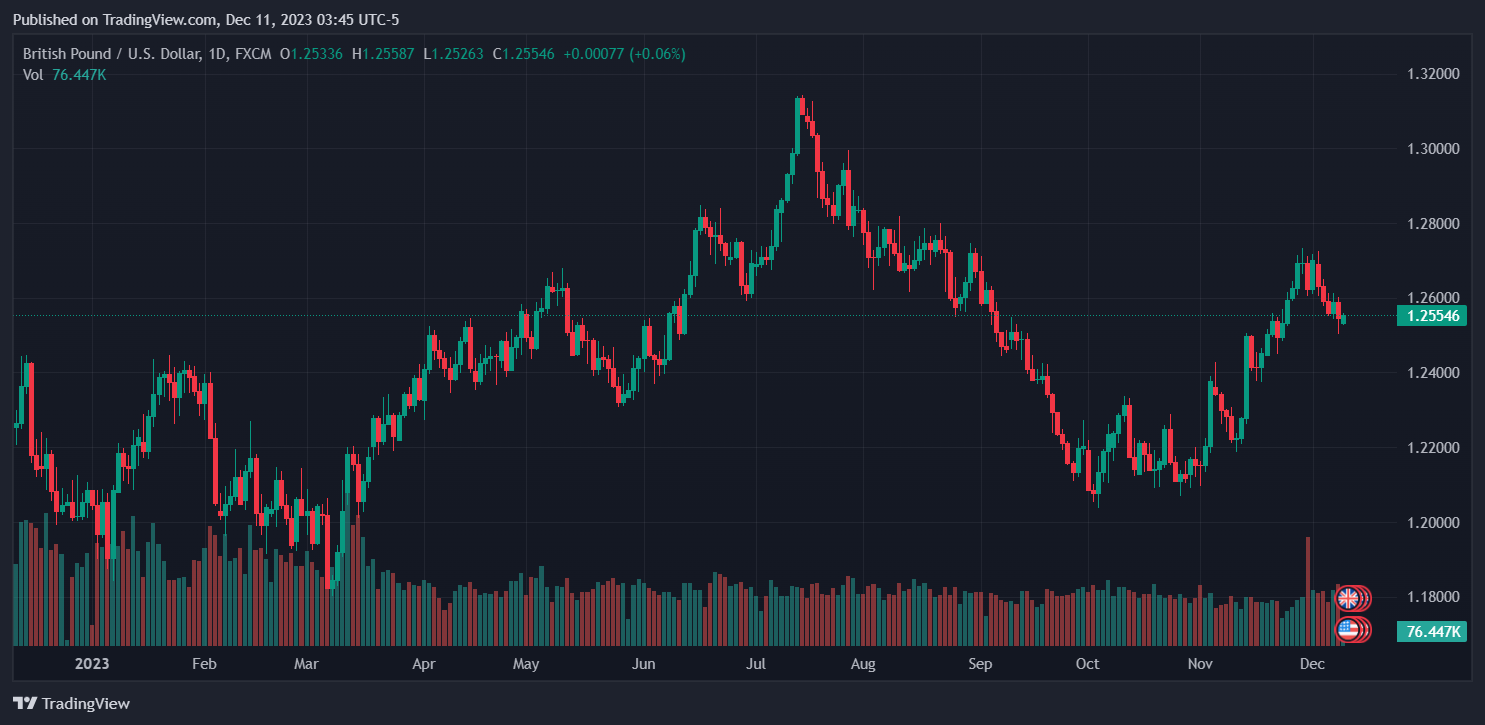


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






