






RBA surprise hike propels AUD higher

OVERNIGHT
Asian equity markets were mostly higher overnight. The Japanese Nilkkei 225 index, for instance, continued its rally, gaining nearly 1%. The big surprise overnight was the decision by the Reserve Bank of Australia (RBA) to raise interest rates by 25p to 4.1%. Policy rates were expected to be unchanged by most economists, although a significant minority anticipated another increase. The RBA indicated that inflation was still too high and that some further tightening may be required.
THE DAY AHEAD
The British Retail Consortium (BRC) overnight provided an early look at the strength of UK retail activity in May. It reported like-for-like value sales growth of 3.7%y/y in May down from 5.2% in April. As these figures are unadjusted for inflation, they are flattered by rising prices, while underlying volume sales growth is much less strong. Latest official data from the ONS suggest that volume sales in April were down 3.0% compared with a year earlier.
Also earlier this morning, the volatile German factory orders data posted a further fall of 0.4%m/m in April after a sharp 10.9% drop in March. The outcome contrasted with expectations for a partial rebound. Recent revised figures revealed the German economy contracted by 0.3%q/q in Q1, compared with the previous estimate of 0.0%. Given negative growth in Q4 of last year as well, it suggests Europe’s largest economy did fall into a technical recession after all. Looking ahead, the current expectation is that modest growth will resume in Q2. Early tomorrow sees the release of German industrial output for April.
Eurozone retail sales for April are due later this morning. They are forecast to show a small month-on-month increase of 0.2% after the 1.2% fall in March. Eurozone retail sales have remained weak, falling in Q1 for the fifth consecutive quarter. All being said, the ECB is still set to raise interest rates again next week as policymakers focus on getting inflation down. This morning’s update of the ECB’s consumers expectations survey will therefore generate some interest. The last data point showed a reversal of the downtrend in inflation expectations (see chart) which would likely have been a concern particularly for more hawkish rate-setters.
There are no US releases of note today. Early Wednesday sees the release of Chinese trade data which will be parsed for signs of the strength of domestic demand as well as the impact of global demand on export growth. Concerns that China’s recovery is petering out have gathered pace recently. Also out early tomorrow is Australian Q1 GDP, with growth forecast to have slowed to 0.3%q/q from 0.5%q/q in Q4.
MARKETS
GBP/USD fell below 1.24 yesterday before softer than expected US ISM services data weakened the dollar and pulled Treasury yields lower. The pound was slightly firmer in Asian trading session at around 1.2450 and little changed versus the euro at 1.16. The Australian dollar outperformed following the surprise RBA hike. 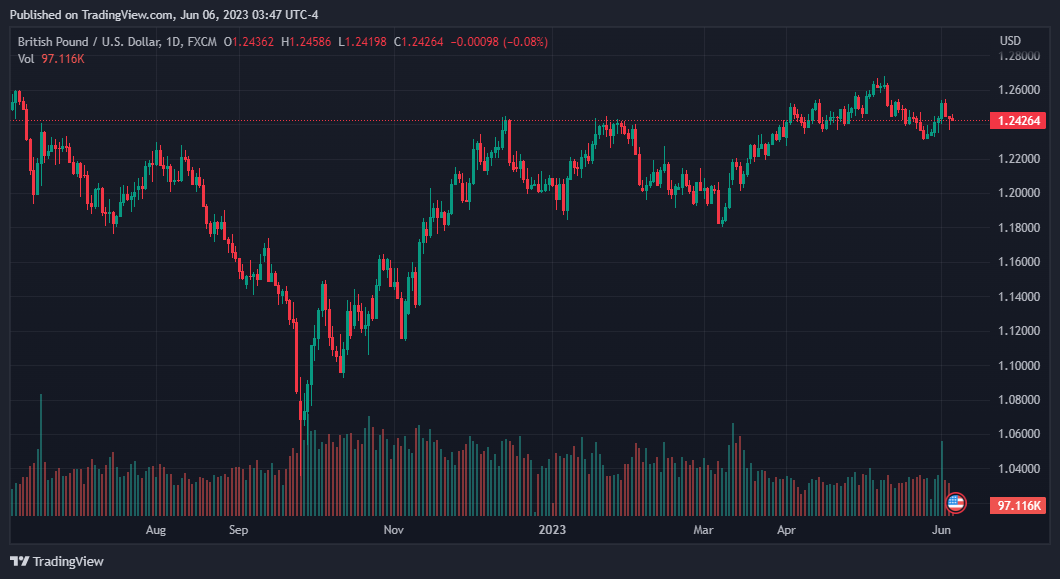


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






