






Risk appetite fades as Fed decision looms

The wait is almost over
With the crucial Fed meeting just one day away, market tensions are gradually rising as investors are essentially trying to predict the signals from tomorrow’s gathering. The expected rate move, the overall rhetoric, the number of rate cuts penciled in for 2026 by Fed members in the dot plot, the voting result, Chair Powell’s comments about the likely January actions and his replacement create a potentially explosive mix.
Meanwhile, risk assets are trying to find their footing after Monday’s mixed session. US equity indices finished in the red despite US President Trump’s announcement allowing NVIDIA to ship its advanced H200 products to approved customers in China, with the US government earning 25% of the fees. While the deal does not include the most powerful Blackwell chips, it is a positive step towards maintaining the current good trade relations between the two largest economies.
Interestingly, bitcoin remains on the back foot, being down 1% this week, and continuing to diverge from the major altcoins. Ether appears to be rejuvenated by last week’s Fusaka update, while both Cardano and Solana are also gaining this week. Following an impressive run, cryptos’ recent performance has clearly dented enthusiasm amidst a traditional risk-on period. Could Wednesday’s Fed meeting prove the missing catalyst for another advance?
Unexpectedly, bond yields appear to have caught market attention. Japanese government bond yields have been rising aggressively since the last BoJ meeting on October 30 – essentially ‘pricing in’ the much-discussed rate hike in one week’s time – with the longer end of the US yield curve also following suit despite the expected Fed rate cut. The two-year yield is almost unchanged from the October 29 Fed gathering, but the 30-year yield has climbed 22bps, reflecting increasing market angst about the inflation outlook and the likely dovishness of the Board once Powell’s replacement takes office in 2026.
FX mostly rangebound, RBA remains hawkish
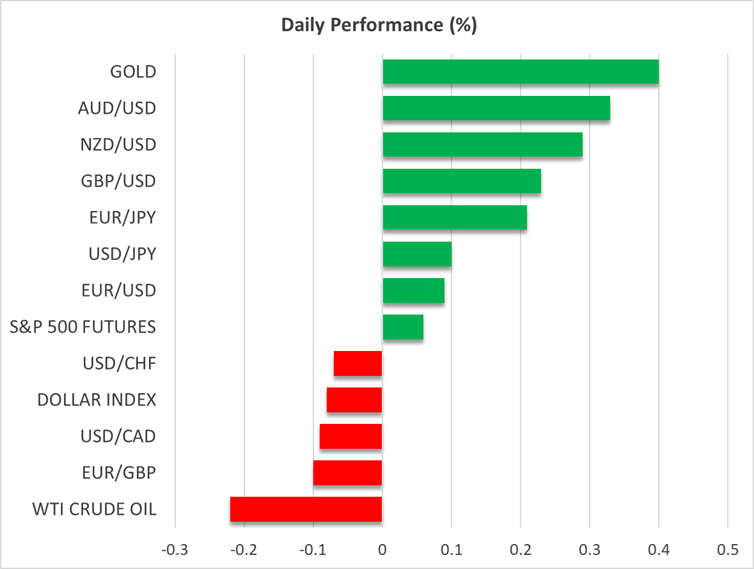
The FX space is experiencing a rather quiet period – clearly depicted in one-month implied volatilities – potentially resembling the calm before the storm. The dollar remains cornered as a dovish Fed show tomorrow could unlock another bout of weakness, even against peripheral currencies.
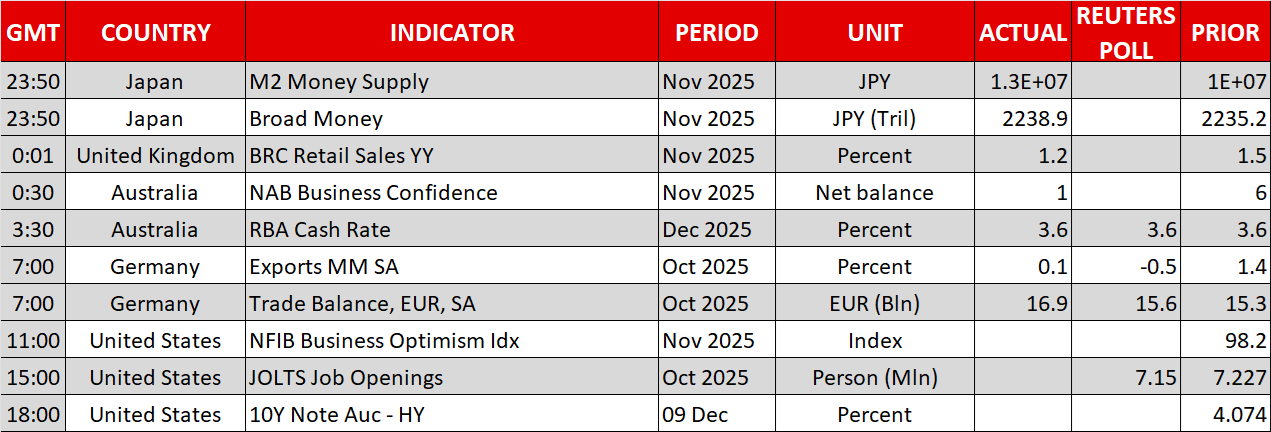
Meanwhile, as widely expected, the RBA kept rates unchanged and turned more hawkish. With another rate cut off the table for the foreseeable future, Governor Bullock opened the door to a Q1 rate hike if inflationary pressures do not abate and prove persistent. Aussie/dollar is in the green today, erasing yesterday’s weak session, but failing to rally aggressively towards the 0.6681 zone. Positive inflation data from China, to be published overnight, could open the door to another episode of aussie strength.
Crammed US data calendar
Following a rather quiet Monday, today’s calendar is busier, with the weekly ADP employment report garnering some market attention. Notably, two JOLTS job openings reports for September and October will be published, making these releases useful but clearly out-of-date. More importantly, a 10-year note auction will take place later today, and it would be interesting to see if the recent yield rise will positively influence demand or whether investors feel that current yield levels are still underpricing the inflation risk.
Meanwhile, the mixed risk appetite is not benefiting gold, which has dropped below the $4,200 level once again. The decline in oil prices is more telling though, as the move above the 50-day simple moving average proved very short-lived following reports that Iraq restored production at one of the largest oil fields in the world, operated by Russia’s Lukoil, despite the absence of significant progress in the US-brokered Ukraine-Russia peace process.


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






