




Spotlight on US CPI inflation report

OVERNIGHT
Equity markets in the Asia-Pacific region are mostly higher but there appears to be some caution ahead of the key US inflation data later today. There were some mixed Fed comments on prospects for US monetary policy, although most policymakers concurred with the March ‘dot plot’ forecast signalling modest further tightening. Today’s inflation numbers will play an important role in the debate.
THE DAY AHEAD
In the absence of notable UK or Eurozone data this morning, the focus will be on US CPI figures and the minutes of last month’s Fed policy meeting during which policy rates were raised by 25bp amid concerns about regional banking stresses. BoE Governor Bailey is among several central bankers scheduled to speak later today. The Bank of Canada is expected to leave interest rates at 4.5%. Early tomorrow morning sees the release of the UK RICS housing survey and official monthly GDP data for February. Chinese trade data will also be released early Thursday.
Already released Eurozone March CPI posted a big fall in annual headline inflation as last year’s sharp rise in energy prices contrasted with this year’s falling prices. We expect a similar outcome in today’s US CPI data (and in the UK next week) and forecast US annual CPI inflation to have dropped to 5.3% from 6.0% in February. The consensus is for a larger fall to 5.1%. However, like the Eurozone, ‘core’ inflation may prove to have been stickier. We look for annual inflation in prices other than food and energy to rise modestly to 5.6% from 5.5%. This presents a dilemma for the Federal Reserve that they will need to weigh up against concerns about faltering growth and tightening credit conditions when deciding on their next move in interest rates.
Credit conditions and their potential impact on growth is a topic that is also likely to come up in the minutes of the US Federal Reserve’s March monetary policy meeting. At that time Chair Powell took a distinctly less hawkish line than he had in speeches just a few weeks before. In particular, he implied that potentially tighter credit conditions negated the need for some interest rate rises that Fed policymakers previously thought would be necessary. The minutes are likely to provide more detail on their new concerns.
Early tomorrow’s UK GDP reading is forecast to have posted a second successive monthly rise in February and we look for a modest gain of 0.1%m/m. A strong February reading for the services PMI potentially points to a larger increase. However, that index does not cover the public sector which has been impact by strikes particularly in schools and the NHS. As a result of those, we expect overall services output to have dipped slightly. Nevertheless, construction output and industrial production are expected to have rebounded by enough to ensure a small overall rise in activity.
MARKETS
GBPUSD remained above 1.24 overnight, while GBPEUR traded just below 1.14. US 10-year Treasury yields stayed above 3.4% and Brent crude oil rose towards $86 a barrel.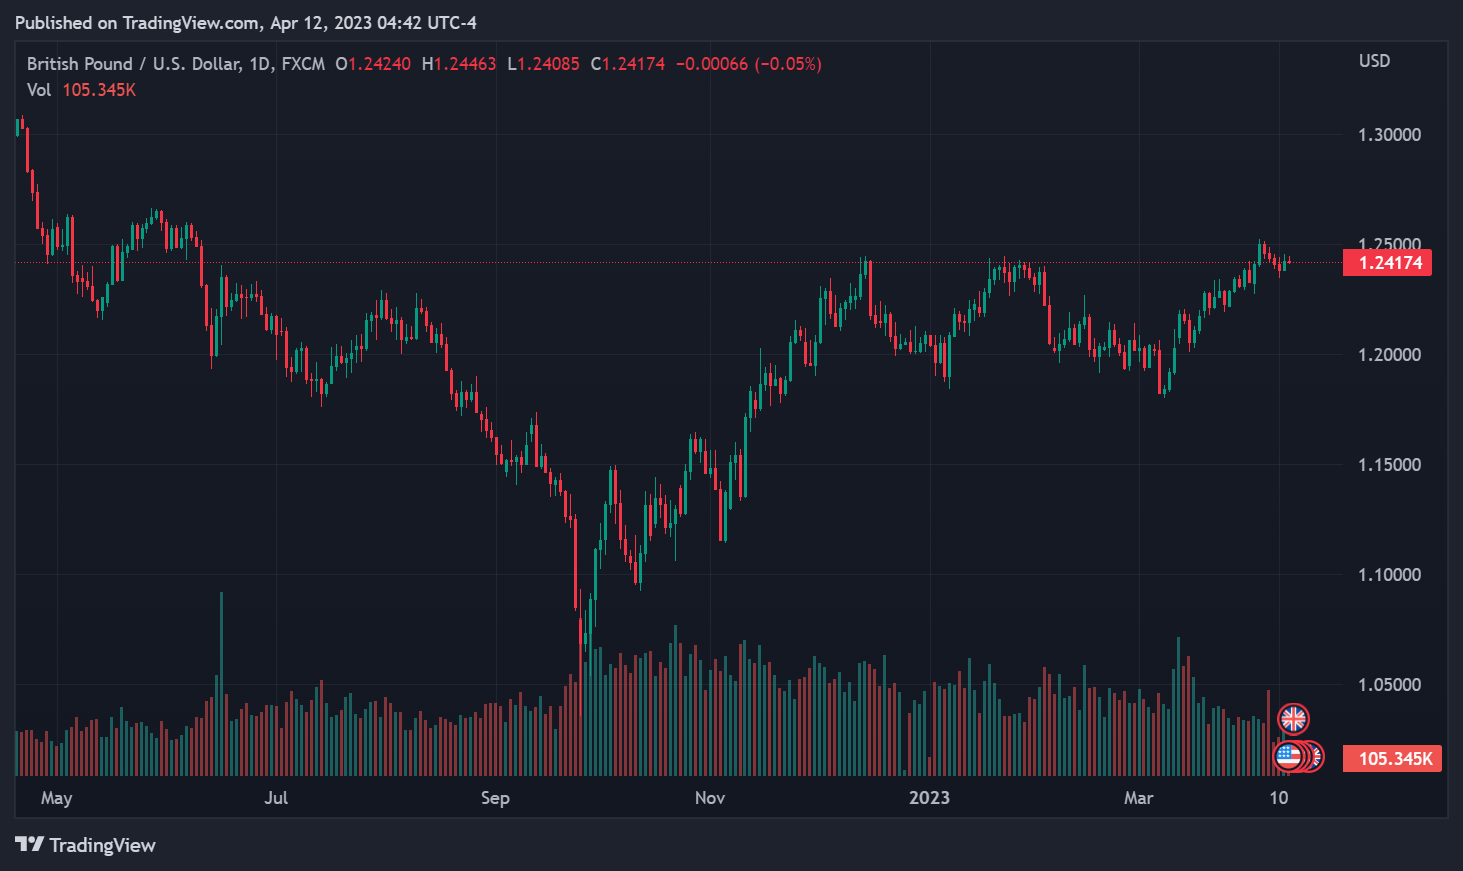
US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026
The dollar saves the day
Tech Stocks Lead US Selloff Ahead of Payrolls
GBPUSD bull run: Can the pair smash through 1.3565?
Democrats' Midterm Victory Sends Dollar and Oil Lower
US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback
US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026