






Sterling markets await UK CPI

OVERNIGHT
Asian equity markets traded mostly lower as the recent positive momentum in global stocks appeared to be fading for now. US and European equities also closed lower yesterday. China’s central bank lowered its 1- and 5-year prime loan rates by 10bp as expected, although there were hopes for a larger cut to support the country’s property sector. Also, notable overnight was the release of the minutes of the Reserve Bank of Australia’s decision to increase interest rates at its last policy meeting earlier this month. The minutes were more dovish than expected, with the final policy decision between hike or pause described as “finely balanced”.
THE DAY AHEAD
The domestic focus over the next twenty-four hours is the release of UK CPI inflation early tomorrow at 07:00BST. The report comes a day before the Bank of England policy announcement at midday on Thursday. We forecast headline inflation to fall slightly from 8.7% to 8.5% in May. The market consensus forecast is marginally lower at 8.4%. Regardless, the outturn will confirm the relative ‘stickiness’ of UK inflation compared with other jurisdictions such as the US (4.0%) and the Eurozone (6.1%). Particularly concerning for policymakers is that UK core inflation, which excludes energy and food and consists mostly of services prices, is still on an uptrend. Last week’s upside surprise in wage growth will not have allayed these concerns. The BoE, as a result, is widely expected to increase interest rates again this week by 0.25% to 4.75%, and financial markets predict a series of further hikes later this year.
There are no major UK or Eurozone data releases today. Several ECB speakers are scheduled to present, following last week’s decision to raise interest rates again by 25bp. ECB President Lagarde gave a strong signal that another hike is likely next month, while there appears to be somewhat more of a debate whether there will be a further rate rise in September.
US housing data today in the form of housing starts and building permits will draw attention ahead of Fed Chair Powell’s semi-annual testimony to Congress next Wednesday. His comments will provide further colour on the Fed’s rate hike ‘skip’ last week and give him another opportunity to discuss prospects for Fed policy, including what it needs to see to affirm or negate the policymakers’ ‘dot plot’ showing projections of 50bps of further hikes in H2.
MARKETS
The turnaround in market risk sentiment has provided some support for the US dollar. GBP/USD fell below 1.28 yesterday and was little changed overnight. The euro’s fall against the greenback was more limited. The Australia dollar underperformed after unexpectedly dovish RBA minutes. UK 10-year gilt yields closed up 8bp to 4.49%, the highest since last October. US 10-year Treasury yields traded higher overnight, while the Brent crude oil price fell.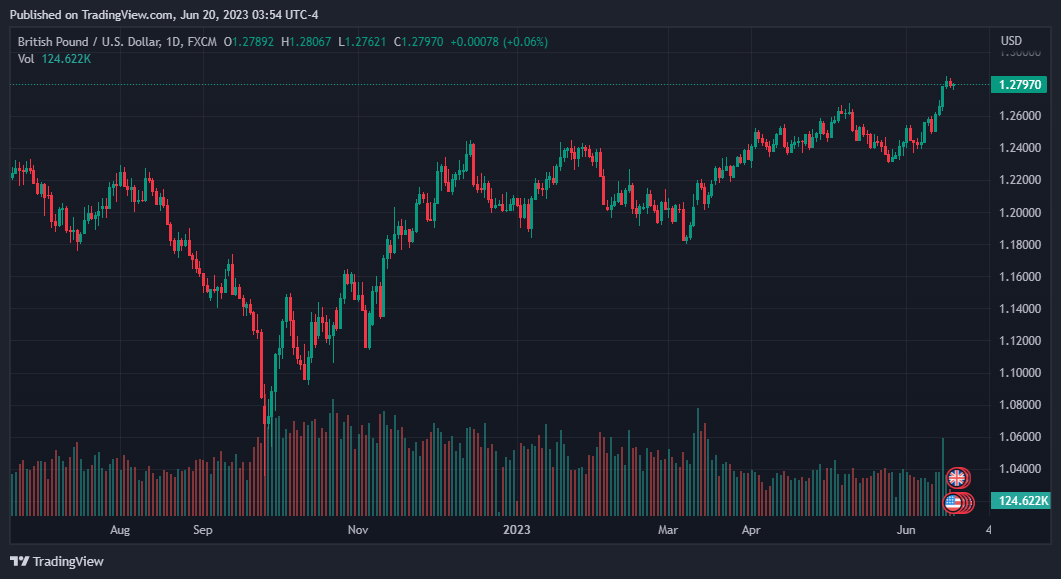


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






