






Turkey elections hang in the balance

OVERNIGHT
Equities across the Asia Pacific edged higher, as well US and European futures as talks aimed at averting a US debt default showed signs of progress. Meanwhile, the election in Turkey looked set to go to a second-round run-off between President Erdogan and his main opponent Kilicdaroglu after neither appeared likely to reach the 50% threshold to win outright.
THE DAY AHEAD
Following a busy couple of weeks for key central bank meetings, the coming week is set to be less eventful. Nevertheless, a number of data releases should provide some input into future monetary policy decisions. In the Eurozone, we expect industrial production to have fallen sharply in March after having posted two consecutive months of increase earlier in the quarter. Already released data for France, Germany, Italy and Ireland point to that outcome particularly with the latter seeing a drop of 26.4%m/m. We forecast a drop of 3.0%, which would still leave overall Eurozone industrial output up in Q1, courtesy of the strong start made to the quarter.
In the US, the Empire State manufacturing survey for May is forecast to show the headline balance moving back into contractionary territory. Such an outturn would suggest that April’s positive reading was a blip. There are a number of Fed speakers in the shape of Bostic, Goolsbee, Kashkari and Cook. Markets will be watching for signs that these members support the prospect of the Fed pausing hiking interest rates.
Domestically, there are no UK data releases due, though some focus should be on comments from the Bank of England Chief Economist Huw Pill. Mr Pill is due to speak at an online event to discuss the detail of the May Monetary Policy Report. Speaking after last week’s policy announcement – at which the MPC raised interest rates by a further 25bp to 4.50% – Mr Pill noted that while inflation was coming down, the persistence of elevated outturns would leave the door open to further tightening.
Early tomorrow morning, the latest UK labour market will be closely watched, and it seems unlikely to provide reassuring reading for the BoE. Employment growth is expected to have been robust in the three months to March (we look for a 330k rise), while the unemployment rate is expected to have slipped to 3.7% from 3.8%. Moreover, while the official measure of unfilled job vacancies may provide a tentative sign of the market rolling over with a further modest fall the overall level at above 1 million is still very high. So, all in all, the picture still seems to be one of a very tight market. Wage growth is projected to have accelerated and we look for the annual headline rate to have accelerated to 6% from 5.9%, while regular pay growth (excluding bonuses) is set to rise to 6.8% from 6.6%. Ahead of that, Chinese retail sales and industrial production for April will provide the latest news on the strength of the economic rebound after the easing of Covid restrictions.
MARKETS
US bond yields are little changed from their Friday close, hovering just below the 4% mark. The US dollar is modestly weaker, reversing some of its Friday afternoon gains. GBP/USD has edged up but remains below 1.25.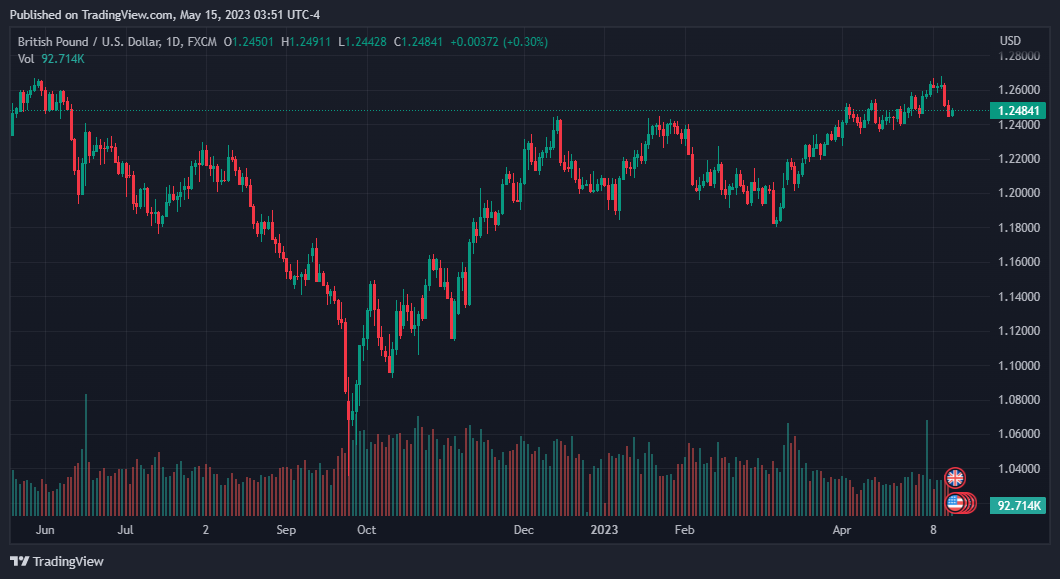


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






