






UK consumer confidence at 15-month high

OVERNIGHT
Equity markets in the Asia-Pacific region increased, encouraged by hopes of a near-term resolution in US debt ceiling negotiations to avoid a debt default. Japan’s Nikkei index rose to a new 33-year high. The exception to the positive risk tone was China where emerging signs of a fading post-Covid bounce in economic activity weighed on asset prices. US Treasury yields were steady overnight but have risen in recent sessions as investors ponder whether the Fed might increase interest rates next month, although a ‘pause’ is still considered the more likely scenario.
THE DAY AHEAD
UK consumer confidence, released overnight, increased to the highest level since early 2022. The overall index climbed to -27 in May from -30 in April. It fell sharply last year due to the energy crisis but has steadily recovered since last September’s low point, helped by lower energy costs and stronger labour demand. The report revealed a further improvement in expected personal finances in the next twelve months. Yesterday, Governor Bailey reiterated that inflation is on the way down, led by energy, but that there are uncertainties and upside risks related to potential second-round effects from domestic wages and prices. While policy interest rates are expected to be at or near a peak, the BoE has left the door to further hikes.
The rest of the day is bereft of major data releases. Canadian retail sales are expected to have fallen for a second month in a row. BoE MPC member Haskel is scheduled to speak this morning, but the topic is on productivity measurement issues rather than monetary policy.In the US, Fed Chair Powell and NY Fed President Williams take part in a monetary policy conference, and their remarks will be closely attended to, particularly with respect to the likelihood or not of a Fed policy ‘pause’ next month.
In the Eurozone, ECB speakers include President Lagarde and Executive Board member Schnabel. The ECB has indicated it will continue to increase interest rates at the next policy update in June and possibly beyond that.
Looking to next week, the UK focus includes April CPI inflation data and the flash PMI survey for May. The flash PMI will also be released for other countries including the Eurozone with attention also on the German IFO business survey. The US data focus includes the second estimate of Q1 GDP, FOMC minutes and personal consumption figures for April including the Fed’s preferred PCE inflation measure.
MARKETS
The US dollar continued to post gains as investors assess whether the Fed will press pause on its rate hikes at the next policy update in June. Markets now attach about 30% probability of a rate rise versus approximately 10% a week ago. GBP/USD has fallen towards 1.24 on broader dollar strength.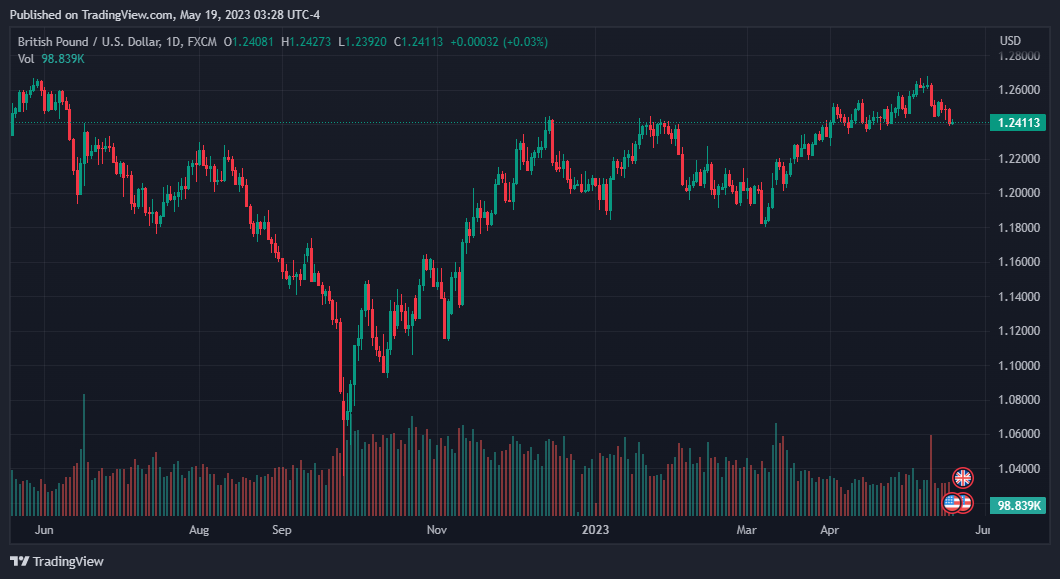


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






