




UK February GDP hit by strike activity

OVERNIGHT
Asian equity markets are mostly lower this morning. The minutes of the Federal Reserve’s March monetary policy discussions reported that Fed forecasters now see a mild recession as likely later this year. It also said that some policymakers argued for a pause in interest rate hikes before agreeing to the 25 basis point increase that was enacted. China posted a larger than expected March trade surplus reflecting a sharp pickup in exports. In Australia, March employment rose by more than expected prompting speculation that the central rate had ‘paused’ its interest rate hike cycle too early.
THE DAY AHEAD
Just released data for February UK GDP showed a weaker than expected outcome of no growth on the month, but January was revised up to a 0.4% gain from 0.3% previously. The February figure reflects a combination of a large 2.4% rise in construction output offset by a 0.2% fall in industrial production and a 0.1% decline in services output. That latter move seems primarily due to the impact of strikes particularly in schools and the NHS. After today’s data, GDP seems on course to record a modest rise in Q1 rather than the fall previously predicted by the Bank of England.
In the Eurozone, we expect industrial production to have notched up a second consecutive monthly rise, this time of 1.6%. Already released data for France, Germany and Spain point to that and the Italian data, which is due out just before the Eurozone release, is also expected to post a rise. The outcome would suggest that Q1 industrial activity has rebounded following a drop in Q4. It also points to the possibility that Eurozone GDP be up on the quarter, although it should be noted that some other indicators, for instance retail sales, point to a less positive outturn.
Following on from yesterday’s March US CPI data, which showed a fall in annual headline inflation but a rise in core inflation, today’s producer price data will provide some insight into pipeline pressures. Producer price inflation has dropped sharply of late reflecting the fall in energy prices and a more general easing in bottlenecks. The March data is likely to show a further fall in annual inflation but there are now some tentative signs of disinflationary pressures levelling off.
The Bank of England’s Chief Economist Pill is scheduled to speak about UK economic conditions today. His most recent comments suggested that UK interest rates could still move higher. So it will be interesting to see whether he has anything more to say on this ahead of next week’s busy data calendar which includes the latest UK inflation update.
MARKETS
US Treasury yields fell yesterday on growing concerns about possible recession, while in contrast UK gilt yields rose modestly. In currency markets, the US dollar came under further downward pressure as it slipped further against both the euro and sterling.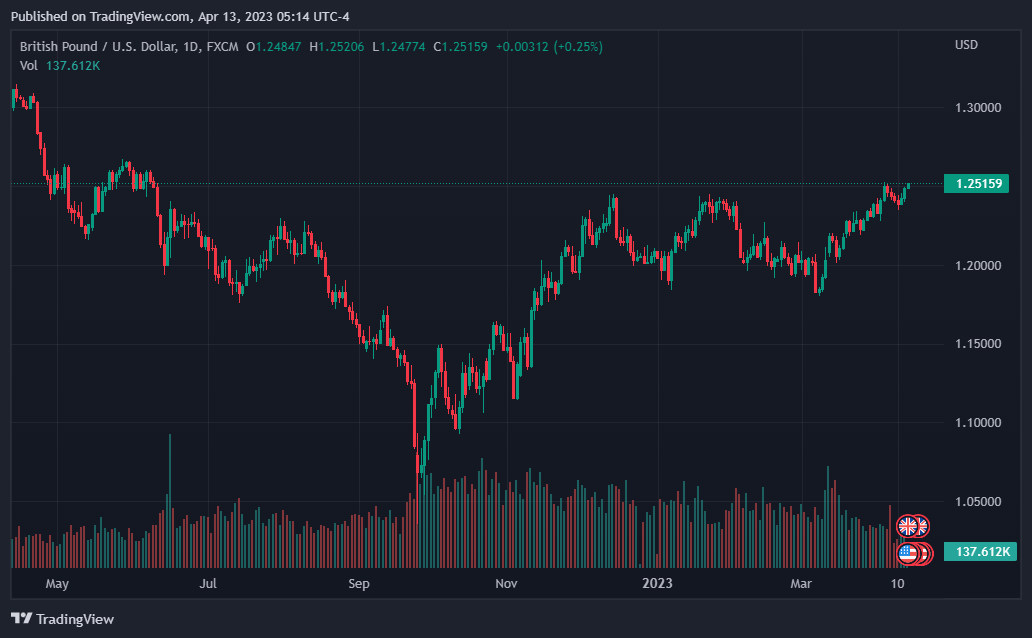
EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets
Stocks sink amid AI wipeout, dollar shines ahead of NFP
US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026
Week Ahead – Inflation and geopolitics in focus as US political landscape shifts
The dollar saves the day
Tech Stocks Lead US Selloff Ahead of Payrolls
Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00