






UK inflation down but core rate sticky

OVERNIGHT
Most Asia-Pacific equity markets are down this morning with many seeing declines of 1% or more. That follows falls in US and European markets yesterday. The Chinese central bank injected more liquidity into the economy in an attempt to boost confidence. In New Zealand, the central bank left interest rates unchanged, at 5.50%, at today’s policy update but warned about upside inflation risk and noted that rates may need to stay higher for longer.
THE DAY AHEAD
Just released UK price data showed that annual CPI inflation fell to 6.8% in July from 7.9%, which means headline inflation was at its lowest since March 2022. It was driven by the favourable comparison between sharply rising energy prices last year and the fall in early 2023. In contrast, however, the ‘core’ rate of inflation was unchanged from June at 6.9%. Coming after yesterday’s news of a larger than expected acceleration in wage inflation, the data may reinforce expectations that the Bank of England will raise rates further in September. Indeed, markets now see a risk that rates will be hiked by 50 basis point rather than just 25bp as was the case this month.
Today’s Q2 Eurozone GDP release is a second reading that is not generally expected to be revised from the original estimate of 0.3% growth. However, new data for June Eurozone industrial production will be released at the same time and a significant surprise compared to expectations of a 0.0% monthly change could prompt a revision to GDP. Even if that measure is not revised from its original faster-than-expected outturn for Q2, more timely indicators point to the likelihood of slower and possibly negative growth in Q3.
Yesterday’s stronger than expected US retail sales data for July suggested that consumer spending continued to support economic growth in early Q3. Today sees more readings for July with both industrial production and housings starts also expected to grow. Continued stronger than expected economic growth need not necessarily stand in the way of the Federal Reserve pausing its interest rate hikes in September as markets now expect. However, the Fed is unlikely to seriously consider cutting rates until there are clearer signs that economic activity is faltering.
The minutes of the Fed’s July policy meeting will be watched for confirmation that the US central bank is likely to leave interest rates unchanged at its upcoming policy meeting. As markets are only giving about a 10% probability to a September hike, they will be hoping for some clarity on what Fed policymakers will be looking for when making their decision.
MARKETS
UK gilt yields rose yesterday after the stronger than expected wage report that highlighted upside interest rate risks. Bond yields were also up in the Eurozone but the US saw choppy trading with yields initially rising and then falling back. Sterling has initially blipped up this morning against both the euro and the US dollar following the news of unchanged core inflation.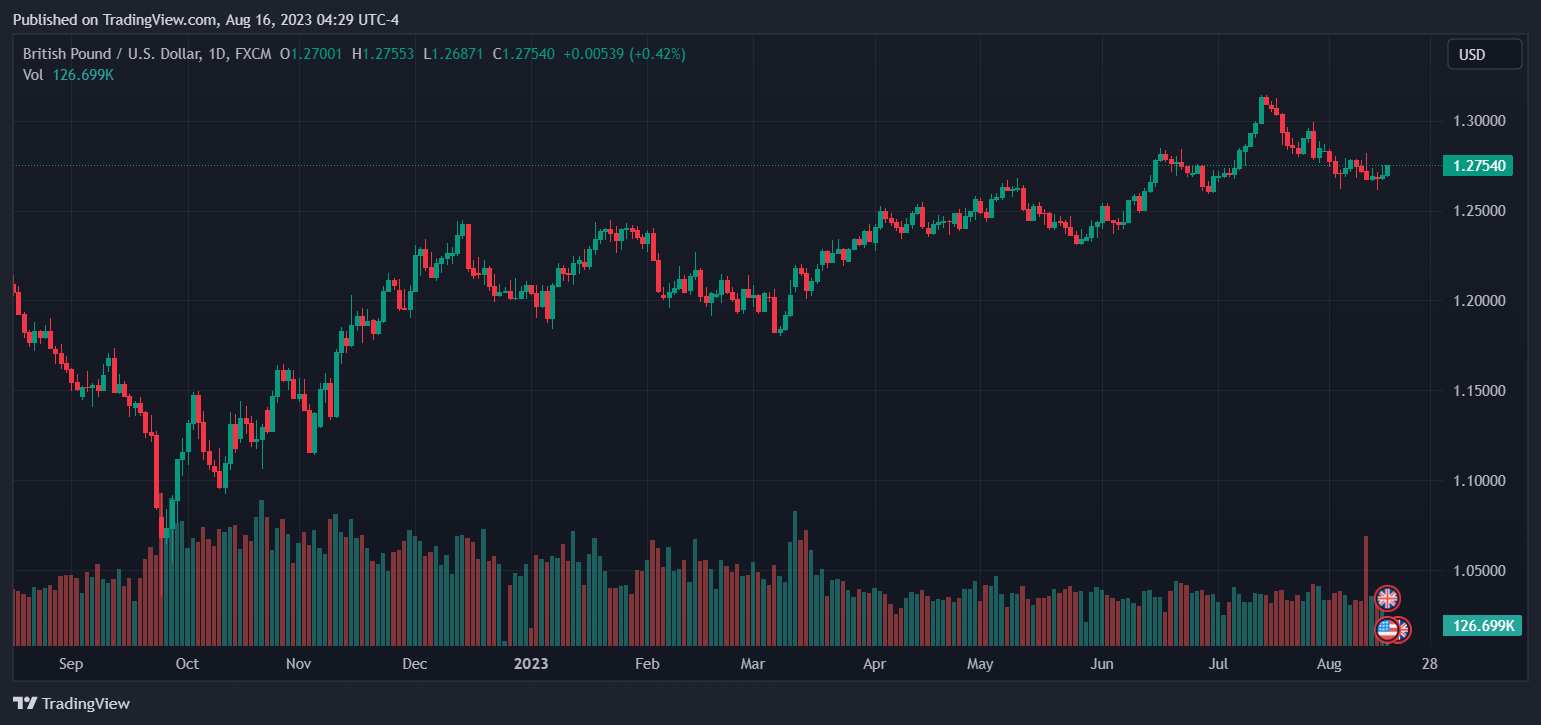


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






