






UK retail sales increased at the start of Q2

OVERNIGHT
Asian equity markets mostly firmed, following the AI tech-inspired rally in the US. Meanwhile, there were reports that an agreement on the US debt ceiling issue was getting closer, with details suggesting an increase in the debt limit and a cap on spending for the next two years. Final details are still to be worked out. In Japan, Tokyo CPI inflation fell by more than expected to 3.2% in May from 3.5% in April for both the headline and core (excluding fresh food) measures. That increases the likelihood the Bank of Japan will maintain its policy stimulus measures.
THE DAY AHEAD
Official UK retail sales figures, released earlier this morning, showed a positive start to Q2. The volume of sales including fuel increased by 0.5%m/m in April after a 1.2% drop in March which was weighed by the unusually wet weather. Food and non-food sales both rose. The outcome was exactly in line with our forecast and slightly above consensus expectations. It continues to show the impact of the squeeze on household real incomes from last year’s energy price shock, as well as a possible shift in spending towards services. The impact of past interest rate rises will also continue to feed through. However, lower energy prices than previously anticipated, as well as continued employment growth, will provide support to real incomes this year.
There are no other UK releases in today’s calendar. Next week’s releases include our Business Barometer survey and the Bank of England’s credit and mortgage approvals data. The BRC’s shop price index may also attract attention after this week’s positive inflation surprise in the official figures.
There are no major Eurozone data out today. The ECB’s Vujcic and Chief Economist Lane will take part in a panel discussion this morning on returning inflation to target at the Dubrovnik Economic Conference. Next week’s focus will be the preliminary flash estimate of Eurozone CPI for May.
In the US, the personal spending figures are expected to show growth of 0.4%m/m, an indication that consumer outlays are holding up, helped by further gains in personal incomes. We also expect the Fed’s preferred inflation gauge, the PCE deflator, to rise to 4.4% in April from 4.2%. It is likely, however, to drop back next month (May) due to lower energy prices. The April inflation rise is therefore likely to be temporary. The Fed still seems more likely to ‘pause’ its interest rate hikes in June, but positive data surprises and hawkish rhetoric from rate setters could change expectations.
MARKETS
The US dollar softened overnight, leading to gains for GBP/USD off its lows near 1.23 yesterday. Gilt yields closed higher on speculation of further Bank of England interest rate rises ahead after recent upside inflation surprises. MPC member Haskel yesterday indicated that he would ‘lean against the risks of inflation momentum’. 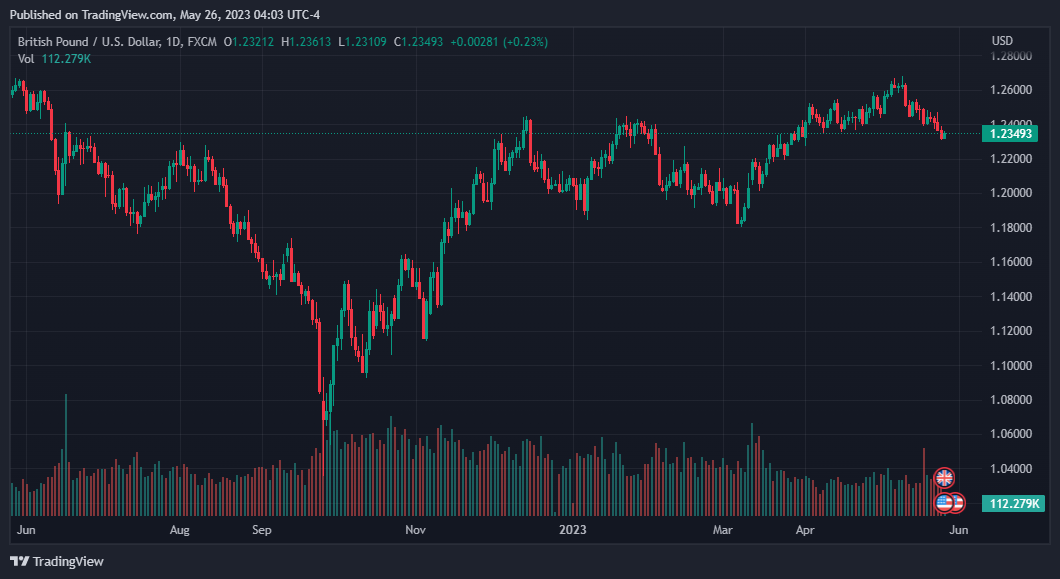


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






