






Wet weather dampens UK retail spending

OVERNIGHT
Asia-Pacific equity markets are mostly down this morning despite a rise in US indices yesterday. China posted a bigger than expected July trade surplus primarily due to a big fall in imports - a possible signal of weak domestic demand. The BRC ‘unofficial’ estimate of UK retail sales printed an annual rise of 1.8% in July down from 4.2% in June amid reports of wet weather impacting upon activity.
THE DAY AHEAD
With the major central bank policy updates now out of the way, including the one from the Bank of England last week, the economics calendar this week has more of a sparse summer feel to it. That can be seen in the low number of scheduled speeches by policymakers from the BoE, European Central Bank and US Federal Reserve. Often following policy announcement there are a spate of speeches but not this time. Yesterday’s talk by BoE Chief Economist Pill is the only scheduled appearance by BoE policymakers this week and the calendars at the other central banks are also light.
Nevertheless, as the message from all three central banks over the past couple of weeks has been - that the interest rate outlook for the autumn is uncertain and crucially data dependent - markets cannot afford to sleep. This is because the high level of volatility in markets ahead of and following last week’s US labour market report may be repeated around other crucial data releases over the next few weeks making for a nervy summer. The next such release is Thursday’s US inflation report, while Friday’s UK GDP update will also likely receive a lot of attention. However, in the meantime, the next couple of days look less interesting.
In the US today, the July update for the NFIB index will provide an indication of how the small business sector is faring. In June, the headline index rose to its highest level this year, while already released readings for July on job creation and wages showed little change from June. Also in the US, already-released data for trade in goods points to a sizeable fall in the June international trade deficit compared to May.
One central policymaker who is scheduled to speak today is Philadelphia Fed President Harker. He is a voter on US monetary policy this year and has supported previous interest rate increases, so his comments may be an important early indicator of the likelihood of another rate hike in September. Early Wednesday, China CPI data for July is expected to show that annual inflation fell below zero for the first time since 2009. That may further boost expectations that more measures will soon be announced to boost economic growth.
MARKETS
Bond yields in the UK, US and the Eurozone all rose yesterday. However, the US Treasury market has subsequently rallied sharply overnight. The fluctuations reflect uncertainty about the interest rate outlook for the autumn as markets look for guidance from upcoming data. In currency markets, sterling was up yesterday against both the euro and the US dollar.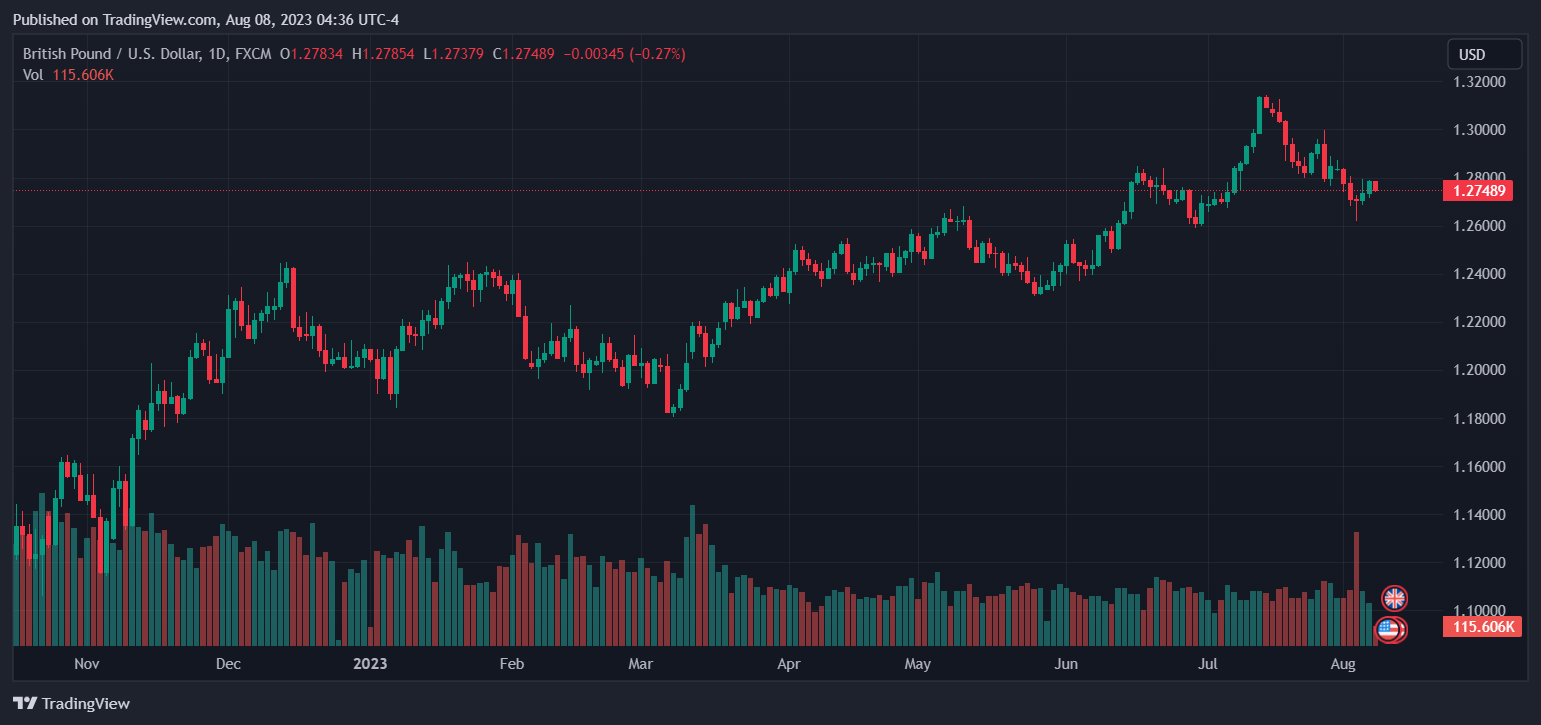


EBC Markets Briefing | "Blue Wave" poised to sweep across stock markets

Stocks sink amid AI wipeout, dollar shines ahead of NFP

US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

Week Ahead – Inflation and geopolitics in focus as US political landscape shifts

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

Technical Analysis – USDJPY stays rangebound, pinned at support near 158.00






