






Dollar extends election-related slide, stocks rebound

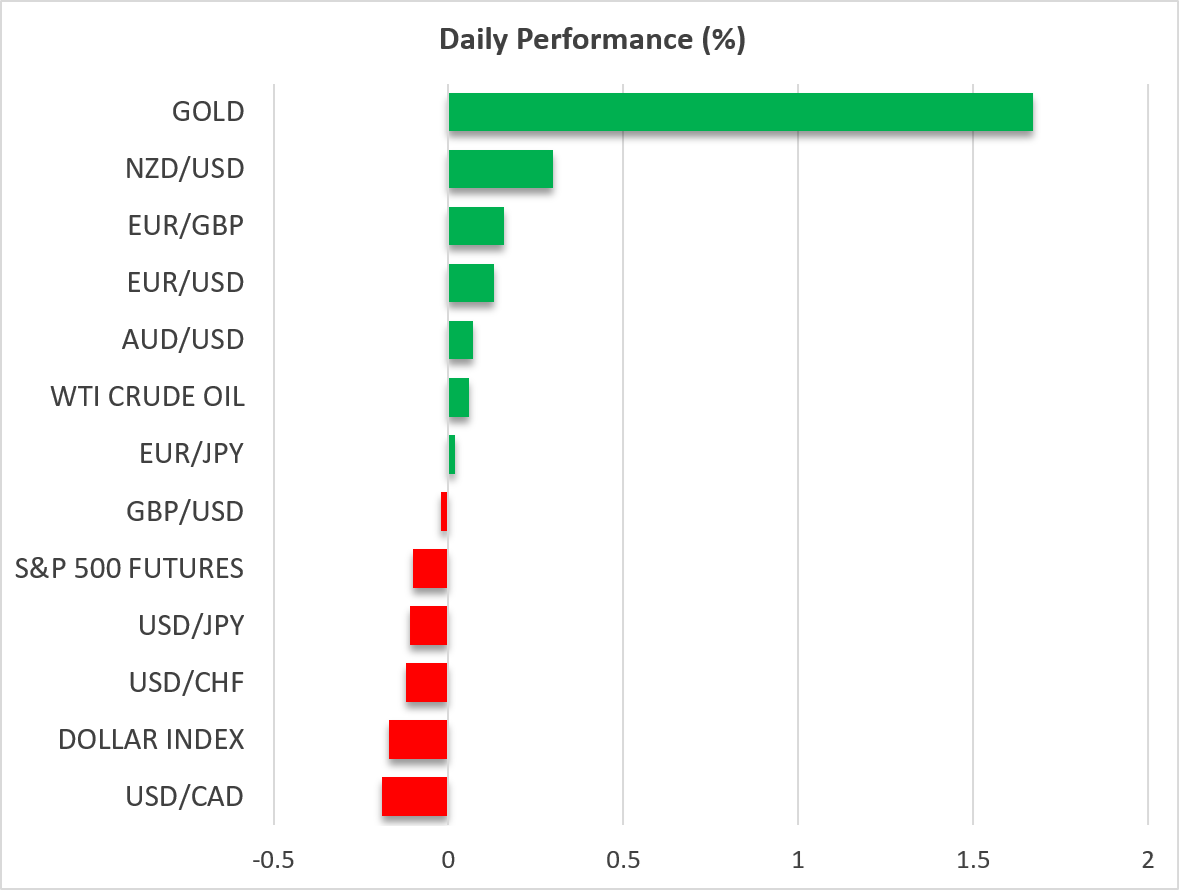
Dollar still feels the heat of the Democratic sweep
The US dollar continued sliding against all its major peers yesterday and today during the European morning, still feeling the heat of the outcome of the US midterm elections.
Democrats have secured both the House and the Senate, which has given them increased power to block US President Trump’s policies and strategies. Massive fiscal spending and tax reductions are now less likely, while tariff-related threats are unlikely to turn into law. What’s more, Trump may face strong opposition when it comes to increasing attacks on Iran and the Middle East.
Expectations of slower growth amid less fiscal stimulus and reduced fears about inflation spiraling out of control prompted investors to reduce their Fed rate-hike bets and thus, the dollar and Treasury yields retreated. Although there is still a strong 80% chance of a 25bps rate hike at the December Fed gathering, there is only one more same-sized increase factored in for next year.
US jobs data could revive dollar support
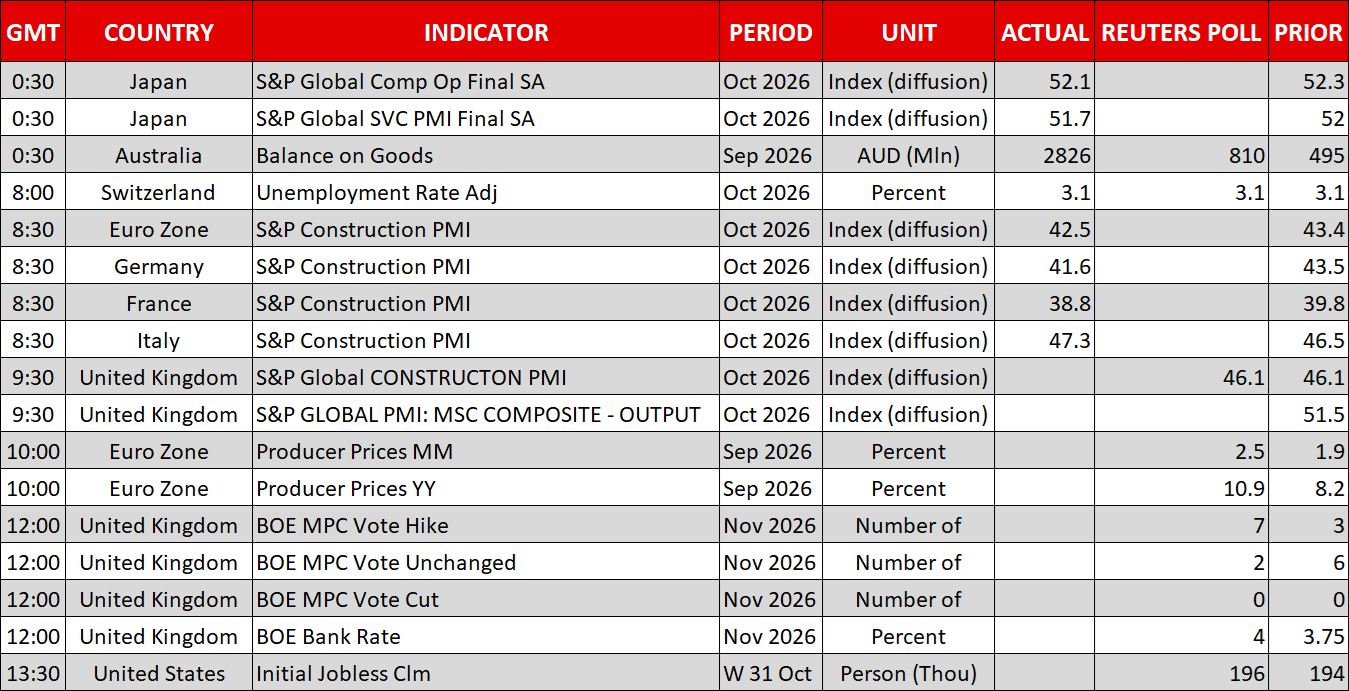
Attention now turns to tomorrow’s US jobs data for October. Nonfarm payrolls disappointed significantly in September, with employment slowing to 29k from 133k in August, and missing the forecast of 90k. However, according to the flash S&P Global composite PMI, hiring in the manufacturing and services sectors in October was the second-fastest since 2022, which combined with the lower prints of initial jobless claims during the month, tilts the risks of tomorrow’s release to the upside. Yesterday, the ADP report revealed that the private sector gained 86k jobs, beating the forecast of 67k and corroborating the idea of a potential upside surprise tomorrow.
A stronger-than-expected jobs report may offer a shot in the dollar’s arm as investors price further tightening for 2027 back into the market.
BoJ signals further tightening, EZ inflation tests ECB caution
In Japan, the minutes of the September Bank of Japan decision – not the latest one in October – revealed that policymakers, after pressing the rate hike button, remained willing to continue raising rates, with some of them suggesting a faster pace of increase. Yet, a December rate hike is not fully priced in, with markets assigning only a 60% chance to it, according to Japan’s overnight index swaps (OIS), while two more quarter point increases are anticipated by the end of next year.
A December rate increase is not fully priced in for the ECB either and that’s even after the Eurozone’s preliminary inflation data for October revealed that headline inflation accelerated to 4%, double the ECB’s inflation objective of 2%. Following the Bank’s shift to a wait-and-see stance, investors may be reluctant to price in a more hawkish ECB moving forward. Perhaps they need more data supporting the need for more aggressive tightening.
Pound awaits BoE decision and guidance
As for the pound, traders are keeping their gaze locked on the Bank of England decision today. With UK inflation accelerating to 3.5% year-on-year in September, investors are nearly certain that policymakers will raise rates for the first time since August 2023.
Therefore, the pound is unlikely to be driven by the hike itself, but by the vote, the updated economic projections and the guidance on further tightening. A unanimous vote for an increase, upwardly revised inflation projections and strong willingness to continue with more rate increases could add fuel to sterling’s engines.
Wall Street rallies as oil tumbles
On Wall Street, all three of its major indices ended Wednesday’s session in the green, with the Dow Jones gaining more than 3%. Although the initial reaction was negative on concerns that the outcome of the US midterms will lead to more scrutiny regarding artificial intelligence, data-center development, banks and cryptocurrencies, expectations of fewer rate hikes by the Fed down the road supported risk appetite.
The tumble in oil prices amid bets that Democrats will oppose further military escalation in the Middle East may have also contributed to the improvement in risk appetite. WTI crude oil tumbled more than 9% yesterday, finding support near $87.50, slightly above the 200-day exponential moving average (EMA). More headlines suggesting progress in peace negotiations could push oil prices even lower, with the next key support zone perhaps at $81.20.


The euro has spread its wings
Midweek Technical Look – US100, OIL, BTCUSD

Democratic Sweep Weakens the US Dollar and Lifts Precious Metals | 5th November, 2026
Dow Holds Near 53,578 After 3% Election Rally as Democrats Win Congress
Gold Extends Rally Above $4,100 as Democratic Wins Weigh on Dollar and Yields
EBC Markets Briefing | Oil prices continue to fall after Vance questioned Iran war

GBPUSD bull run: Can the pair smash through 1.3565?






