






Central banks maintain hawkish rhetoric

OVERNIGHT
Asian equity markets are mixed this morning with many struggling to maintain any gains made overnight. At the ECB forum in Sintra, Portugal yesterday, major central bank heads – including those from the US, the Eurozone and the UK – noted that economic activity has been resilient despite significant monetary policy tightening, an indication that more policy adjustments will likely be needed.
THE DAY AHEAD
UK data releases over the next twenty-four hours include this morning’s Bank of England money and credit data as well the second estimate of Q1 GDP and the Business Barometer, both due early tomorrow. The BoE data includes mortgage approvals which have broadly stabilised in recent months after weakening in the latter part of last year. We expect an improvement in latest figures for May. UK Q1 GDP growth, meanwhile, is expected to be unrevised at 0.1%q/q. A timelier indicator of activity is our Business Barometer report for June, including whether it will continue to show a broad pickup in hiring intentions given the continuing rise in services inflation. Dovish BoE Monetary Policy Committee member Tenreyro will give a speech this evening before she departs the Bank.
The Eurozone focus remains on national inflation releases ahead of tomorrow’s Eurozone June flash CPI estimate. Italy yesterday reported a fall in annual inflation to 6.7% from 8.0% (EU-harmonised measure). Markets expect this morning’s Spanish EU-harmonised inflation rate to decline to 1.5% from 2.9%, but base effects are forecast to lead to a rise in Germany’s EU-harmonised inflation measure to 6.8% from 6.3%. Overall, we anticipate Eurozone inflation to fall to 5.5% in June from 6.1%, but for core CPI to tick back up to 5.5% from 5.3% which will maintain the pressure for the ECB to hike again next month. That would be despite survey evidence this morning that is likely to show a further fall in economic sentiment reflecting a more downbeat mood among firms. In Sweden, the Riksbank is predicted to announce a 25bp increase in interest rates to 3.75% in the face of a weakening currency and high inflation.
In the US, we may see a marginal upward revision to Q1 GDP growth to 1.4% (annualised) from 1.3%. The signs are that US economic activity remained strong in the first half of the year. Weekly initial jobless claims data, however, will be watched for further indications that the labour market has started to soften.
MARKETS
Broad US dollar strength pulled both GBP/USD and EUR/USD lower yesterday, partly reflecting lower risk appetite and Fed Chair Powell’s reaffirmation that the Fed may resume interest rate rises. GBP/USD fell towards 1.26 and EUR/USD moved below 1.09. Both pairs weakened slightly overnight.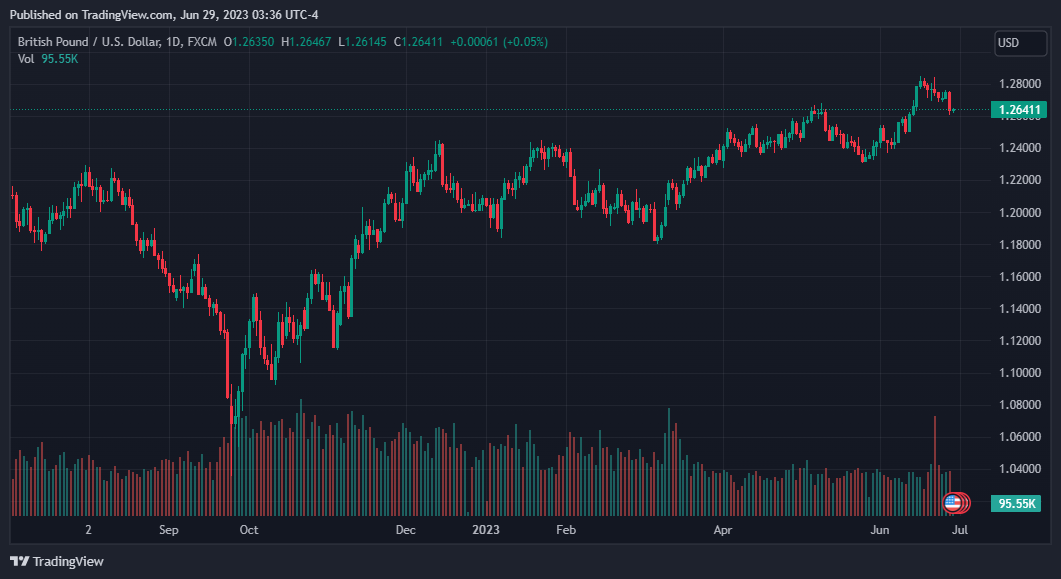


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

The euro has spread its wings

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback






