-21420261153.png)
-21420261153.png)





Dow Jones Caps Strong First Half - CPT Markets

 Market Wrap-up: Dow Jones Rallies; Oil and Gold SlideMarkets closed out June with a series of notable milestones as tensions in the Middle East eased, while investors continued to price in another Federal Reserve rate hike later this year.
The Dow Jones advanced 8.9% during the first half of the year, marking its strongest six-month performance since 2021. The S&P 500 gained 9.6%, while the Nasdaq Composite outperformed with a gain of more than 12%.
Meanwhile, easing tensions between the United States and Iran triggered a sharp decline in energy prices. Brent crude fell around 21% in June, posting its steepest monthly decline since March 2020 during the Covid-19 market collapse. WTI also lost more than 20% over the month, marking its worst monthly performance since late 2021.
However, conflicting statements from both sides suggest that the temporary peace arrangement between the US and Iran remains fragile. US President Donald Trump said on Monday that talks between the two countries would take place in Doha.
Iran's Foreign Ministry, however, denied the report, stating that no negotiations have been scheduled in the coming days. According to Iranian officials, the visit of a technical delegation to Qatar this week is unrelated to any meeting with US representatives.
Despite the recent decline in oil prices, inflationary pressures generated by the earlier Middle East conflict have reinforced the Fed's hawkish stance. As a result, the US dollar posted its strongest monthly gain since July 2025.
Markets are currently pricing a roughly 65% probability of a Fed rate hike in September, putting significant pressure on gold, which declined 11.3% in June.
In addition, the latest Job Openings and Labor Turnover Survey (JOLTS) released by the US Bureau of Labor Statistics showed job openings rising by 9,000 to 7.594 million in May, the highest level since May 2024. The stronger than expected labor market data further supported expectations for tighter Fed policy and reinforced USD strength.
Looking ahead, traders will focus on the ISM Manufacturing PMI and ADP Non-Farm Employment Change later today. Investors will also closely monitor remarks from Fed Chair Kevin Warsh at the ECB Forum on Central Banking in Sintra, Portugal.
XAU/USD: Gold Falls 11.3% in June on Fed Rate Hike Bets 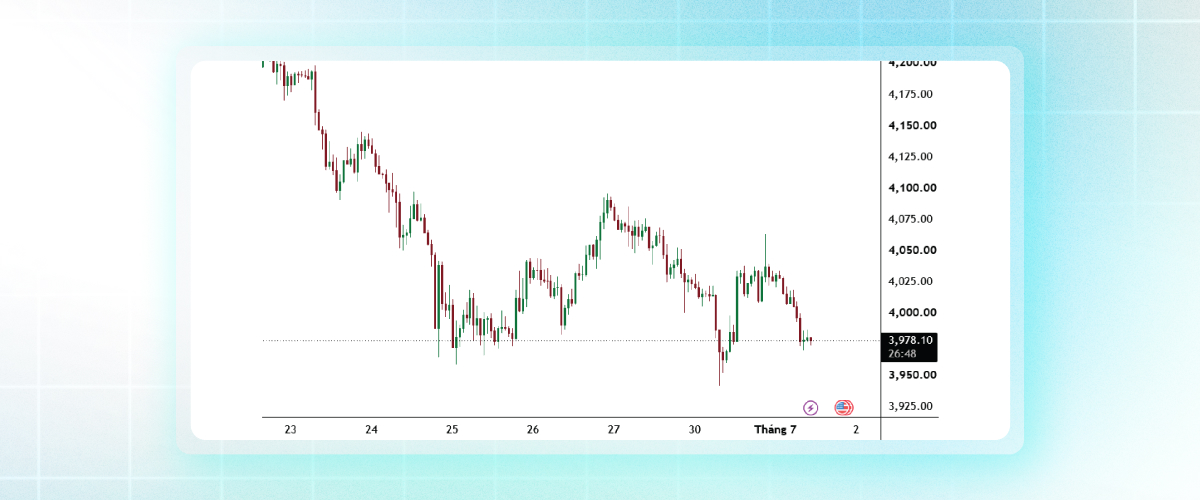
Key takeaway:
Gold declined during the June 30 session, recording its worst quarterly performance in 13 years as persistent inflation concerns stemming from the Middle East conflict continued to strengthen expectations that the Federal Reserve will raise interest rates.
Gold fell 11.3% in June alone.
According to the CME FedWatch Tool, traders currently assign around a 65% probability of a Fed rate hike in September.
Market participants are now turning their attention to today's ADP private employment report for further policy signals.
Technical Outlook:
Daily Bias: Bearish
Support: 3,942
Resistance: 4,063
Oil: WTI Slides More Than 20% in June 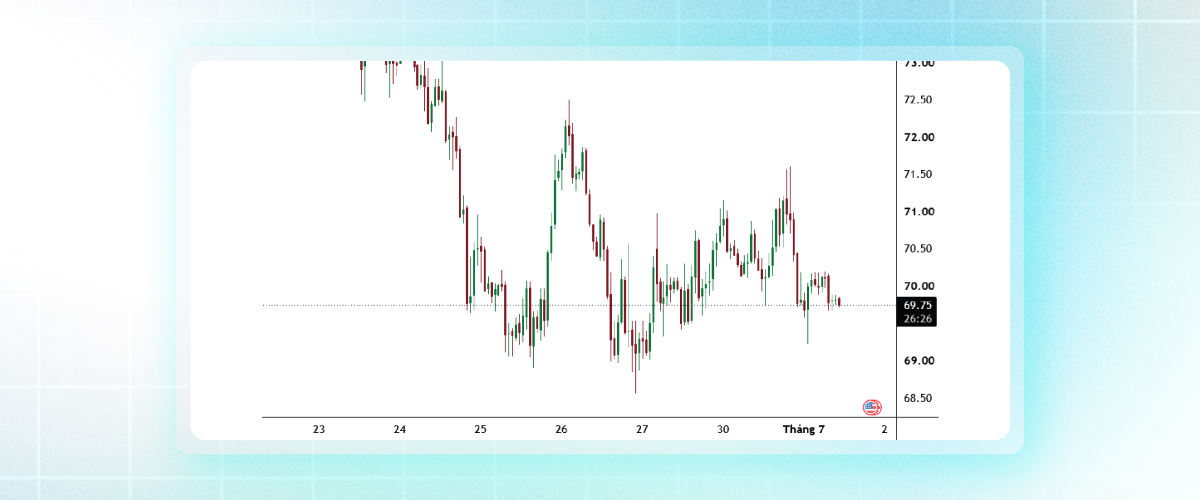
Key takeaway:
WTI crude extended losses during the final trading session of June 2026 as energy markets closely monitored the possibility of renewed US-Iran negotiations in Qatar.
WTI fell more than 20% in June, marking its steepest monthly decline since late 2021.
Despite the sharp monthly sell-off, WTI remains higher on a year-to-date basis after the US-Iran conflict disrupted oil production and transportation earlier this year.
At the same time, conflicting messages from both sides suggest that the temporary peace agreement remains fragile, leaving geopolitical risks elevated.
Technical Outlook:
Daily Bias: Bearish
Support: 69.00
Resistance: 71.60
DXY: US Dollar Holds Firm on Fed Rate Hike Expectations 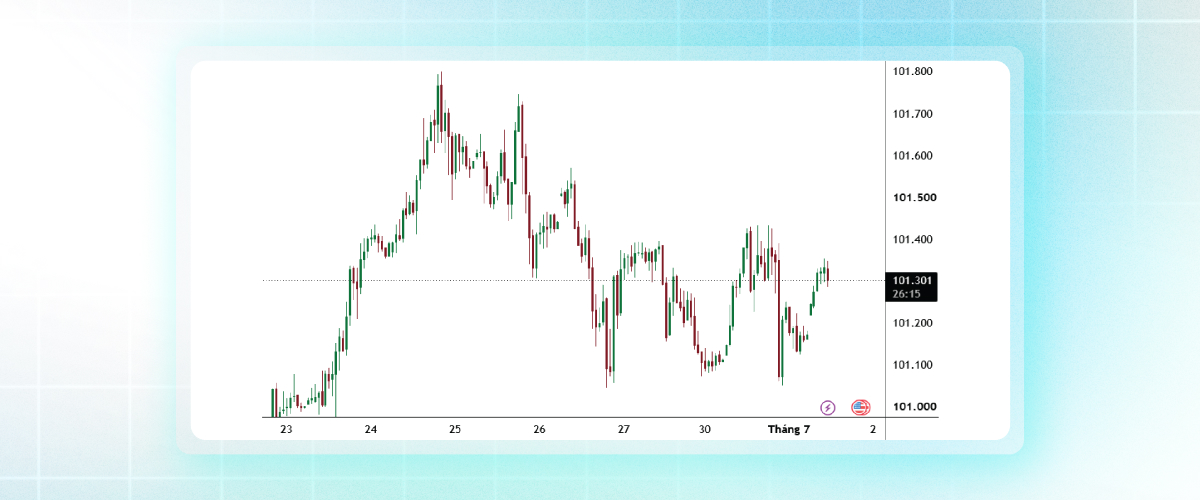
Key takeaway:
The US Dollar Index (DXY) traded sideways as investors balanced stronger US labor market data against ongoing hawkish rhetoric from Federal Reserve officials.
Cleveland Fed President Beth Hammack stated that inflation remains too high and that additional rate hikes may be necessary if price pressures persist.
Meanwhile, yesterday's JOLTS report from the US Bureau of Labor Statistics showed job openings reaching their highest level since May 2024, reinforcing expectations that the Fed may keep policy tighter for longer.
Technical Outlook:
Daily Bias: Neutral
Support: 100.12
Resistance: 101.60
EUR/USD: Euro Weakens as German Inflation Cools 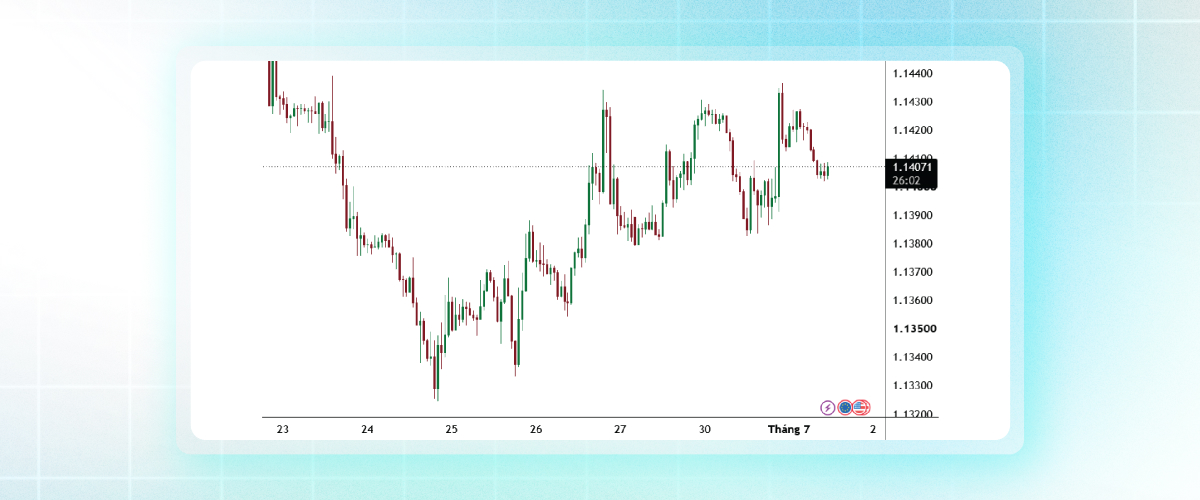
Key takeaway:
The euro weakened after softer German inflation reduced expectations of further ECB policy tightening.
Data released by Germany's Federal Statistical Office (Destatis) on Tuesday showed the country's Consumer Price Index (CPI) easing to 2.3% in June from 2.6% in May, below the market forecast of 2.5%.
The weaker inflation reading strengthened expectations that the ECB could leave interest rates unchanged at its July meeting.
Technical Outlook:
Daily Bias: Bullish
Support: 1.13821
Resistance: 1.14177
USD/JPY: Japanese Yen Hits Fresh 40-Year Low Against USD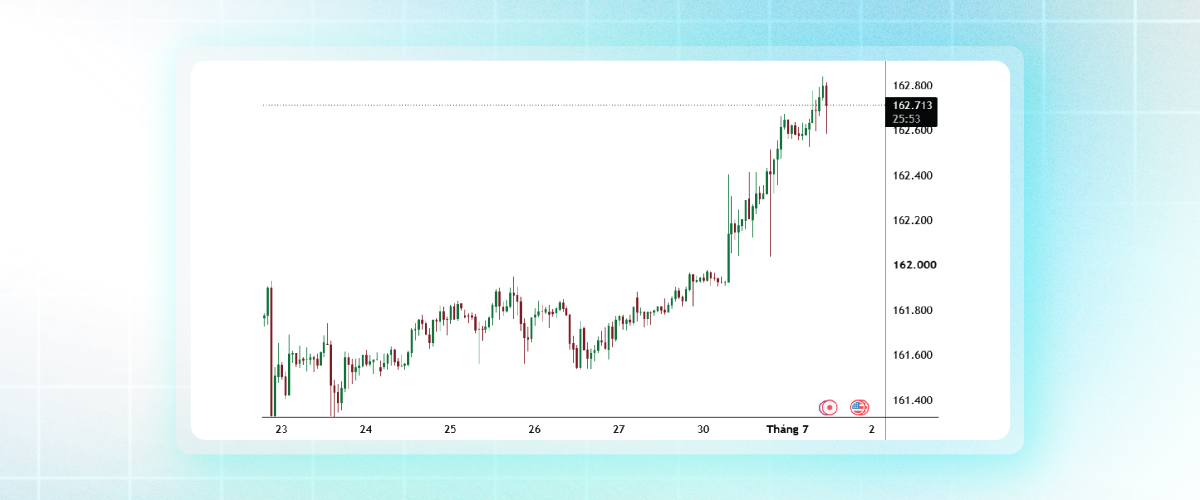
Key takeaway:
The Japanese yen weakened to its lowest level against the US dollar since 1986 as the wide US-Japan interest rate differential continued to favor the greenback.
The Bank of Japan raised its benchmark policy rate to 1% in June, the highest level since 1995.
However, expectations for additional Federal Reserve rate hikes have kept yield differentials wide, allowing carry trade demand involving the yen to remain intact.
Combined with a firmer US dollar, this continues to provide support for USD/JPY and favors the broader bullish trend.
Technical Outlook:
Daily Bias: Bullish
Support: 162.40
Resistance: 163.00
Markets are currently being driven primarily by the repricing of Federal Reserve expectations rather than geopolitics. While easing tensions between the US and Iran triggered a sharp correction in oil prices, resilient US labor market data and persistent inflation concerns have reinforced the case for tighter Fed policy.
That combination has supported the US dollar, pressured gold, and widened interest rate differentials in favor of USD across major currency pairs, particularly against the yen.
Equity markets have remained resilient as geopolitical risks eased, but traders are now shifting their focus to today's ISM Manufacturing PMI, ADP employment report, and comments from Fed Chair Kevin Warsh for further clues on the Fed's next policy move.
If you are looking for a platform to take advantage of market volatility, CPT Markets is a compelling choice. Trade global markets on advanced trading platforms with competitive spreads, fast execution, and a seamless experience across all devices.
Whether you are a beginner or an experienced trader, trading short-term or long-term, the right platform can make the difference - Trade smarter with CPT Markets!
This content is for informational purposes only and should not be considered investment advice. Trading financial products such as Forex and CFDs involves a high level of risk and may not be suitable for all investors. You may lose all of your invested capital. Please ensure that you fully understand the risks involved and carefully consider your financial situation before trading.

The euro has spread its wings

Democratic Sweep Weakens the US Dollar and Lifts Precious Metals | 5th November, 2026

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026
The dollar concedes the Democrats’ victory
What the Democratic Midterm Win Means for Gold, US Stocks and Bitcoin






