

Markets have been tricked, but is there a treat around the corner?

Stock market weakness lingers
US equity indices remain in the spotlight as investors ignore the strong elements of AI-related earnings announcements and focus on the weaknesses. That was the case again when both Amazon and Intel mostly beat Q3 forecasts, but their soft Q4 guidance, adding to the already sour sentiment, triggered losses for both stocks.
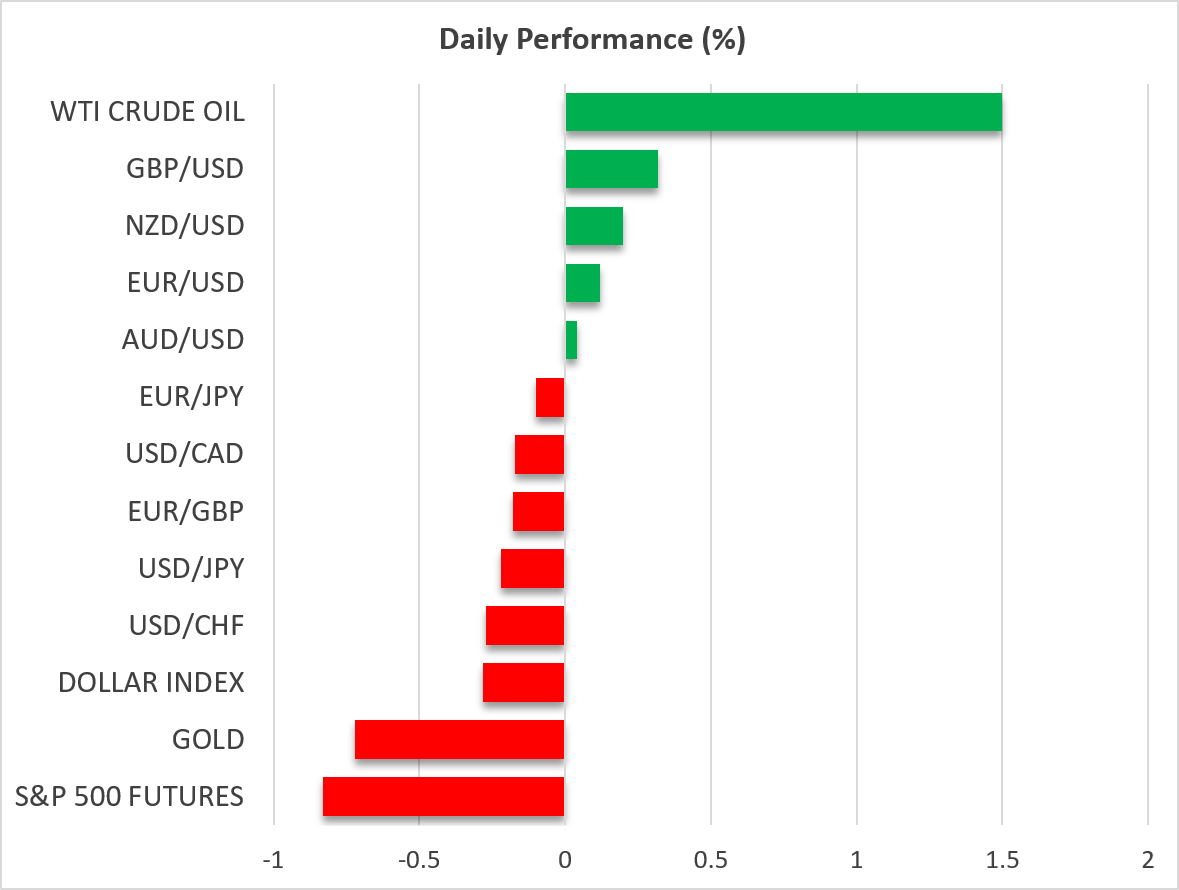
The Nasdaq 100 index closed the session well in the red, with the other two major US indices following suit, as investors scratch their heads about how long this decline could continue and how low the Nasdaq can drop. US investment houses are pointing to a potential support in the 7,100 area for the S&P 500 index, around 9.5% below from the recent all-time high and about 7% below from current levels, which means that the potential sell-off might just have begun.
The situation is obviously more critical for the Nasdaq 100, though, as it has completely erased the September rally and is now trading at a key support area, which has acted as a floor multiple times during May. Should the drop persist, the next key support area is located at the 200-day simple moving average (SMA) at 29,578. Back in March, during the first leg of the US-Iran conflict, the Nasdaq’s drop below this lagging indicator proved short-lived, with a 35% rally ensuing by early June.
Not everything is bleak though
Despite the negative risk appetite and significant decline, bulls might take solace from the fact that, despite the market angst, the current sell-off might be a short-term blip ahead of another strong rally. Notably, the short-term outlook until year-end and Q1 2027 appears to be positive. Research has shown that the period after the midterm elections, regardless of the winner, tends to be bullish for stocks, with gains typically boosted into year-end by the famous Santa rally that takes place after the Thanksgiving holiday. Hence, for some investors, the current correction could be seen as a buying opportunity.
ECB and BoJ remain on the tightening path
Despite the current market weakness, the importance of AI going forward is undeniable, although central banks are starting to nag about the AI-related funding pushing sovereign bond yields higher. That was one of the key discussion topics during yesterday’s ECB press conference, which was obviously overshadowed by the news of Lagarde’s departure. She is determined to leave the ECB on a high note though and thus the Council is expected to announce another 25bps hike in December, unless there is an important development in either of the two ongoing conflicts. Interestingly, markets are currently pricing in just a 64% probability of a move in 45 days’ time, which seems quite low, thus opening the door to some euro appreciation if the situation in France remains calm.
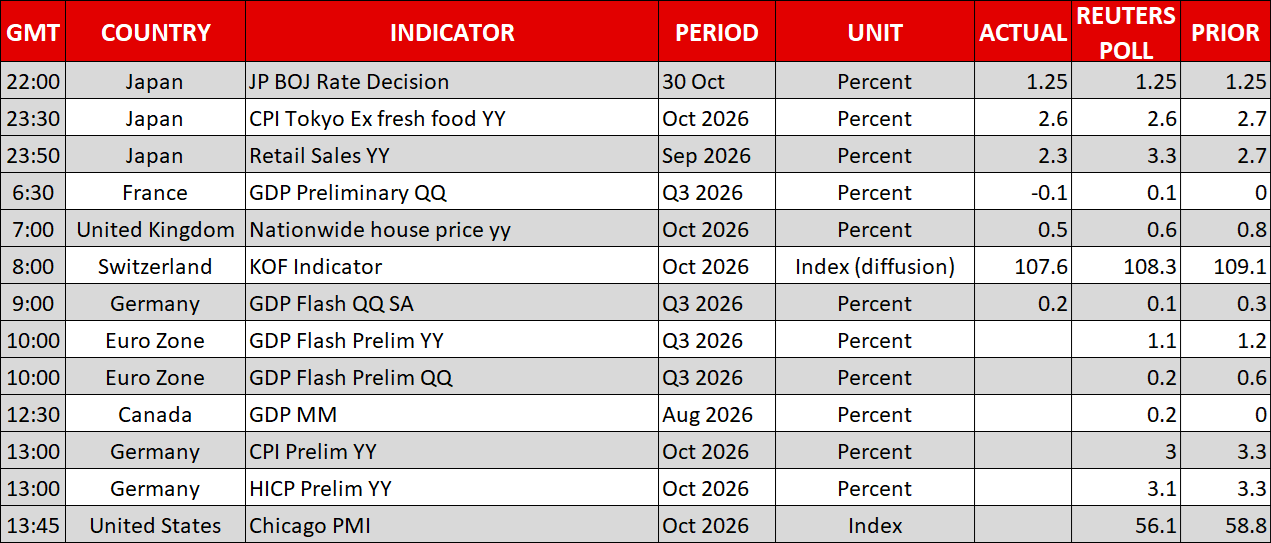
The same can be said for the BoJ, where, despite today’s hawkish hold with one dissident and upgraded inflation forecasts, markets price in just a 50% probability of a December 18 rate hike, down from being fully priced in at the end of the September. A gradual increase in this probability could help dollar/yen escape the current range-trading, although developments in US equities may have a bigger impact at this stage.
Oil price rally persists
At the end of the day, market movements remain dependent on oil prices. There has been some progress made in the two ongoing conflicts – for example there are reports that Ukraine has not been targeting Russian refineries lately – but nothing noticeable for the markets to pick up on. WTI spot oil prices continue to climb, reaching the mid-September high of $105.76. If reports about President Trump preparing for a fresh military operation after the midterm elections prove true, then equity investors will have a bigger headache than the current soft guidance offered by recent earnings announcements.
Gold and bitcoin suffer
Gold and bitcoin continue their journey lower, despite the mixed dollar performance. Gold has dropped below the $4,000 level, getting pretty close to the late-June low of $3,942, with the main question being whether central banks and sovereign wealth funds will come to the rescue once again. Similarly, though mostly for different reasons, the cryptocurrency market is in disarray following a massive hack at the crypto giant Binance. Bitcoin has rebounded from the $76k low, but the latest shock could dent the chances of a significant rally towards year-end.
EURUSD recouped its losses
The impact of the Binance hack is unlikely to last long
Week Ahead – Nonfarm payrolls and US midterm elections take center stage
AI Spending Fears Erase $500 Billion from Alphabet’s Market Value
BoJ Hawkish Hold and a Softer US Dollar Shape Currency Markets | 30th October, 2026
Binance Security Fears Send Bitcoin to Six-Week Low
EBC Markets Briefing | Oil prices gain as fresh attack on Iran is planned