-21420261153.png)
-21420261153.png)





US Stocks Rebound as Oil and Treasury Yields Ease

Market Wrap-up: US Stocks Recover as Oil Prices and Yields Retreat
US equities advanced on 17 September, recovering some of the previous session’s losses after the Federal Reserve (Fed) raised interest rates for the first time in three years. Lower Treasury yields and oil prices, alongside gains in major technology stocks, supported the rebound.
The Dow Jones Industrial Average rose 316.14 points, or 0.61%, to 51,778.04. The S&P 500 gained 1.14% to 7,637.76, while the Nasdaq Composite advanced 1.69% to 26,418.30.
Technology shares led the gains, with Nvidia and Amazon rising more than 2%, Microsoft adding 1.5%, Qualcomm gaining 2% and Intel climbing 7%.
US 10-year Treasury yields fell by more than 7 basis points to 4.93%, moving back below the 5% threshold after climbing above it on Wednesday following the Fed’s decision.
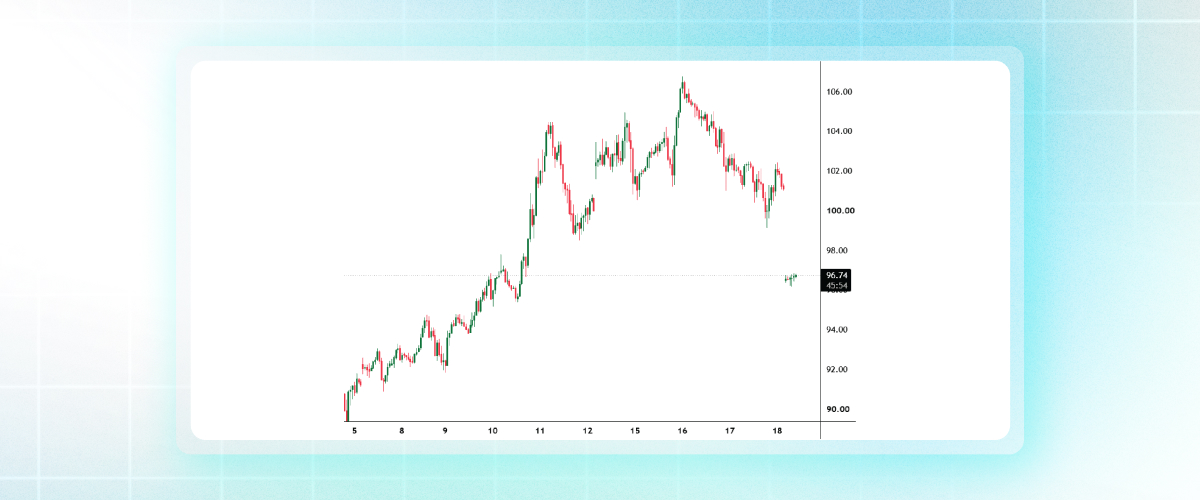
Oil prices retreated, with WTI crude falling 0.51% to $101.91 a barrel and Brent crude declining 0.95% to $104.82. Despite the pullback, WTI remained higher for the week and month, gaining nearly 2% and more than 18%, respectively.
The decline came as concerns over supply disruptions eased following reports that Saudi Arabia was supplying additional crude cargoes to Asian refineries through ship-to-ship transfers near Oman’s Sohar port. The arrangements helped ease concerns over disruptions to the East-West pipeline, which was shut after being damaged in a drone attack.
While US Energy Secretary Chris Wright described the disruption as temporary, independent analysts warned that repairs could take weeks or even months.
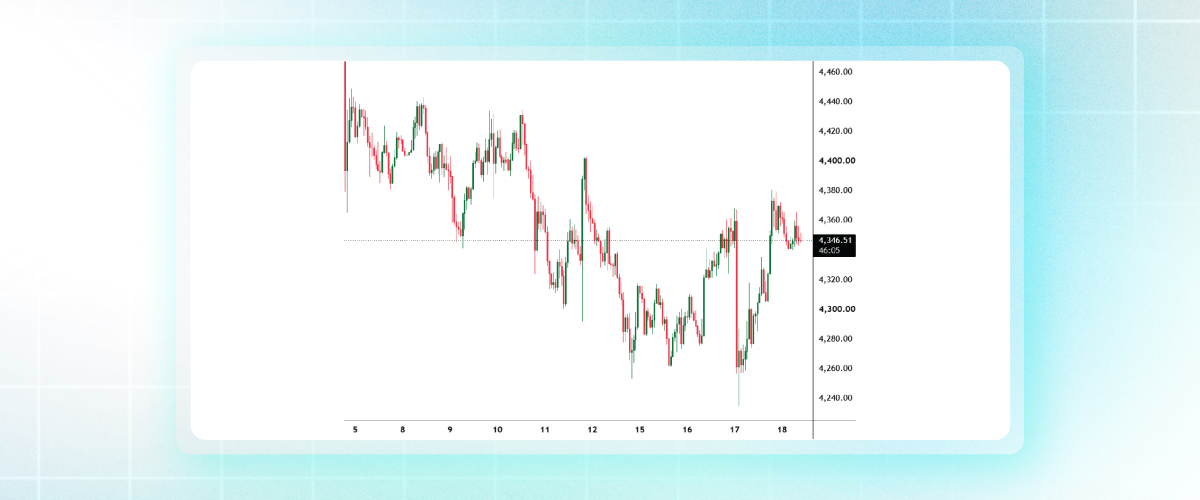
Gold also rebounded, with spot prices rising 2.4% to $4,364.29 an ounce after reaching a near six-week low in the previous session. The recovery coincided with easing oil prices, a weaker US dollar and lower Treasury yields.
David Meger of High Ridge Futures said softer energy prices had helped relieve some pressure on the gold market.
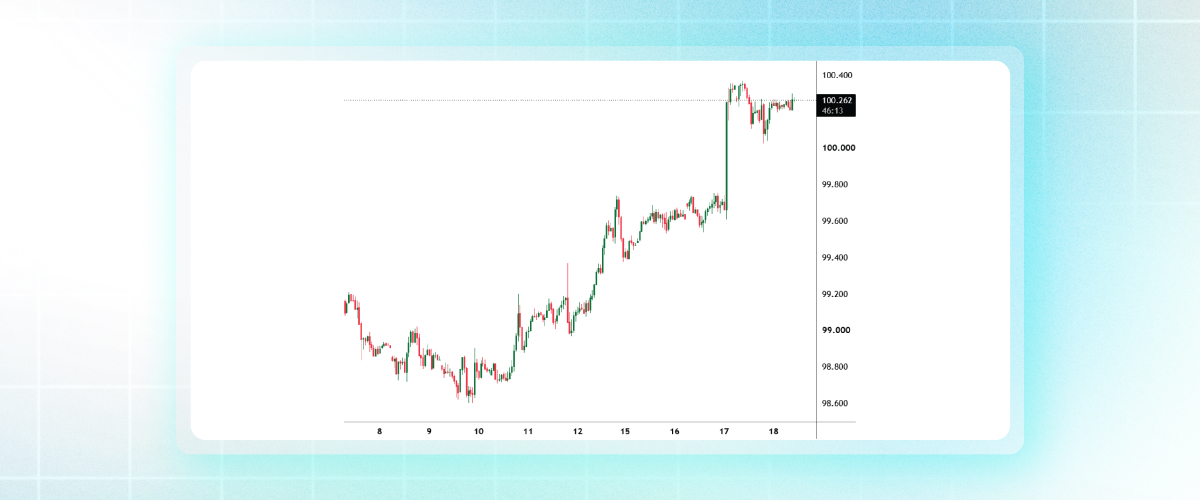
The US Dollar Index (DXY) traded just above 100.00 on Thursday, easing from a seven-week high earlier in the week. Although the Fed’s rate increase initially supported the dollar, those gains faded as energy prices retreated and President Donald Trump reiterated calls for substantial rate cuts.
The Fed raised rates by 25 basis points on Wednesday and signalled the possibility of another increase this year, with Chair Kevin Warsh stressing that inflation remained too high.
Meanwhile, the Bank of England held rates at 3.75% in a 6-3 vote, with three policymakers favouring an increase.
The Bank of Japan (BoJ) raised its short-term policy rate by 25 basis points to 1.25% from 1.00% on Friday, following its two-day monetary policy review. The decision was in line with market expectations.
Looking ahead, markets will focus on upcoming US data, including Industrial Production and the CB Leading Index, alongside further central bank developments.
DXY:
Key takeaway:
DXY traded just above 100.00 as the dollar eased from its seven-week high.Markets are assessing the Fed’s hawkish outlook alongside shifting rate expectations.Technical Outlook:
Daily Bias: BullishSupport: 100.00 Resistance: 100.40
Gold:
Key takeaway:
Spot gold rebounded 2.4% to $4,364.29/oz, recovering from a near six-week low.Lower energy prices, a weaker USD and easing Treasury yields supported the recovery.Technical Outlook:
Daily Bias: Bearish with Rebound PotentialSupport: 4,305 Resistance: 4,402
Oil:
Key takeaway:
Brent fell below $105/bbl as concerns over supply disruptions eased.WTI remained higher for the week and month, despite the latest pullback.Technical Outlook:
Daily Bias: BearishSupport: 95.39 Resistance: 102.42
Japanese Yen:
Key takeaway:
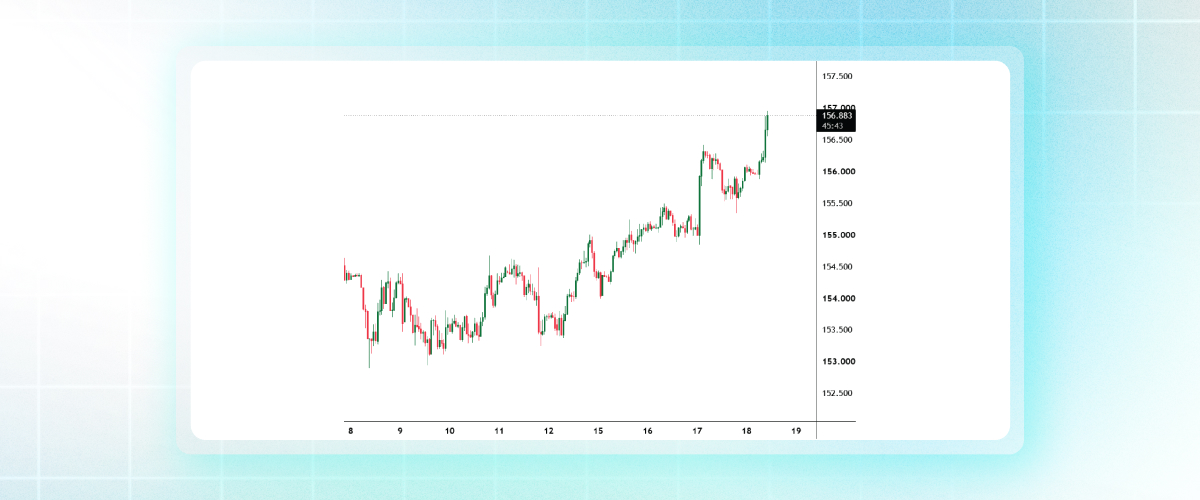
The BoJ raised its short-term policy rate by 25 basis points to 1.25%, in line with market expectations. The Japanese yen weakened after the BoJ’s rate decision, with USD/JPY moving towards 157.00. Technical Outlook:
Daily Bias: BullishSupport: 155.35Resistance: 157.50
Calendar Watch:
Industrial Production: Measures changes in US industrial output, providing insight into activity across the manufacturing, mining and utilities sectors.CB Leading Index: Tracks economic indicators that may signal the future direction of US economic activity.
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as Forex and CFDs involves a high level of risk and may not be suitable for all investors. You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.
RBA’s Split Rate Hike and US Midterm Uncertainty Shape Currency Markets | 3rd November, 2026
Central Bank Signals and Easing Safe-Haven Demand Shape Currency Markets | 2nd November, 2026
BoJ Hawkish Hold and a Softer US Dollar Shape Currency Markets | 30th October, 2026
The ECB, the Bank of Japan and the Fed prefer to wait until December
Fed Holds Rates; PCE and ECB Take Center Stage
Rate-Hike Bets and a Hawkish Fed Hold Shape Currency Markets | 29th October, 2026
Dollar Firms and Oil Rebounds Ahead of Fed Decision