-482026738.png)


Week Ahead: Fed Decision, GDP and PCE Inflation Put Dollar, Gold and S&P 500 in Focus

Key Takeaways
- US GDP grew at an annualised 2.2% in Q2, and September unemployment stood at 4.2%, pointing to a mature expansion rather than a recession.
- September CPI rose 3.7% year-on-year and PPI rose 1.3% month-on-month, keeping further tightening on the table.
- Markets expect the Fed to hold its target range at 3.75%-4.00% this week.
- S&P 500 earnings were projected to grow 29% year-on-year in Q3, though the average earnings beat is well below its five-year norm.
- Traders are watching SP500, XAUUSD, USOIL, USDX and EURUSD around the Fed decision and the 29 October GDP and PCE releases.
Markets enter the week of 26 October with the Federal Reserve at the centre of the outlook. US equities fell for a second consecutive week, with the S&P 500 down 0.5% and the Nasdaq Composite down 0.7%. Semiconductor shares dropped 3.2%, and lower Treasury yields failed to lift the broader market. Investors now need corporate results to support prices as higher energy costs threaten business margins and household spending.
Why Traders Are Watching Global Markets
Inflation is limiting the Fed’s choices. September consumer prices rose 0.6% month-on-month and 3.7% year-on-year, while producer prices rose 1.3% in the month, adding pressure on business costs. Markets expect a hold this week, but persistent inflation could keep further tightening possible, and officials must balance price pressures against weaker hiring.
The Fed announces its decision before the 29 October GDP and PCE releases, so markets may reassess the policy outlook soon after the meeting. Hotter inflation could support the dollar and weigh on gold through higher expected interest rates. Softer inflation could ease that pressure, provided growth holds up.
Earnings remain the main support for equities. According to FactSet’s 16 October report, S&P 500 earnings were projected to grow 29% in Q3, with full-year 2026 growth forecast at 32.8%. The forward P/E of 19 times sits just below its 10-year average of 19.1 times. However, although 84% of reporting companies beat estimates, aggregate earnings exceeded expectations by only 2.6%, against a five-year average of 7.5%. With the 10-year Treasury yield around 5%, fixed income also offers equities more competition for capital.
Key factors influencing markets include:
- Federal Reserve policy: Signals on further tightening could move the dollar, gold and stocks.
- US inflation: Core PCE and CPI readings keep pressure on policymakers.
- Treasury yields: A 10-year yield near 5% gives investors a competitive alternative to equities.
- Corporate earnings: Profit guidance matters more now that beats are narrower.
- Energy prices: Higher oil costs threaten margins and household spending.
Three paths could guide market direction:
- Continued expansion: Easing inflation, stable yields and resilient profits could support new highs.
- Stagflationary slowdown: Weak demand with persistent inflation would squeeze margins and leave equities vulnerable to sharper swings.
- Recession: A broader fall in employment, consumption and profits could be priced in by shares before official data confirm it.
Key Movements of the Week
SP500
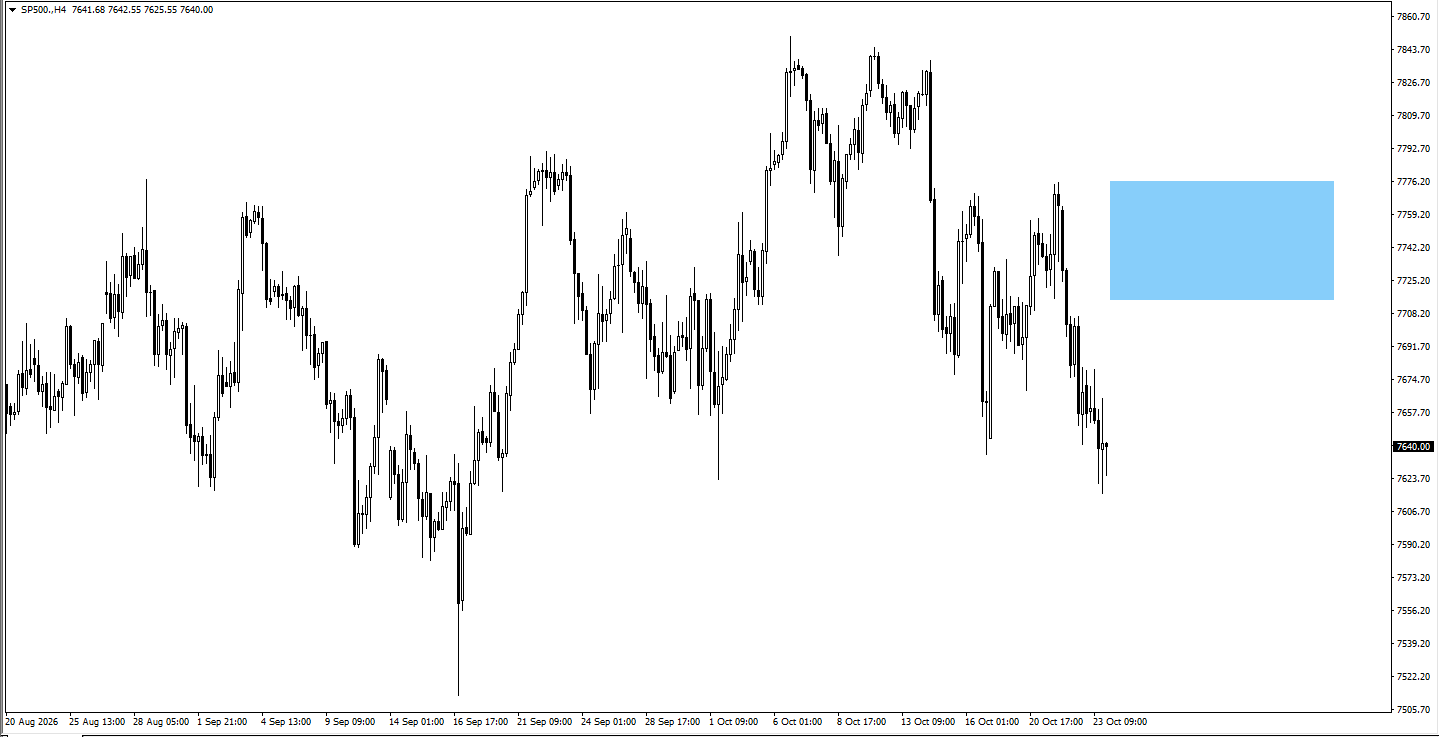
Price could rise from the current area, but monitor the type of price action to determine the structure. If price rises, monitor price action at 7,735.
XAUUSD
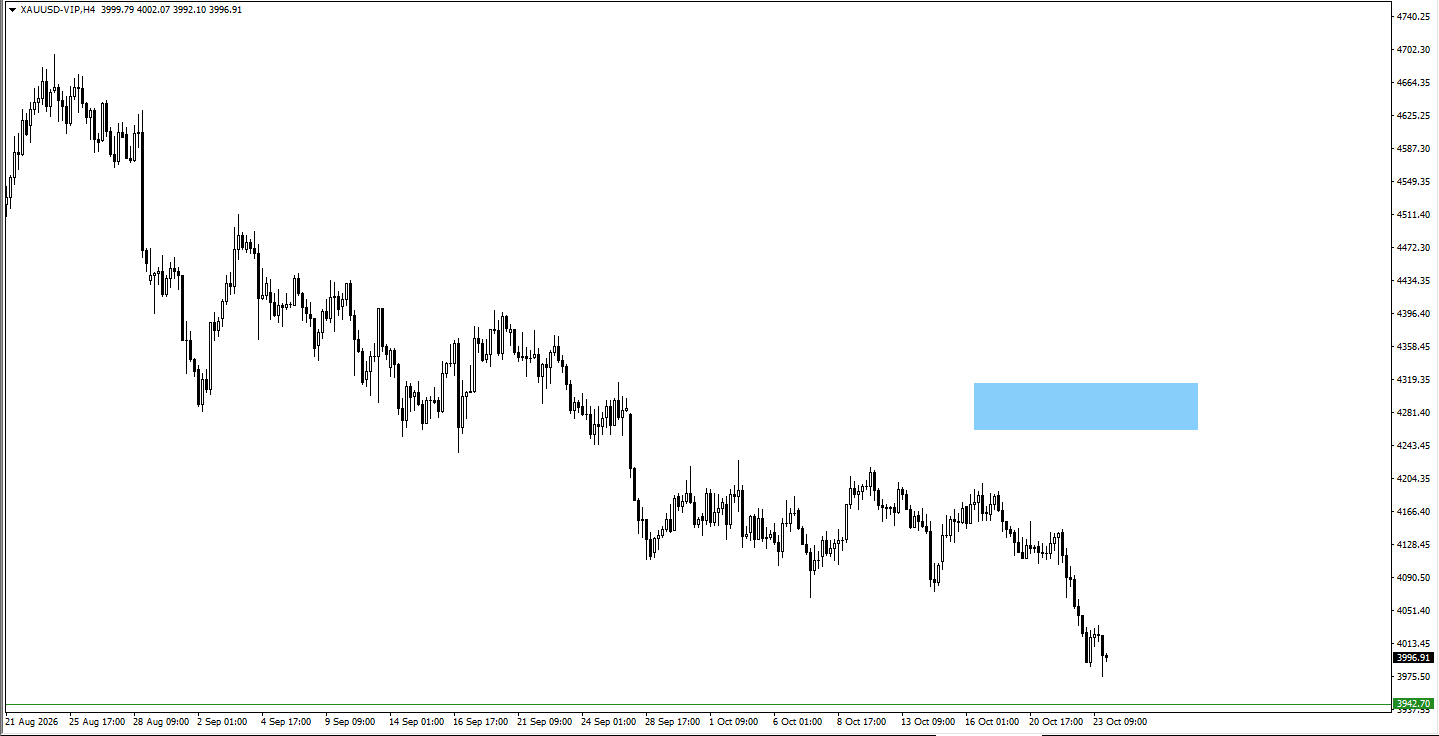
If price trades lower, look for bullish price action at 3,942.70.
USOIL
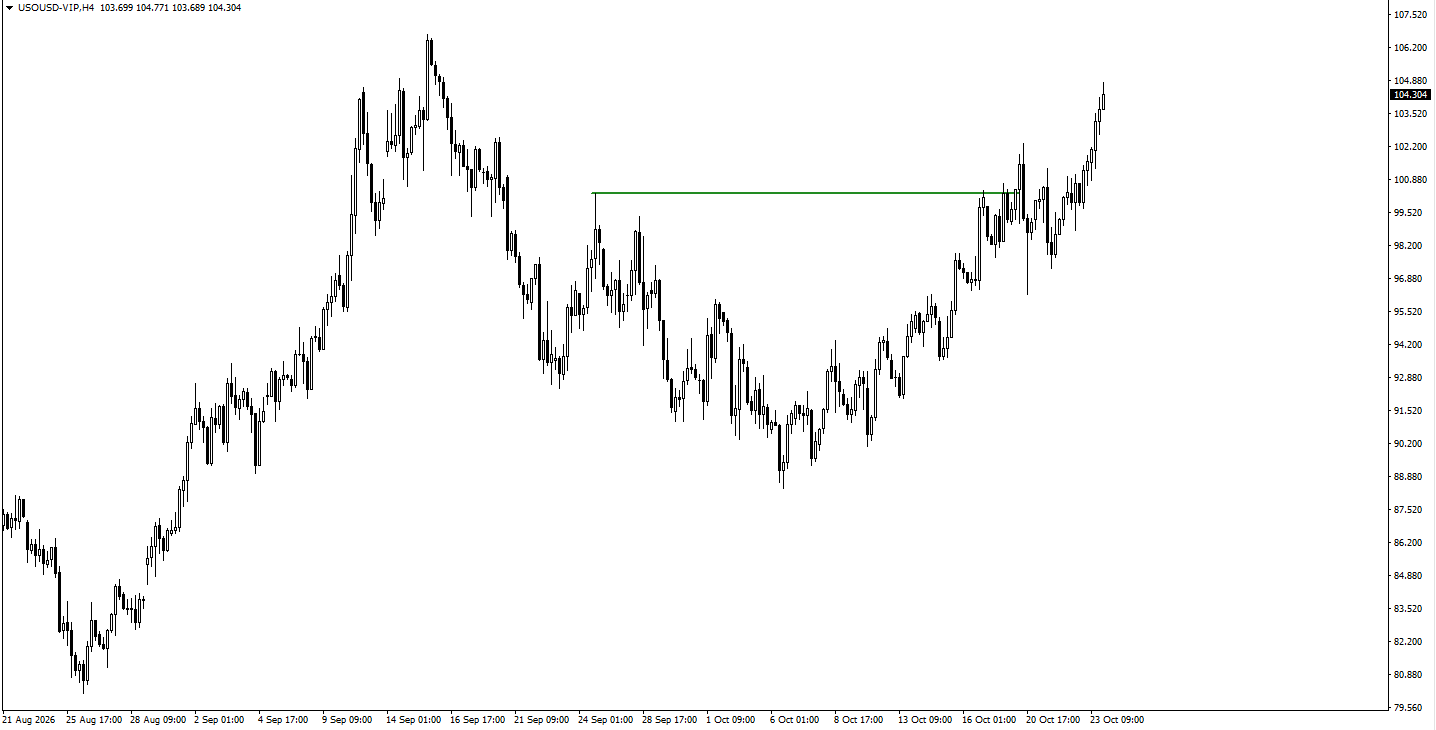
USOIL broke 102.546. Monitor price action once it breaks 106.745.
USDX
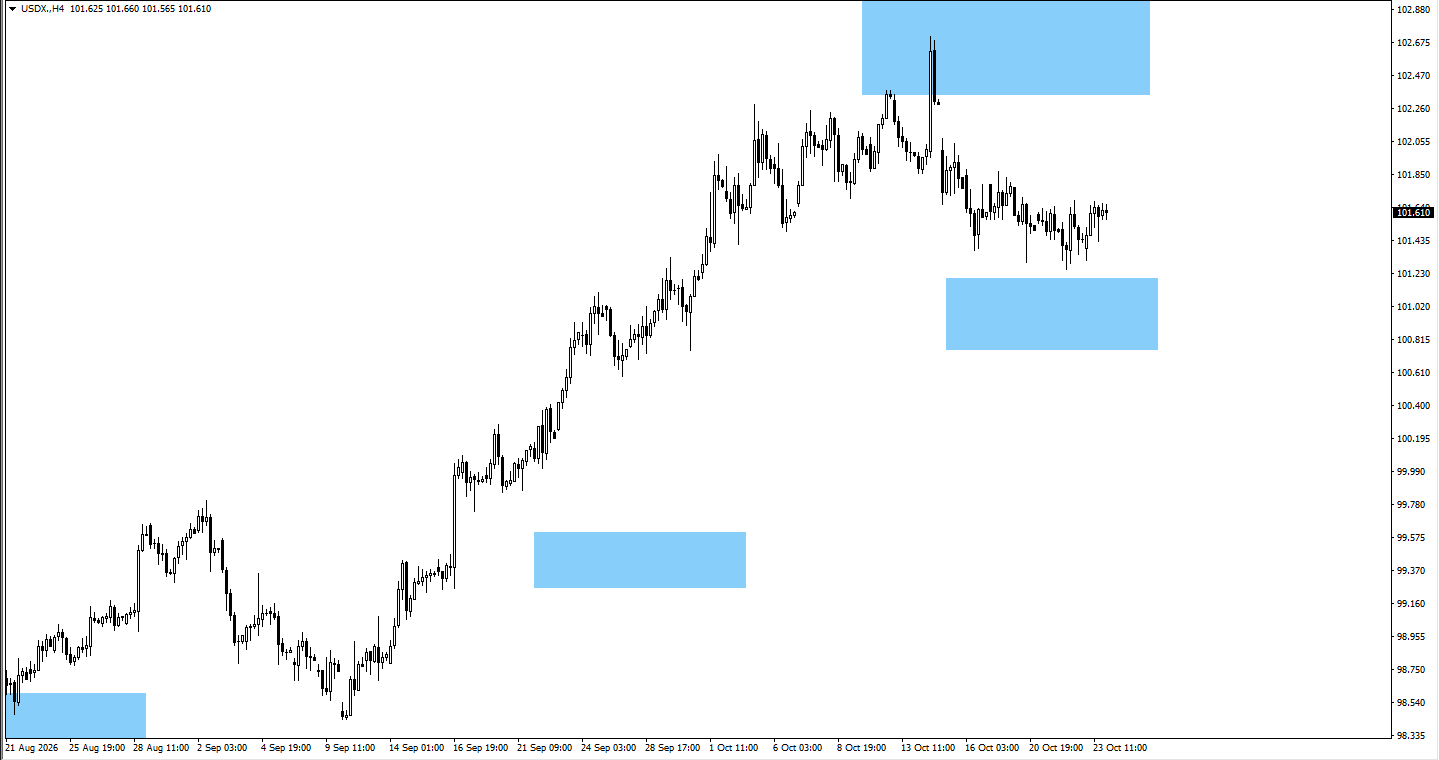
USDX is trading near the 101.00 monitored area. If price trades lower, look for bullish price action at 101.00.
EURUSD
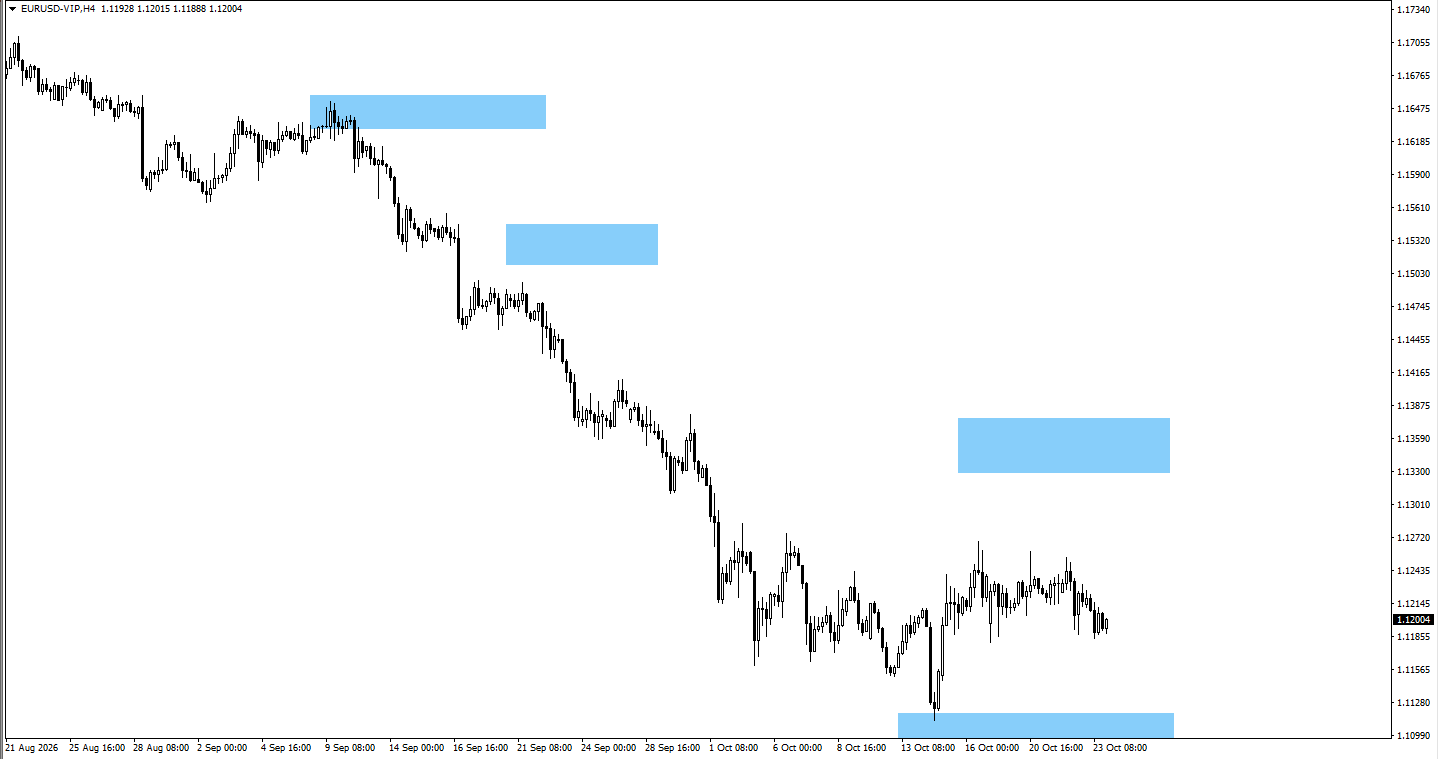
If price consolidates, EURUSD could trade higher. In that case, monitor price action at 1.1350.
What to Watch Next
A busy calendar of central bank decisions and inflation data leads the week:
- 28 October: Australian CPI y/y (forecast 4.20%, previous 4.00%), RBNZ Official Cash Rate (forecast 3.00%, previous 2.75%) and Bank of Canada overnight rate (forecast 2.50%, previous 2.25%)
- 29 October: FOMC statement, US Core PCE m/m (forecast 0.30%, previous 0.20%) and the ECB decision and press conference
- 30 October: BOJ policy rate and press conference (forecast and previous both <1.25%)
This week tests whether markets can sustain their initial response to the Fed once GDP, PCE and corporate results arrive. A rebound backed by both economic data and earnings guidance would be evidence of renewed buying demand. The US may be late in its economic cycle without necessarily being at the end of its stock market cycle.
For the full article, click here.
The US Midterms Are the Next Test for Gold, the Dollar and Stocks
Five Central Banks Set to Shape Market Sentiment This Week
Weekly Market Recap and Forecast: AI Stocks Face Renewed Pressure as Oil Prices Surge, Gold Falls Below $4,100
EURUSD failed to break through the French barrier
Gold Slips Below $4,000 as Inflation Fears and a Hawkish Fed Outlook Outweigh US–Iran Tensions
Oil Holds Near Highs as Gold Slips Ahead of Fed Decision
GOLD Below $3,999 or Above $4,501? What Could the Coming Week Bring?