

Diplomatic hopes rise but equity markets focus on earnings

Has progress really been made on the two open conflicts?
In a rather quiet week monopolized by earnings announcements, there has been a flurry of reports about significant progress being made in both the Ukraine-Russia conflict and the Middle East. In the case of the latter, news articles published yesterday afternoon detailed a proposal prepared by both Qatar and Pakistan, which appears to have the initial approval of both the US and Iran.
This proposal includes the release of a small amount of frozen Iranian funds in exchange for access by the International Atomic Energy Agency (IAEA) to Iranian nuclear sites, aiming to reduce the angst by President Trump and Israeli officials about Iran’s nuclear intentions. This agreement could obviously act as the basis for broader discussions regarding the end of the Houthi attacks on Saudi Arabia and the reopening of the Strait of Hormuz, which Iran has already proposed in previous peace plans.
Meanwhile, progress on the other conflict seems to be even more significant. The strong pressure from Trump – restrictions on the supply of Patriot missiles and military intelligence information, strong criticism of Ukrainian President Zelenskyy about repeatedly targeting Russian oil refineries, with Trump even suggesting his replacement – appears to have been successful.
US envoy Witkoff is scheduled to meet with President Putin today, and while US news outlets point to another deal with Russia to free jailed Americans, Witkoff is carrying the result of intense discussions between Zelenskyy, US and European officials in Oslo. The ball is now in Putin’s court to make the next move, with reports about a potential Trump-Zelenskyy-Putin summit being prepped to finally resolve the 4½-year conflict.
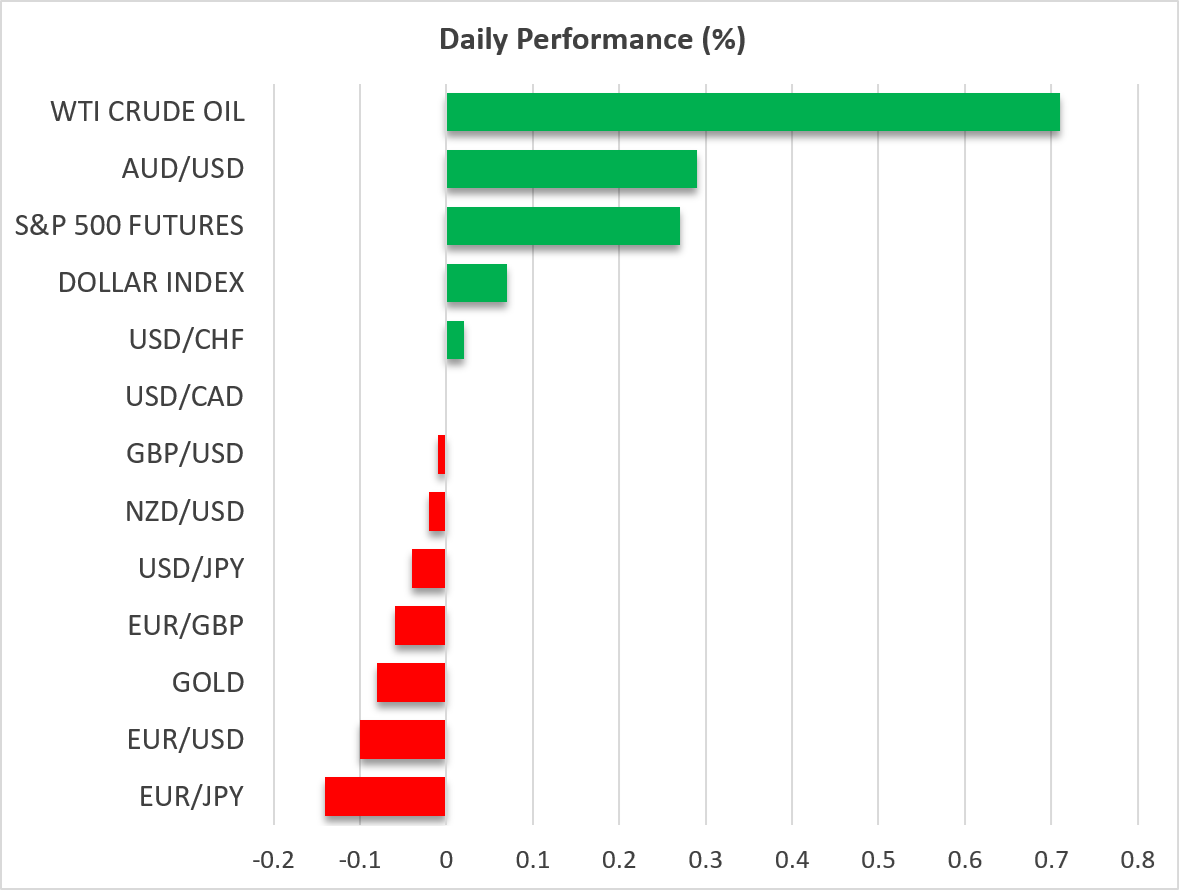
Progress on either front would significantly impact the current risk premium in oil prices and affect central bank expectations for December. However, so far, WTI spot oil prices are completely ignoring the plethora of headlines, having failed to post a significant decline in yesterday’s session and instead rising above $100 following fresh attacks on ships crossing the Hormuz and further aggressive rhetoric from Iran’s IRGC.
Investors are potentially not buying the progress advertised by US media, potentially treating the latest headlines as a political tactic from Trump ahead of the US midterm elections, where the Republicans’ chances of retaining control of the Senate are dwindling and the battle for the House of Representatives appears to have already been lost.
Frail risk sentiment
Despite the improved performance of the Nasdaq 100 index this week, most AI-related firms continue to feel the pressure regarding valuations, borrowing, investment spending and credible returns. Specifically, Netflix’s weak Q4 guidance was not taken lightly by investors, CoreWeave remains in the spotlight due to its high debt exposure, a number of smaller AI-related firms have postponed their IPOs due to weaker investor demand, while Anthropic’s draft IPO details are under close scrutiny.
Following the solid SpaceX results, the focus shifts to today’s earnings from Meta Platforms and Tesla, with investors also monitoring announcements from smaller firms like Lam Research and Texas Instruments. The lack of stellar results and upbeat guidance could further dent risk sentiment, putting the Nasdaq 100 index under renewed pressure and potentially underperforming the more traditional Dow Jones index.
Euro under pressure
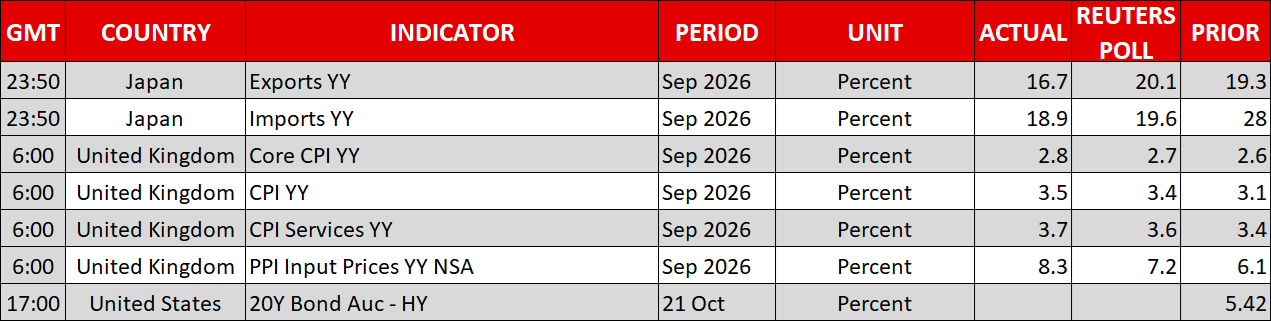
Developments in France, where Marine Le Pen is seen as the main beneficiary of the current unrest, are keeping the euro under pressure. Notably, euro/pound is currently down 1.7% in October, the worst monthly performance for this pair since January 2024, as the British pound is taking advantage of the euro’s troubles, while solid UK labour market data and upside surprises in today’s CPI and PPI reports have cemented the early November BoE hike bets. That said, investors might be underestimating the impact of the October 28 UK Autumn Budget statement, potentially threatening the recent pound gains.
Weekly Market Recap and Forecast: AI Stocks Face Renewed Pressure as Oil Prices Surge, Gold Falls Below $4,100
EURUSD failed to break through the French barrier
Week Ahead – Central bank and earnings bonanza could roil markets
Tech selloff weighs on dollar as Treasury yields tumble
Bitcoin: all eyes on the next move
EBC Markets Briefing | Crude market on a roll as US prepares for new attacks
Brent Crude Climbs Above $114 as US–Iran Tensions Revive