

Dollar dominates as risk appetite remains fragile

A big week for the US technology sector
After four consecutive weeks of losses, the Nasdaq 100 index managed to post decent gains last week. However, there are still numerous challenges ahead, starting with the fact that Asian stocks had another weak start to the week today, as investors are trying to gauge the broader risk appetite.
Nvidia remains in the spotlight, mostly for the wrong reasons, as speculation and commentary about the next CEO are rife. With its share price trading around 33% below its recent all-time high level, ex-CEO Huang is apparently mulling a quiet comeback, partly demanded by shareholders worried about the company’s future.
However, such a move, just a few days after his removal, would be a risky endeavour, particularly as even Treasury Secretary Bessent called for a “dramatic leadership shakeup” and stated that Nvidia “should look outside the company for its next CEO”. Nvidia’s Q3 earnings will be released on Tuesday evening, after US markets close, and confirmation of current expectations for another massive increase in earnings could help ease pressure on its stock price for a few sessions.
Meanwhile, with leading US investment banks continuing to highlight their bullish stance on equities, investors are preparing for the Anthropic IPO. Its shares are set to be priced on Wednesday and start trading on Thursday, November 19, with the estimated company valuation reaching $1.4trn, 30% below the original estimate of $2trn. With 22 banks lined up to facilitate this IPO and the offering apparently seven times oversubscribed, the success of the endeavour at a tumultuous period of the AI industry could help ease selling pressures in equity markets. But the main question remains whether this expected calmness will last.
Is the Fed really pondering a 50bps move in December?
Part of the mixed performance seen in equities lately is due to the higher Fed rate hike expectations. Somewhat unexpectedly, as if President Trump’s defeat at the midterm elections unchained the FOMC, Fedspeak has been overly hawkish, supported by the solid US CPI and PPI reports.
With Fed doves like San Francisco’s Daly and Vice Chair Jefferson finally acknowledging that inflation is elevated, and Boston’s Collins carefully stating that it is “possible the Fed may have to raise more than expected”, markets continue to fully price in a 25bps rate hike in December and a 10% chance of a 50bps move. The latter looks slightly too aggressive, but US economic data and elevated oil prices could support current expectations.
Chair Warsh is scheduled to speak at 17:00 GMT, but given his dislike for providing forward guidance, New York’s Williams and Cleveland’s Hammack comments could prove more market-moving.
Middle East remains in the spotlight
At the end of the day, developments in the Middle East could overshadow Nvidia’s news and even the Anthropic IPO, as there are fresh reports of increased pressure on Trump to greenlight another military operation against Iran. With the WTI spot oil prices hovering around the 200-day simple moving average (SMA), another escalation could quickly trigger another rally towards the $95 area.
That said, considering that Trump is expected to meet with Chinese President Xi and Russian President Putin during the Asia-Pacific Economic Cooperation (APEC) summit in Shenzhen, China, this week, any decisions on military actions against Iran appear to have been postponed.
Dollar is the driving seat
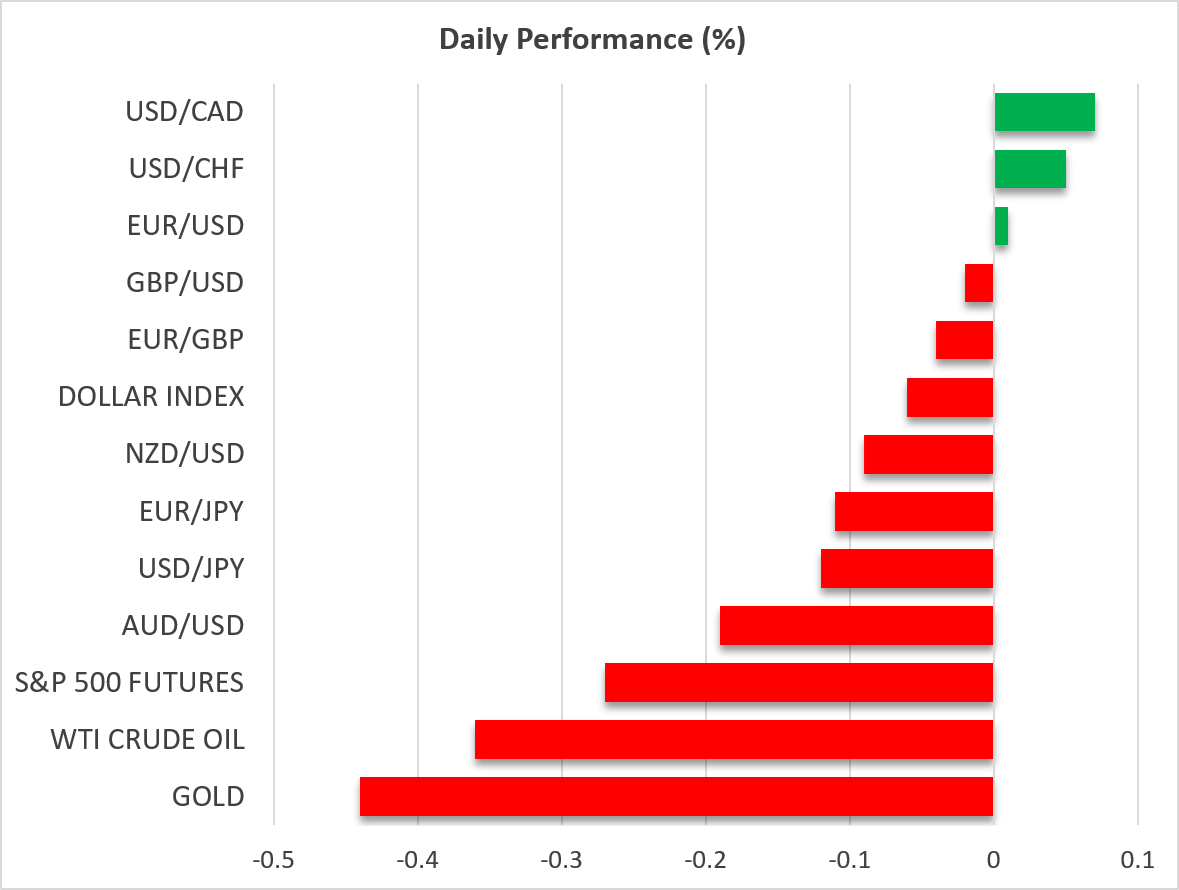
Boosted by higher Fed hike bets, rising US Treasury yields and concerns about an escalation in the Middle East, the US dollar managed to outperform every major currency last week, posting solid gains across the board. The most impressive move was the 2.2% weekly gain against the Swiss franc – the strongest weekly rally since June 2022 – while dollar/yen, after a period of range-trading, retested the 160 level.
The dollar started the week on the front foot, although the yen is setting today’s pace, benefiting from BoJ Takata’s hawkish commentary. Importantly, euro/dollar dropped to the lowest level since early April 2025, when Trump’s reciprocal tariffs shocked markets.
Finally, gold and bitcoin continue to suffer from the persistent dollar strength, highlighting their correlation with the greenback. Without a reversal or easing in Fed hike bets and/or another decline in oil prices that eases inflation concerns, it will be difficult for gold to meaningfully rally in the short-term. A climb towards the $4,000 level remains the first target for gold bulls.
Interestingly, following a relentless sell-off, selling pressure in the cryptocurrency market appears to have paused, with bitcoin rising above $64k. In addition to the factors mentioned above, analysts are also highlighting the possibility of crypto holders shifting their exposure to the Anthropic IPO. Potentially, after Thursday’s stock debut, some funds might circle back to the crypto market.
Technical Analysis – GBPUSD rebounds from one-month lows after five-day slide
Tech Tremors and Hawkish Fed Pressures Trigger Broad Risk-Off Reset
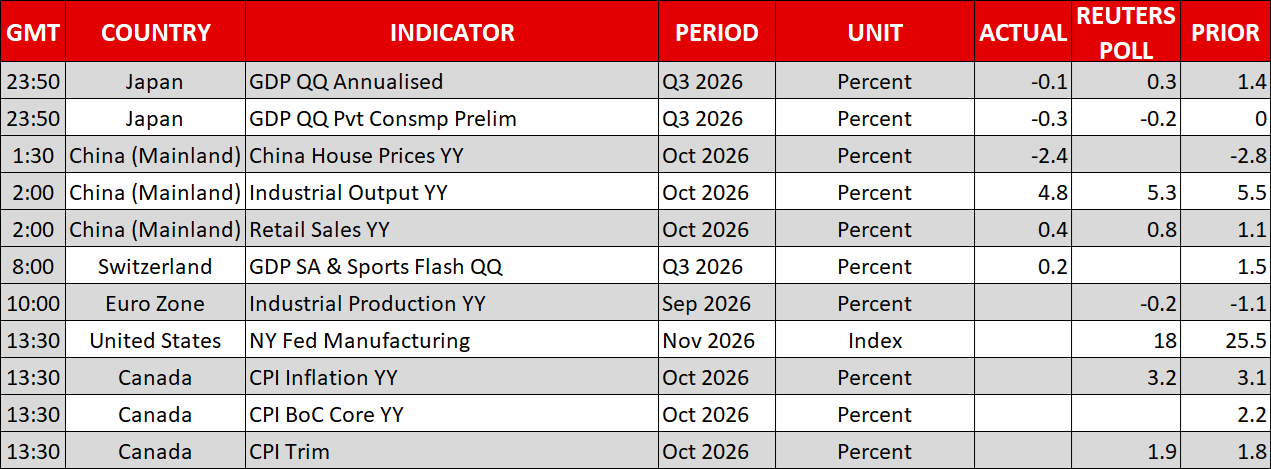
EBC Markets Briefing | Yen moves sideways after unexpected GDP contraction
Daily Fundamental Analysis: stock indices trade lower as Nvidia continues to weigh on market sentiment
Yen Intervention Risk Builds as Dollar Momentum Cools and Precious Metals Attempt to Stabilize | 17th November, 2026
Dollar Index Hits 19-Month High as Demand for Dollar Strengthens
Wall Street Slides as AI Fears Hit Nvidia and Chip Stocks Ahead of Earnings