-21420261153.png)
-21420261153.png)





Dollar Holds Near 18-Month High as Oil Rises and US Stocks Close Mixed

Market Wrap-Up: Dollar Strength and Higher Oil Prices Keep Markets Cautious
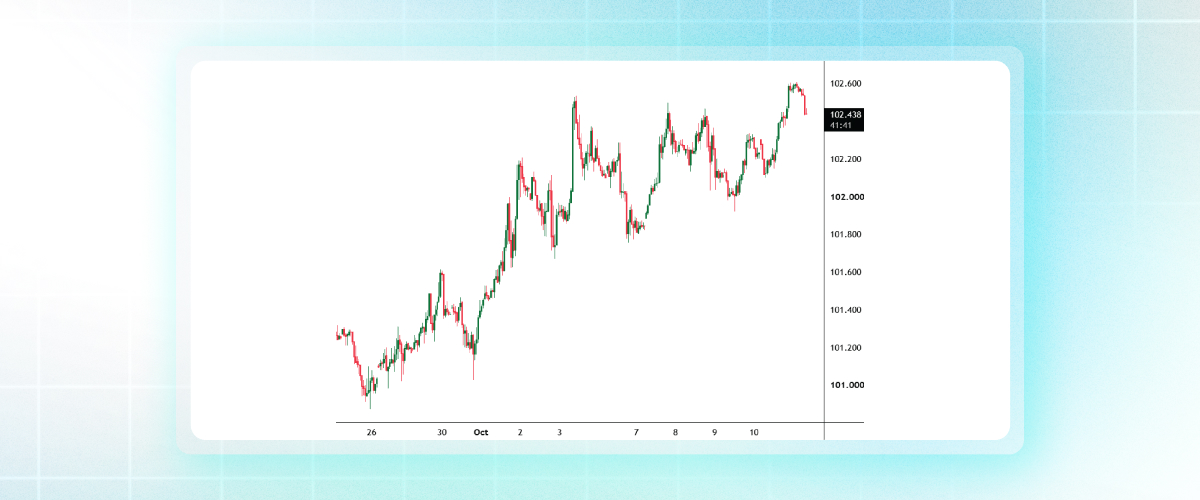
The US dollar held near an 18-month high on Monday as escalating tensions in the Middle East supported demand for safe-haven assets. The US Dollar Index (DXY) rose 0.37% to 102.58, its highest level since April 2025, while attacks on Saudi Arabia and commercial shipping added to concerns over regional oil supplies.
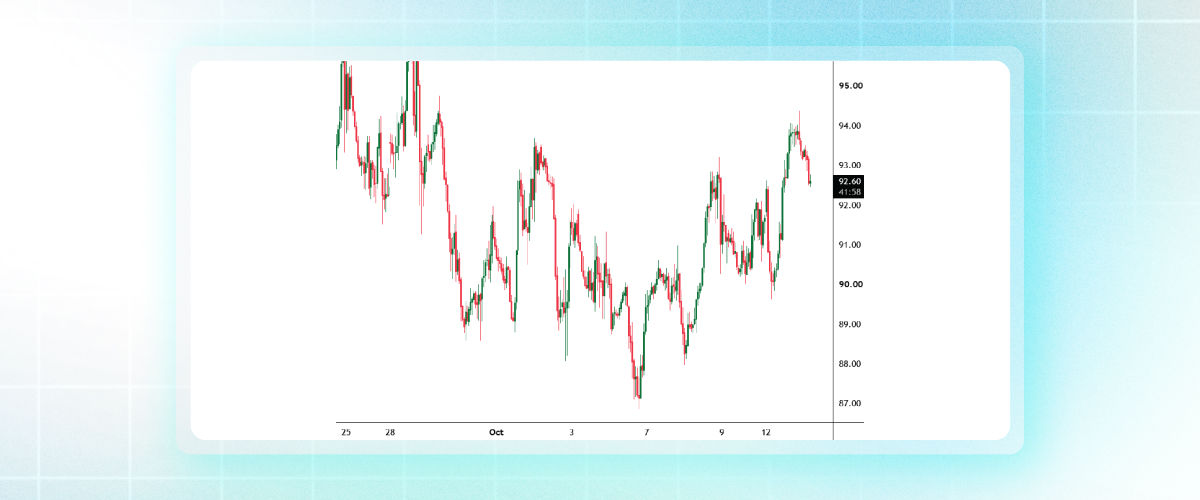
Brent crude futures settled up $1.93, or 1.8%, at $106.65 a barrel, while US West Texas Intermediate (WTI) crude rose $1.89, or 2%, to $93.74. The gains followed attacks on Riyadh's international airport and further reported incidents involving tankers near Oman and the Strait of Hormuz. These developments overshadowed the prospect of additional diesel supplies from Russia and an announced Russia-Ukraine ceasefire covering energy infrastructure, which Ukraine accused Russia of violating.
In the foreign exchange market, the euro fell 0.4% to $1.1156, near a 17-month low, amid concerns over France's fiscal outlook ahead of its 2027 presidential election. The US dollar gained 0.2% against the Japanese yen to 158.66, while sterling slipped 0.2% to $1.3203.
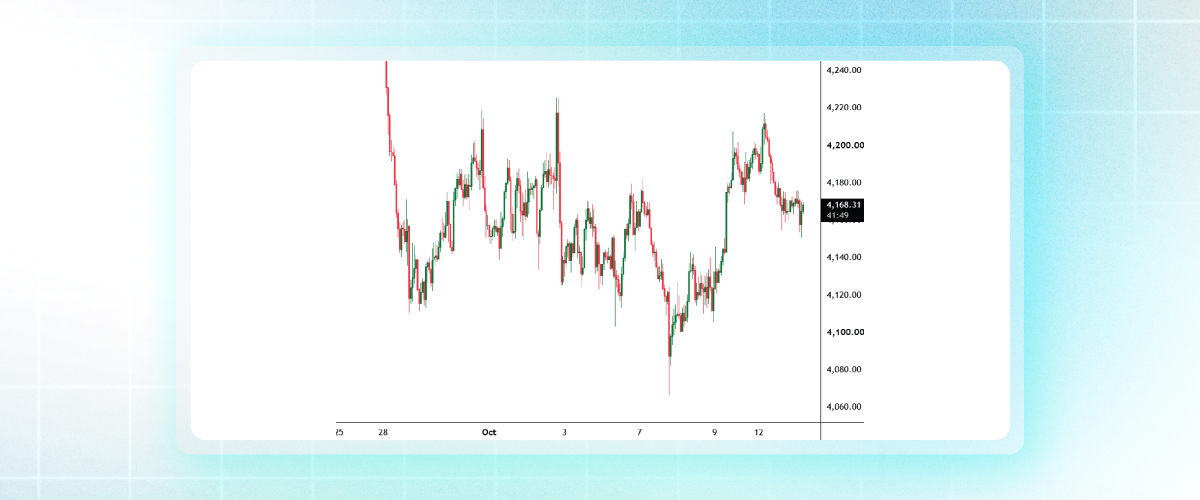
Gold prices eased as a stronger dollar and higher oil prices weighed on the metal ahead of US inflation data. Spot gold fell 0.6% to $4,169.10 an ounce after reaching a one-week high earlier in the session. US gold futures for December delivery also settled 0.6% lower at $4,190.60 an ounce. Investors are assessing whether upcoming inflation figures could influence the Federal Reserve's policy outlook, with markets largely expecting interest rates to remain unchanged later this month.
US equities closed mixed as rising oil prices, elevated bond yields, and upcoming economic releases weighed on sentiment. The Dow Jones Industrial Average gained 0.38% to 51,850.55, while the S&P 500 slipped 0.06% to 7,807.24 and the Nasdaq Composite fell 0.44% to 27,245.90. Energy shares outperformed, while technology stocks declined, with the Philadelphia Semiconductor Index falling 2.7%.
Cleveland Fed President Beth Hammack said the central bank should move relatively quickly to tighten monetary policy in response to increasingly broad-based inflation pressures. According to the CME FedWatch Tool, traders were pricing in an almost 22% probability of a rate increase this month, up from 17.7% on Friday.
Investor attention now turns to Wednesday's US Consumer Price Index (CPI) report, followed by Thursday's Producer Price Index (PPI) and retail sales data. Major US banks, including JPMorgan Chase, Citigroup, and Goldman Sachs, are also due to report earnings on Tuesday, marking the start of the third-quarter reporting season. The results and incoming economic data could provide further insight into the outlook for corporate performance, inflation, and monetary policy.
DXY
Key Takeaways
· Geopolitical uncertainty and persistent inflation concerns remain supportive of the dollar, while the potential for further Fed tightening remains a key consideration for currency markets.
· The upcoming US CPI report could influence interest-rate expectations and determine whether the dollar can sustain its recent strength.
Technical Outlook
· Daily Bias: Bullish
· Support: 102.10
· Resistance: 102.60
XAU/USD
Key Takeaways
· The combination of elevated oil prices and inflation concerns may reinforce expectations for tighter monetary policy, creating a challenge for non-yielding gold.
· The dollar's direction and incoming US inflation data remain key factors in assessing gold's near-term price action.
Technical Outlook
· Daily Bias: Bearish
· Support: 4,150
· Resistance: 4,217
WTI
Key Takeaways
· Risks to Middle East supply routes and infrastructure continue to underpin crude prices, with further tanker incidents potentially threatening the recovery in regional exports.
· Additional Russian diesel supplies offer a countervailing supply factor, leaving prices sensitive to developments affecting both export flows and the security of energy infrastructure.
Technical Outlook
· Daily Bias: Bullish
· Support: 89.63
· Resistance: 94.38
Calendar Watch
· US: ADP Employment Change Weekly. Markets will assess the latest employment signals for indications of changes in labour-market momentum. Any evidence of weakening or persistent labour demand could influence expectations for the Fed's policy path.
· US: Existing Home Sales. The data will offer insight into housing-market demand and the effect of borrowing costs on activity, helping investors assess the broader resilience of the US economy.
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as Forex and CFDs involves a high level of risk and may not be suitable for all investors. You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.

Gold Edges Higher as Dollar Weakens Ahead of US Midterm Results
US Midterm Elections Loom as Dollar Hovers Near One-Month Low
Gold Steadies Near $3,943 as Falling Oil Eases Inflation Fears
Markets Await United States Midterms as Dollar Holds Steady and Oil Falls
Week Ahead: RBA, BoE and US Jobs Data Put AUDUSD, GBPUSD and Gold in Focus
US Inflation Heats Up, Strengthening December Rate Hike Bets
Federal Reserve Holds Rates, Leaving Policy Outlook Unclear