-21420261153.png)
-21420261153.png)





Dollar Steady as Yen Gains Ahead of US Payrolls Report

A sharp US equity sell-off sends investors towards safe-haven assets ahead of the October US non-farm payrolls report, while recovering oil supplies and weaker demand point to a potential global surplus.
Market Wrap-Up: Equity Sell-Off Supports Haven Assets as Oil Supply Recovers
The US dollar (USD) held broadly steady against major currencies on Friday, 6 November, while the Japanese yen strengthened as a sharp sell-off in US equities prompted investors to seek safety in government bonds and haven currencies. Markets also turned their attention to the US non-farm payrolls report, due later on Friday, for further clues about the future direction of monetary policy from the Federal Reserve (Fed).
US equities fell sharply on Thursday following the Democratic sweep in Congress, amid concerns over tighter scrutiny of the artificial intelligence (AI) industry, particularly data centre construction. The Nasdaq Composite recorded its steepest one-day decline since "Liberation Day" in April 2025.
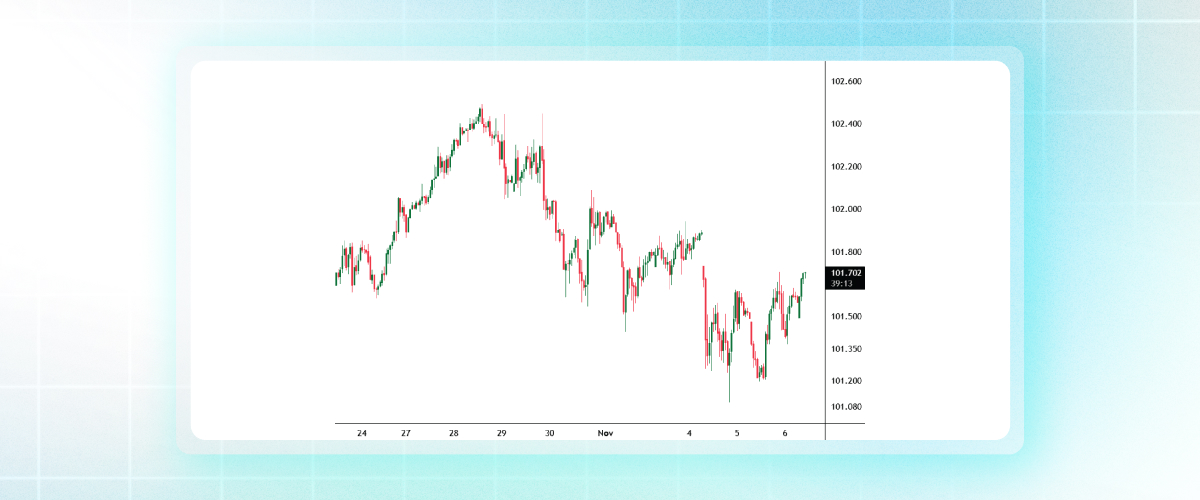
In foreign exchange markets, the yen initially gained 0.2% to a one-week high of 157.40 against the USD before surrendering some of its gains. The Swiss franc also advanced 0.2%, while the USD Index (DXY) remained broadly unchanged at 101.55. The euro held steady at USD 1.1222, leaving it on course for a 0.5% weekly gain and potentially ending a two-week losing streak. Sterling edged 0.1% higher to USD 1.3457 following the Bank of England's latest monetary policy decision.
US Treasury yields moved lower amid demand for government bonds and a reassessment of interest-rate expectations. The 10-year Treasury yield stood at 4.84% during Asian trading, near its lowest level since 10 September. Meanwhile, the two-year yield fell approximately 10 basis points overnight to 4.47%. Fed funds futures pricing also reflected a shift in expectations for the Fed's December decision, with the implied probability of a 25-basis-point move falling to around 70%, from more than 80% on Wednesday.
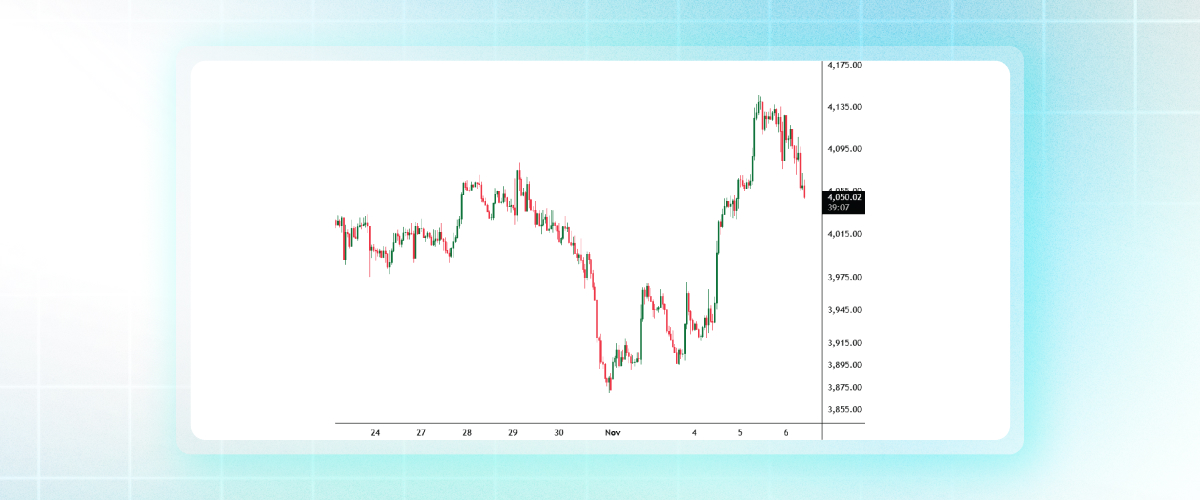
Gold extended its recovery to a more than two-week high on Thursday, supported by a softer USD and lower Treasury yields during the session. Spot gold rose 1% to USD 4,100.27 an ounce after touching an intraday high of USD 4,146.63, its highest level since 20 October. The latest advance followed a nearly 3.4% gain on Wednesday, marking gold's strongest daily increase since 19 August. Prices had also climbed more than USD 250 from a one-year low of USD 3,869.85 recorded on Friday, 30 October.
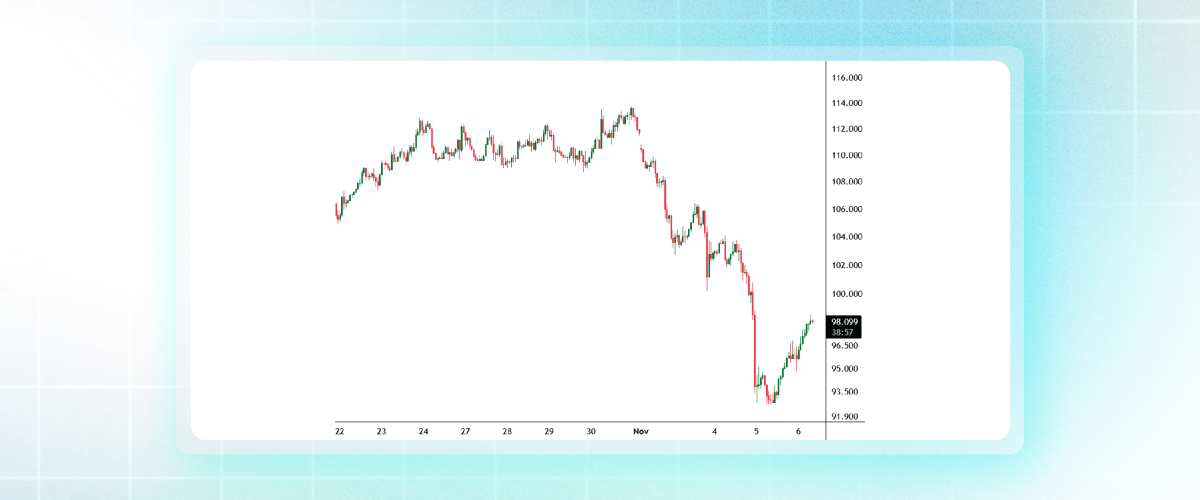
The global oil market is showing increasing signs of returning to a supply surplus, despite continued disruption to Middle Eastern exports from the Iran war. Higher prices have weighed on demand, while recovering regional supplies and increased production elsewhere have helped narrow the market deficit.
JPMorgan estimated that the global oil market returned to a surplus of 1.1 million barrels per day (bpd) in September, widening to 1.4 million bpd in October. Goldman Sachs, meanwhile, estimated that global oil stocks did not decline between September and October, suggesting that the market had become broadly balanced compared with the deficit recorded in March.
However, signals from oil futures markets remain mixed. Brent swaps have moved into contango, with contracts for immediate delivery trading at a discount to those for the following week, indicating more ample near-term physical supply. By contrast, Brent futures beginning with January 2027 delivery remain in backwardation, indicating that the futures market continues to reflect tighter near-term supply conditions.
Investor attention now turns to Friday's US non-farm payrolls report, which could provide further insight into labour-market conditions and the Fed's policy trajectory. Recent US data showed initial jobless claims falling by 6,000 to a seasonally adjusted 189,000, matching the lowest level recorded in July and coming in below the 196,000 forecast in a Reuters poll of economists.
DXY
Key Takeaways
· Falling US yields are limiting the dollar's appeal relative to traditional safe-haven currencies.
· The divergence in haven demand between the dollar and yen highlights the impact of US-specific market volatility.
Technical Outlook
· Daily Bias: Bullish
· Support: 101.19
· Resistance: 101.94
Gold / US Dollar (XAU/USD)
Key Takeaways
· Lower Treasury yields are improving the appeal of non-yielding gold.
· The prospect of a stronger US employment reading presents a potential challenge to gold's recent recovery through its implications for rate expectations.
Technical Outlook
· Daily Bias: Bearish
· Support: 4,014
· Resistance: 4,127
Brent Contract for Difference (CFD)
Key Takeaways
· Recovering Middle Eastern exports and rising production outside the Gulf are reshaping the global supply outlook.
· The emergence of contango in Brent swaps points to easing immediate supply tightness, despite continued backwardation in longer-dated futures.
Technical Outlook
· Daily Bias: Bearish
· Support: 92.68
· Resistance: 104.11
Calendar Watch
· Non-Farm Payrolls: The key labour-market release of the week, providing insight into employment conditions and helping markets assess the Fed's future interest-rate decisions.
· Unemployment Rate: Markets will assess whether the unemployment rate points to further labour-market weakness or continued resilience, offering additional insight into employment conditions.
· Average Hourly Earnings: Wage growth will be closely watched for signs of inflationary pressure, helping investors assess whether labour costs could influence the Fed's monetary policy.
· Fed's Musalem Speech: Investors will look for clues about the Fed's assessment of economic conditions, inflation risks, and the future direction of interest rates.
· Michigan Consumer Sentiment (Preliminary): The survey will provide an early indication of household confidence and inflation expectations, offering insight into consumer spending prospects and the broader economic outlook.
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as foreign exchange (forex) and contracts for difference (CFDs) involves a high level of risk and may not be suitable for all investors. You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.

Democratic Sweep Weakens the US Dollar and Lifts Precious Metals | 5th November, 2026

Democrats' Midterm Victory Sends Dollar and Oil Lower
What the Democratic Midterm Win Means for Gold, US Stocks and Bitcoin

Gold Edges Higher as Dollar Weakens Ahead of US Midterm Results
US Midterm Elections Loom as Dollar Hovers Near One-Month Low
Gold Steadies Near $3,943 as Falling Oil Eases Inflation Fears
Markets Await United States Midterms as Dollar Holds Steady and Oil Falls