

Dollar strengthens as risk appetite weakens

Challenging September, eventful October
The busy data calendar, fluctuating oil prices, elevated bond yields and hawkish central bank meetings resulted in a challenging September for risk assets. Most major stock indices finished the month in negative territory – the Dow Jones 30 index fell by 4.3%, its weakest month since March 2026 – with only the Nasdaq 100 index bucking the trend and climbing by a decent 3.2% due to the AI euphoria.
Notably, the cryptocurrency market posted solid gains in September, but these were well below the impressive August performance. With bitcoin completing three consecutive positive months for the first time since mid-2025, crypto bulls are warming up to the fact that we might be at the start of another long-term bullish trend.
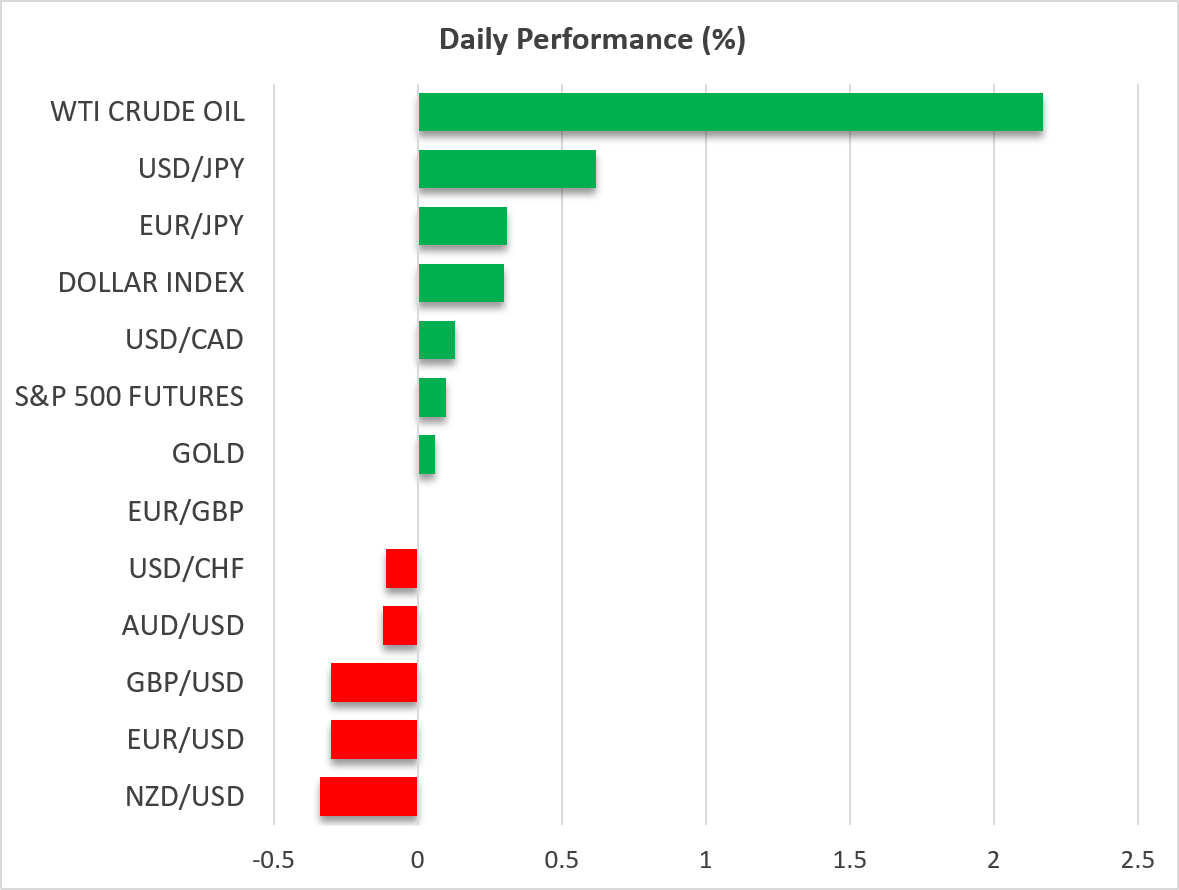
Meanwhile, the US dollar dominated FX markets with a solid 2% rally in the dollar index. Interestingly, euro/dollar dropped by 2.5%, the strongest monthly decline since July 2025 when strong US data and the US-EU trade agreement boosted the greenback, while the antipodeans also suffered considerably in September.
October commences with most issues unresolved. The key driver of market movements, oil, has dropped to a three-week low, erasing the mid-September advance that played a key role in pushing the Fed into hiking on September 16. That said, there has been very little progress in the US-Iran talks despite mediation from various Middle Eastern countries like Qatar.
US President Trump’s rhetoric is obviously not helping the negotiations, as he repeated overnight that there will be developments on Iran “very soon”. This has been interpreted by some analysts as a signal for fresh military operations, which, if confirmed, are bound to push oil prices aggressively higher, boost the dollar and keep risk assets under pressure.
October Fed hike bets have been dropping
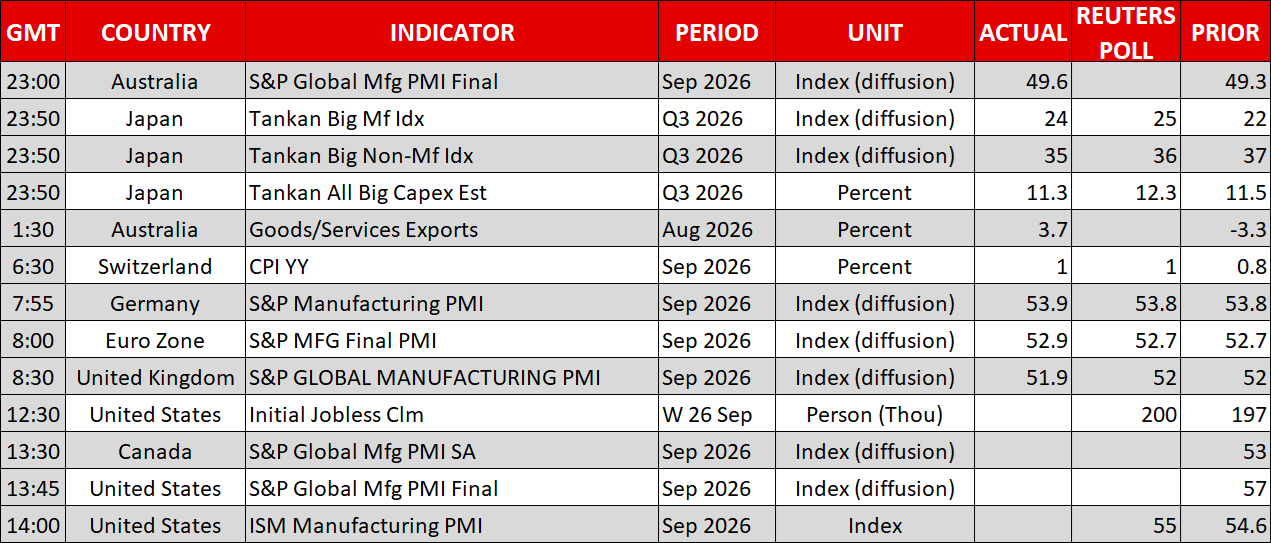
Another oil price surge would clearly boost October Fed rate hike bets, which have been dropping aggressively as oil prices slip and US data soften. Following Tuesday’s weak CB Consumer Confidence Index and Wednesday’s softer PCE report, and despite the upwardly revised Q2 GDP print and the upside surprise in the ADP employment report, the chances of a 25bps October hike have dropped to just 36% from 80% on September 28. The next key data release is today’s ISM Manufacturing PMI, with extra focus on the elevated prices paid subindex.
Notably, Fedspeak has been quite hawkish so far, with members almost unanimously expressing their support for another rate hike. Timing is obviously key, as the Fed hawks push for at least one additional move before year-end, which is what the market currently prices in. Interestingly, at least nine Fed speakers will be on the wires today, with the focus being on the ultra-doves and more specifically Board members Jefferson and Bowman. Could this week’s softer US data motivate the Fed doves to become more vocal and start erecting barriers to the increasingly hawkish expectations?
Yen weakens, gold’s selloff pauses at $4,110
The unsurprisingly hawkish Summary of Opinions from the September BoJ meeting and the solid Q3 Tankan report did not help the yen today. After finding strong support at the 156.74 level, dollar/yen is climbing again towards the 158.5 area. The focus now shifts to tomorrow’s Tokyo inflation report for September.
A significant acceleration is expected, which, if confirmed, would push the CPI index excluding fresh food to 2.4%, the highest level since November 2025. Such an outcome could boost BoJ rate hike bets, as markets are currently assigning an 85% probability to a December rate hike
Finally, gold has bounced off $4,110 despite dollar strength and US Treasury bond yields reaching 5.3%. The weaker risk appetite and lower Fed rate hike bets have assisted gold, but the short-term trend remains bearish. A retest of the $4,000 level remains on the cards, especially if tomorrow’s nonfarm payrolls report surprises on the upside.
Today Technical Analysis: Gold prices rebound as the precious metal nears $4,200 level
US Data Revisions: A Brighter Inflation Picture, but Underlying Pressures Persist
USDJPY recovery eyes key SMA resistance band
Today Fundamental Analysis: Nasdaq surges to a new record high following PCE inflation data
The euro has slipped out of its range
Crypto: calm before the storm?
September Market Review: Fed Rate Hike, AI Momentum and October Outlook