






Major oil producers agree to supply cuts

OVERNIGHT
Equities across Asia were mostly trading higher at the start of the new week, helped by better-than-expected news from China’s services sector. The Caixin services PMI for May jumped to 57.1 from 56.4 in April, easing some concern over the health of the world’s second largest economy. Oil prices rose in response to the OPEC+ announcement that supply cuts would be extended until end-2024. Saudi Arabia also agreed to cut oil supply by an extra 1m barrel-a-day in July.
THE DAY AHEAD
While the US debt-ceiling deal has averted the possibility of a US default for now, thus removing a near-term uncertainty for the US economy and financial markets, greater focus is now likely to be on the interest rate outlook. Expectations of how close interest rates across the major economies – including in the US, Eurozone and UK – are to a peak continue to fluctuate. Markets now face a nervous wait ahead of the next set of monetary policy updates from the US Fed and ECB on the 14th and 15th respectively, with the Bank of England’s next decision due on the 22nd. For the US, in particular, Friday’s mixed US labour market report, with a stronger than expected rise in jobs growth as reported in the establishment payrolls survey was accompanied by a 0.3%point rise in the unemployment rate in the households survey as well as a slight moderation in the rate of annual pay growth, has only added to the uncertainty around the US interest rate outlook.
With the Federal Reserve members now in their pre-meeting ‘quiet period’ ahead of the June announcement, there are no Fed speakers scheduled for today. Moreover, the calendar is also bereft of any central bank updates from either Bank of England or European Central Bank (ECB) speakers. As a result, today’s calendar is limited to a number of business activity surveys, mostly for the services sector.
In the UK, the May services PMI measure is a second reading that is not expected to be revised from the ‘flash estimate. The initial print showed service sector activity continue to expand and also pointed to ongoing concerns about the impact of a tight labour market. In the US, the services ISM reading for May will provide another timely update of what is happening to activity ahead of the Fed’s policy announcement. It showed growth still running at a solid pace in April, albeit slower than in the first couple of months of the year. In the Eurozone, the second reading for the aggregate services PMI is expected to remain well above the 50 mark, consistent with a solid expansion in activity in May.
Overnight, and early tomorrow morning, the British Retail Consortium (BRC) will release its report on UK retail activity for May. Meanwhile, the Reserve Bank of Australia will deliver its latest policy decision. Following May’s surprise 25bp hike, expectations are for the central bank to keep rates at 3.85%, albeit markets see it is a close call with some economists forecasting another 25bp increase.
MARKETS
US bond yields have extended gains made on Friday, supporting a further rise in the US dollar. GBP/USD has fallen further below 1.25, while the pound has also slipped against the euro but the pair is still holding close to its high for the year.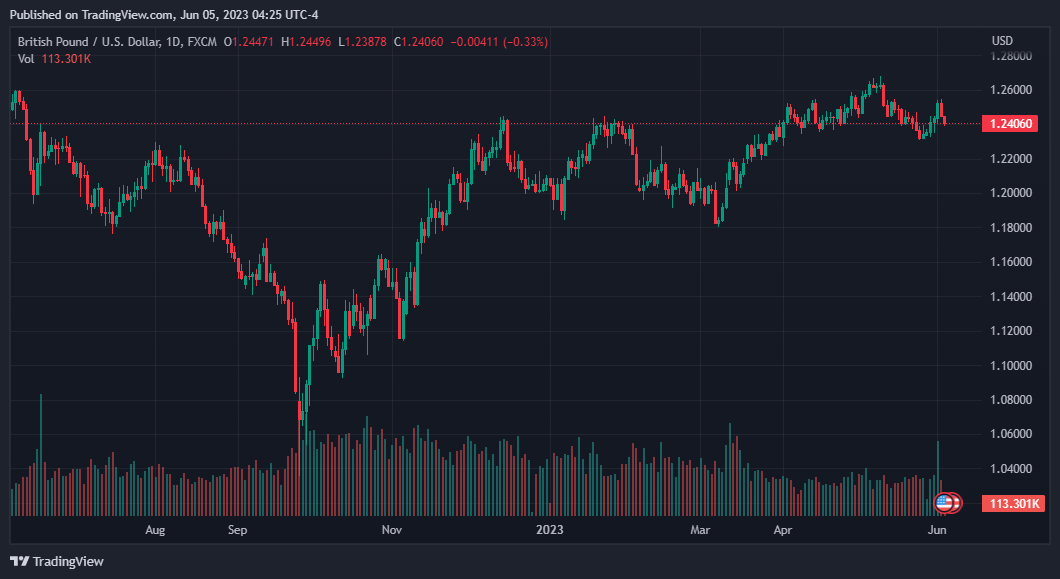


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






