Markets struggle for directions ahead of Jackson Hole

Investors digest US data and Nvidia results
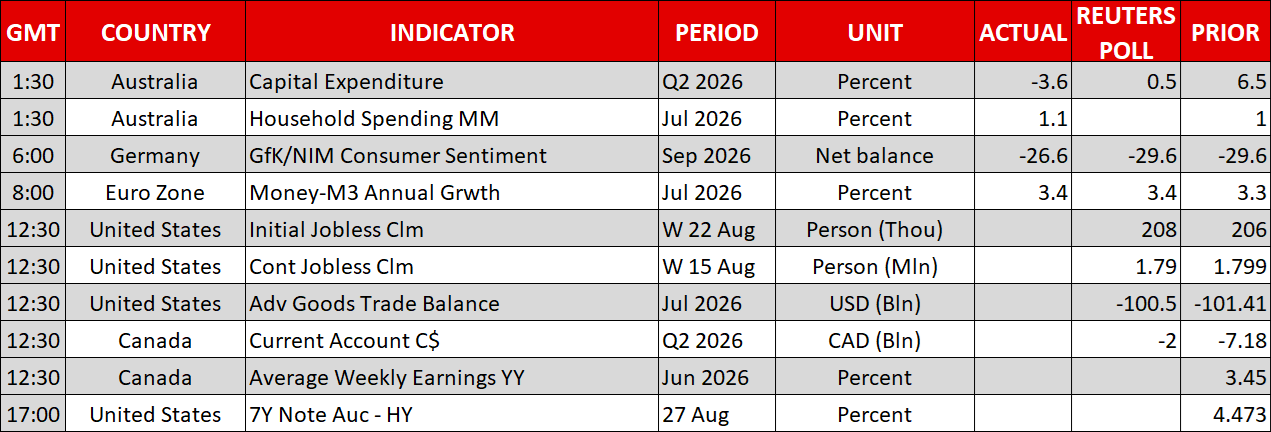
Wednesday’s key events proved market-moving but fell short of expectations for significant asset movements. PCE inflation in July failed to decelerate meaningfully enough to considerably dent the already low chances of a September Fed rate hike, while personal spending eased further and the final Q2 GDP report confirmed expectations.
More importantly, Nvidia earnings beat forecasts for both EPS and revenue. The initial reaction was negative though, courtesy of the extraordinary earnings expectations and as investors potentially responded to the lower Q3 adjusted gross margin, but this stock decline did not last.
Surprisingly, Nvidia’s management announced specific guidance numbers for next year, particularly fiscal 2028 revenue growth of 70%, which turned momentum around, with its stock in the green at the time of writing. While investors crave detailed forward guidance, one could infer a degree of anxiety from Nvidia officials seeking to keep investors happy.
Weak risk appetite
Risk appetite got a bit of a boost overnight, but conviction remains low, with the Nasdaq 100 index lacking the momentum to climb towards the mid-August peak. There are still lingering concerns about a plethora of issues preventing investors from becoming aggressively bullish in risk assets. Specifically, the Middle East remains a headache for market participants, as the negotiations between Oman and Iran continue, but this ongoing process has yet to yield concrete results.
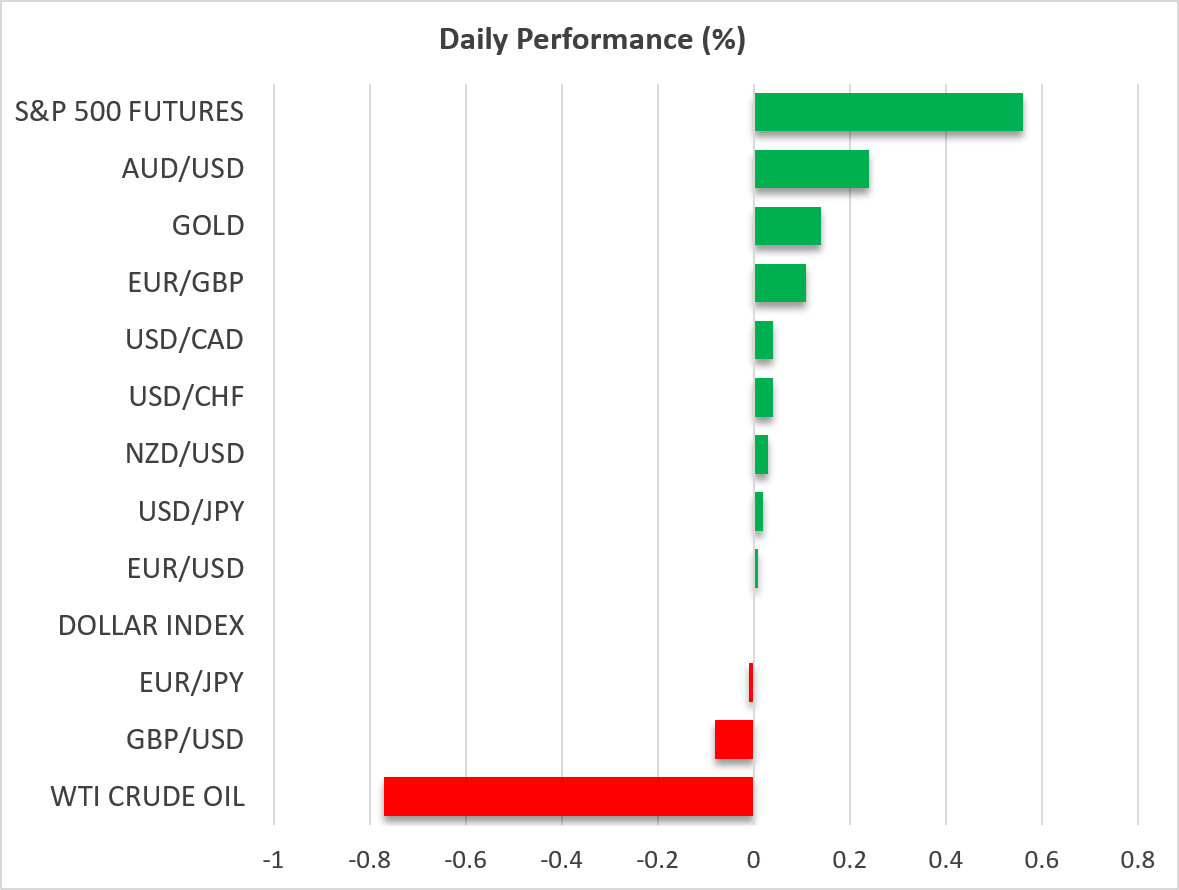
Oil prices appear to have stabilized, with spot WTI oil trading north of $82, around 8% below last week’s peak. Meanwhile, a meeting between US officials and Russian President Putin in Moscow did not break the deadlock, with reports from US media pointing to another escalation in this conflict. This is somewhat unexpected considering that incoming winter tends to stop any meaningful gains on the battlefield from either side, but oil investors are clearly attentive to such headlines.
Dollar maintains weekly gains
The US dollar remains in the green this week, posting muted gains across the FX spectrum, with the stark exception of the aussie, where investment houses have turned more hawkish, anticipating another RBA rate hike during 2026.
Considering today’s very light US data calendar, with the 7-year Treasury auction most likely failing to prove market-moving, FX traders have shifted their focus to Friday’s Jackson Hole Symposium. Speculation is rife over whether Fed Chair Warsh will comment on inflation and monetary policy, or whether he will opt to reduce the importance of the event.
Interestingly, the host of the Jackson Hole Symposium, Kansas City Fed President Schmid, is scheduled to speak today. He is expected to repeat his usual hawkish rhetoric, potentially annoying Warsh just a few hours ahead of his Jackson Hole appearance, but he is a non-voter this year and in 2027.
Euro/dollar has been edging lower this week but is trading within a very tight range. The next key support level is the 200-day simple moving average (SMA) at 1.1628, with the 1.1693 level capping the upside at the moment. The ECB minutes from the July 23 meeting will be released today, but, pending a major surprise that is very uncommon with this release, the current market expectations for a September rate hike will remain firmly supported.
Dollar/yen stabilizes
Dollar/yen has been gliding higher this week but has failed so far to test last week’s peak. Following yesterday’s upside surprise in the July Corporate Service Price index, the next key data release is tomorrow's Tokyo CPI report for August. Confirmation of the forecast deceleration in the core indicator to 1.7% would be a negative sign for the chances of a September rate hike.
Overnight, BoJ Deputy Governor Himino was relatively hawkish, stressing the need for “timely rate hikes” to avoid falling behind the inflation curve, but obviously stopping short of signalling a September move. The yen hawks are not really reacting to Himino’s commentary, as they are already focusing on BoJ Governor Ueda’s decision to skip the Jackson Hole Symposium, avoid sending any of the Deputy BoJ Governors, and select board member Tamura – a solid hawk – to represent the BoJ.
There is strong speculation that Governor Ueda may attend the G20 finance ministers’ and central bankers’ gathering in North Carolina, USA, potentially meeting in private with US officials to coordinate future actions to strengthen the yen. But one could also assume that the BoJ is inching closer to a September rate hike – markets assign a 65% probability to such a move – and Ueda wanted to avoid tipping investors at the Jackson Hole, partly because the hike might not have been greenlighted yet by Japanese PM Takaichi.

Democratic sweep weighs on dollar and yields, lifts gold
What the Democratic Midterm Win Means for Gold, US Stocks and Bitcoin

US Midterms: Early Democratic Senate Wins Sink Dollar and Drag Futures Lower
EBC Markets Briefing | Aussie dollar propped up by US mid-term election uncertainty

Gold Edges Higher as Dollar Weakens Ahead of US Midterm Results
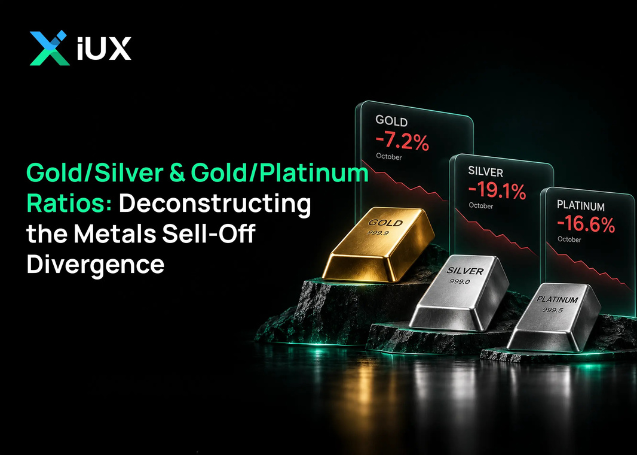
Gold/Silver & Gold/Platinum Ratios: Deconstructing the Metals Sell-Off Divergence
GBPUSD Edges Towards 1.3463 as Traders Brace for the Bank of England Decision