






Muted dollar and equity movements as investors face multiple headwinds

Investors face numerous challenges
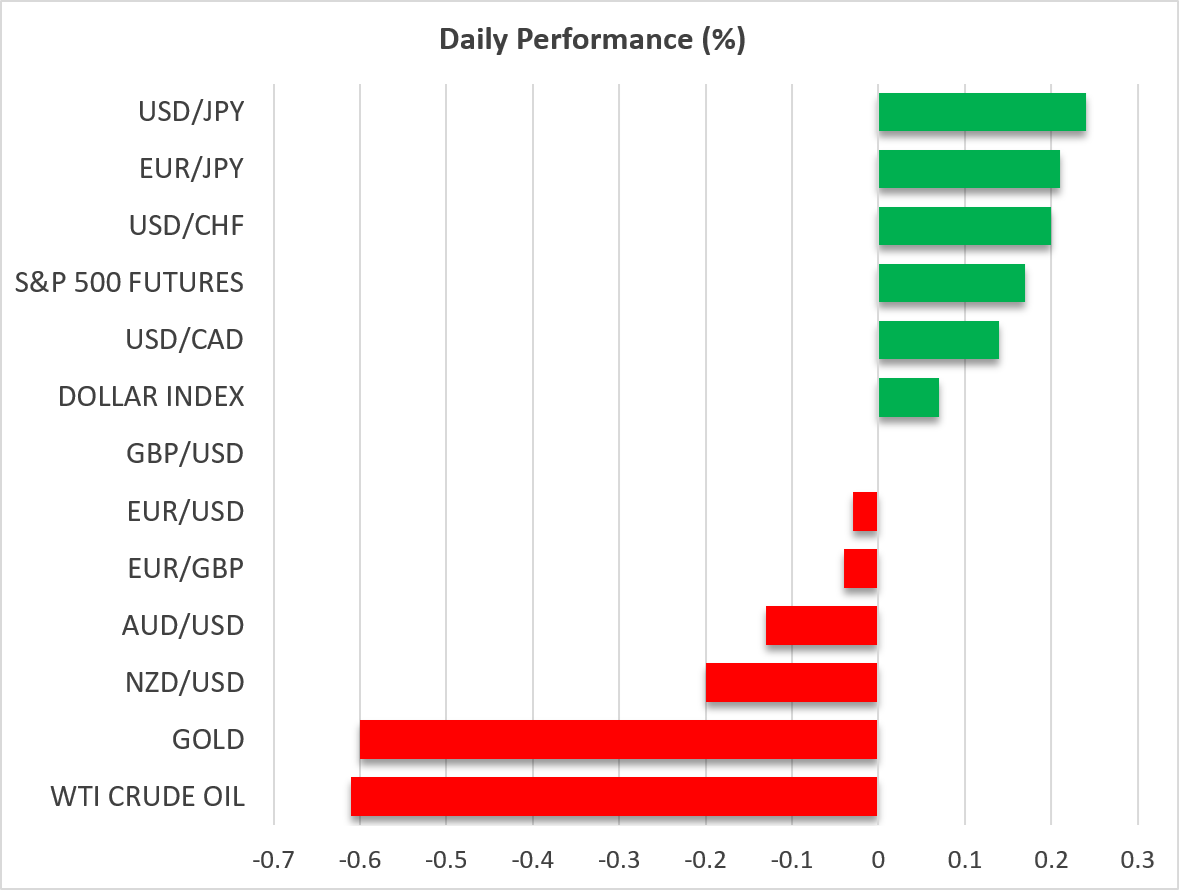
The US dollar has started the last full week of August slightly on the front foot. After trading at a fresh three-month high, at the time of writing, euro/dollar is trying to edge towards the 1.1627 level, near the middle of the June 2025-June 2026 wide trading range. At the same time, equity markets are not feeling comfortable with the current status quo ahead of Nvidia’s earnings announcement tomorrow (Wednesday) after US markets close.
The Middle East conflict and US debt concerns linger
Investors are facing a number of headwinds at this stage. The Middle East conflict remains in the spotlight. While oil is “quietly” flowing via the Strait of Hormuz, as the TotalEnergies CEO commented yesterday, there is no light at the end of the tunnel regarding the US-Iran negotiations. Despite much hype about an ”economic D-Day”, Treasury Secretary Bessent was mum about specific measures against countries and entities doing business with Iran. This continued war-like rhetoric could only mean that Western economies must prepare for lower oil and gas flows in the upcoming winter, with an obvious upward impact on energy prices.
Additionally, despite Treasury Secretary Bessent appearing relaxed about the US ability to fund its debt, last week’s Treasury buyback announcement revealed the US administration’s angst about rising bond yields. Instead of addressing the humongous budget deficit, worsened by US military spending and tariff-revenue shenanigans, Bessent is trying to control the bond market.
Tariffs and AI concerns also in the spotlight
Meanwhile, tariffs have returned to the forefront. Despite the summer Supreme Court decision against Trump’s tariffs and the subsequent return of billions of tariff revenue to firms, tariffs remain close to President Trump’s heart. The battle with Canada is raging, even though the January 1, 2027 deadline for the imposition of a 50% tariff on Canadian goods suggests that the US is willing to find a solution with its neighbour. Since Friday, when it became obvious that an agreement was not coming, the loonie is just 1% weaker against the dollar, reflecting optimism about a trade deal soon.
In the meantime, there are reports that the US is preparing to increase tariffs on Chinese goods by 7.5% to 20%, the maximum agreed level following last year’s understanding between the US and China. This will probably make the Trump-Xi meeting scheduled for September 24 in Washington, DC, even more interesting.
The efficacy and the signalling of such moves, with the justification being to support the US economy, have been diminishing as foreign governments and markets have decoded Trump’s battle plan. But is the US administration really interested in supporting the local economy or could the higher tariffs be a key negotiating tool to force countries like China to continue buying US debt?
Following a muted start to the new week, equity markets are trying to find their footing. Concerns about AI investment commitments, rising operating and funding costs, and, sometimes, extreme market valuations are lingering, with Nvidia’s earnings report being the key trigger event. A solid report might not be enough to keep investors happy, thus contributing to the current anxiety. Interestingly, money market fund holdings are rising exponentially, a worrying development that suggests muted interest from investors in joining the AI bandwagon.
Gold and bitcoin in demand, busy data calendar ahead
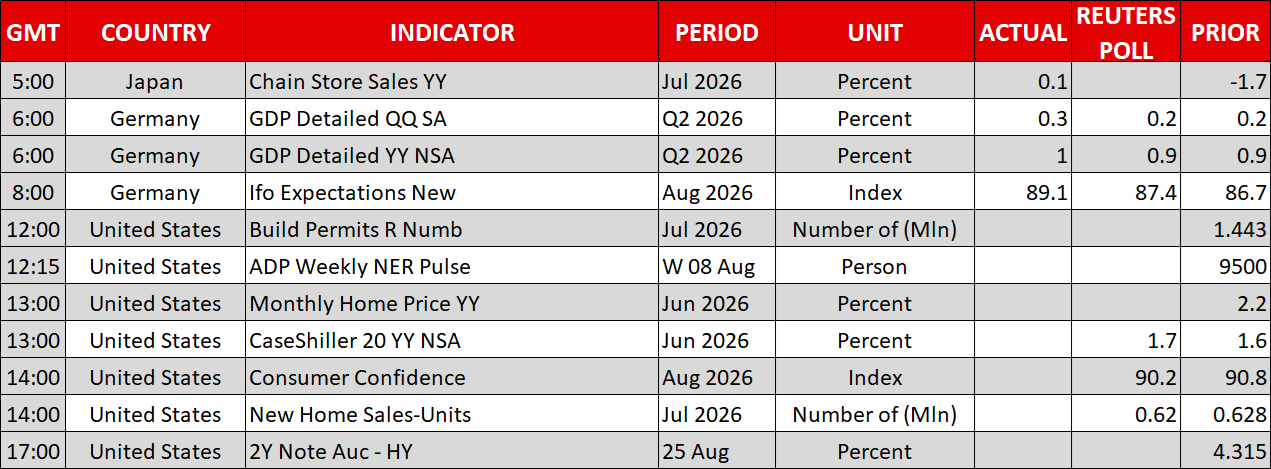
Gold and bitcoin continue to benefit from last week’s Treasury announcement, with the former posting a fresh three-month high overnight and the latter reaching the $80k level for the first time since mid-May. Dollar performance remains pivotal for both assets, with Wednesday’s PCE report and Friday’s speech by Fed Chair Warsh at the Jackson Hole Symposium potentially proving critical. That said, there is a relatively busy calendar today, with both housing data and the popular CB Consumer Confidence Index being released.
Finally, amidst muted moves in the FX market, the aussie is slightly gaining today following the somewhat hawkish RBA minutes. Unsurprisingly, the yen is under pressure as dollar/yen is flirting with 160 again. Friday’s Tokyo CPI report could transform current investor hopes for a September BoJ rate hike into credible market expectations.


US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026
EBC Markets Briefing | Euro remains structurally less secure than Swiss franc
The dollar concedes the Democrats’ victory
Democratic sweep weighs on dollar and yields, lifts gold
What the Democratic Midterm Win Means for Gold, US Stocks and Bitcoin

US Midterms: Early Democratic Senate Wins Sink Dollar and Drag Futures Lower
EBC Markets Briefing | Aussie dollar propped up by US mid-term election uncertainty






