

Stocks and dollar climb ahead of Fed, kiwi sinks on RBNZ shock

RBNZ kicks off rate decisions with a surprise
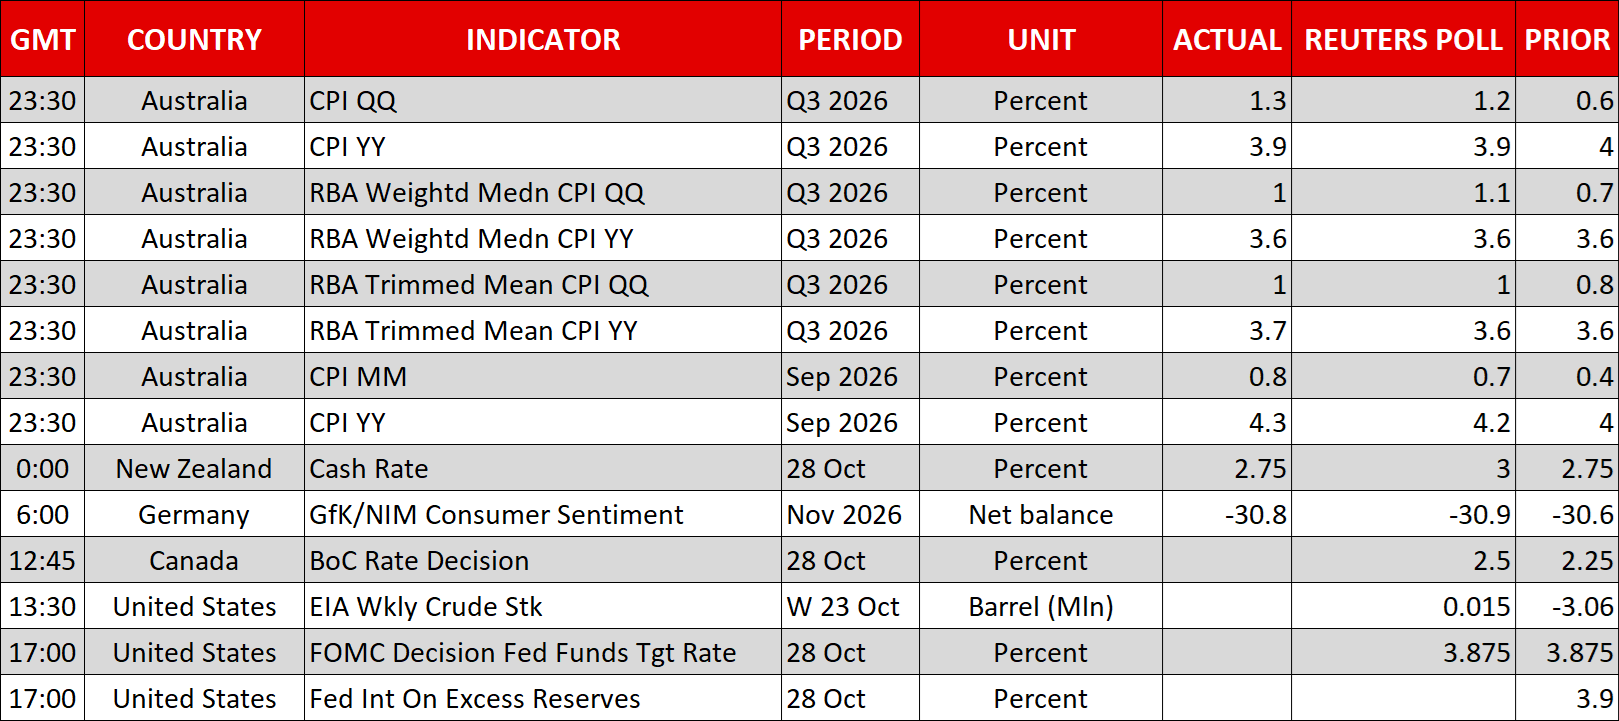
The Reserve Bank of New Zealand blindsided investors on Wednesday by unexpectedly holding interest rates steady after a tight vote. MPC members voted 4-3 to keep the official cash rate at 2.75%, defying market expectations of a 25-basis-point hike. It seems that the RBNZ wasn’t ready for a second back-to-back hike, following the increases in July and September, amid caution over the outlook. Last week’s soft CPI data and a general election in the country in ten days’ time likely influenced the decision too.
But Governor Anna Breman signalled that despite today’s pause, more tightening will be needed, especially if the New Zealand dollar remains on a downward trajectory, stoking inflationary pressures.
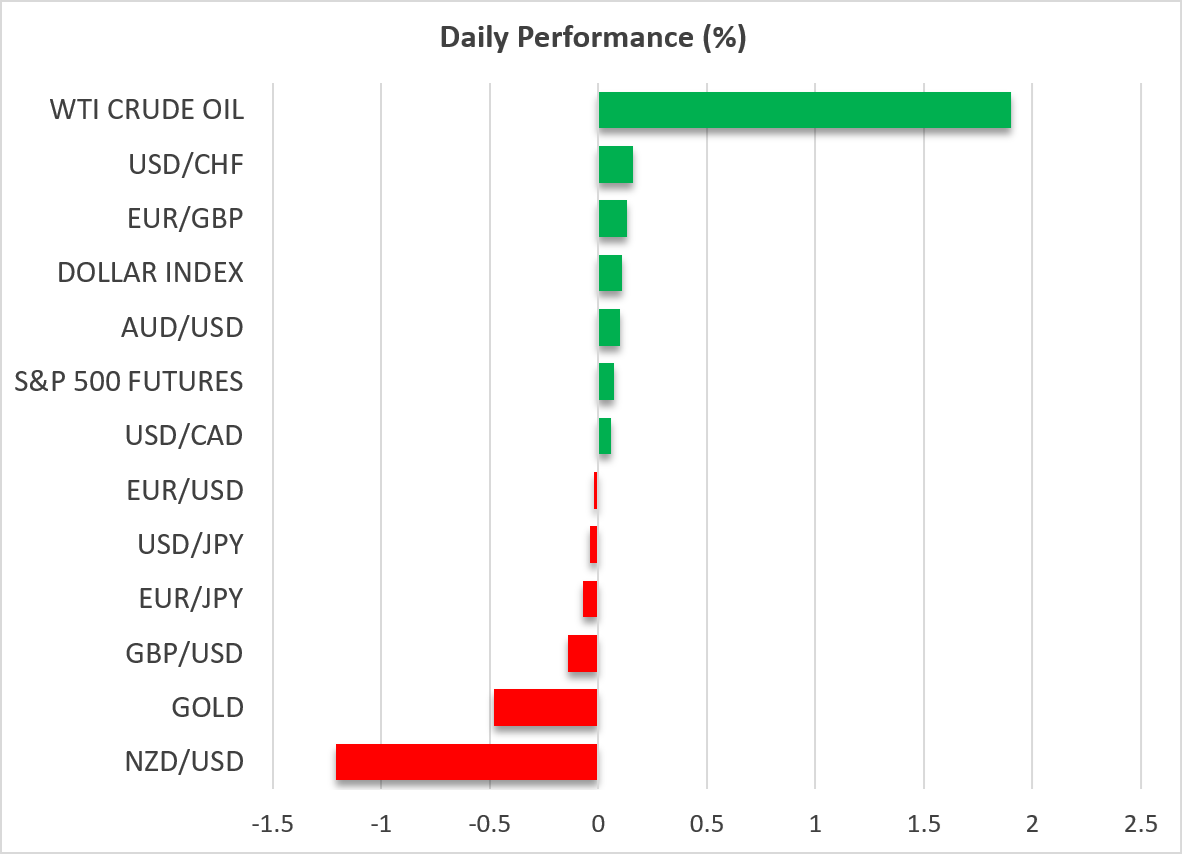
The kiwi, which had enjoyed a more than 2% rebound versus the greenback, sank by almost 1.8% after the decision, as a 25-bps hike was fully priced in. It’s since pared some of those losses to recover to just above $0.56, as Breman’s hawkish tone supported bets of further tightening over the next year.
BoC decision ahead, Fed unlikely to surprise
The Bank of Canada’s rate decision, due at 13:45 GMT, also carries some risks as a 25-bps increase is only about 76% priced in and recent Canadian data support the case for a wait-and-see stance.
Like the kiwi, the loonie’s latest rebound could falter if the BoC doesn’t hike or isn’t as hawkish as the Fed just a few hours later.
The Fed is the least likely to surprise markets out of all the central bank decisions this week. Markets fully priced out an October hike without pushing back the timing following a slew of dovish commentary from Fed officials right before the blackout period.
However, Fed Chair Kevin Warsh will likely keep rate hikes firmly on the table when he speaks at 18:30 GMT but without giving too much away. If Warsh maintains his optimism about the US growth outlook and isn’t too concerned about AI bubble risks or surging Treasury yields, markets will likely take that as a hawkish signal.
The US dollar is holding firm against most major currencies on Wednesday, though it’s slightly weaker against the Japanese currency, trading at 157.79 yen.
The Bank of Japan is also not anticipated to raise interest rates when it meets on Friday, but the yen may find support from upward revisions to the inflation forecasts.
Aussie supported by CPI data, pound slips ahead of budget
Elsewhere in the FX market, the Australian dollar was lifted by somewhat stronger-than-expect CPI figures out of Australia. Although the quarterly readings were largely in line, September’s headline rate accelerated more than expected to 4.3%, boosting the odds that the RBA will hike rates next week.
The aussie was last trading at $0.7032, while sterling was marginally lower at $1.3291.
UK Chancellor John Healy will unveil his first Autumn Budget at 12:30 GMT, amid pressure on the government’s finances by the surge in gilt yields and the energy shock. Healy will likely do his best to offer some relief to households and businesses from soaring inflation with the little wiggle room he has. But the pound may still come under pressure if markets sense a lack of commitment to reducing the budget deficit.
The budget announcement comes ahead of an expected rate hike by the Bank of England next week.
Chips rally ahead of hyperscaler earnings
Despite some uncertainty ahead of the crucial rate decisions, equities appear to be in a buoyant mood. Wall Street ended higher for a second straight session on Tuesday amid optimism around the upcoming IPO by AI giant, Anthropic, while shares in Asia rallied on Wednesday, led by a surge in SK Hynix.
The chipmaker reported triple digit annual growth in both revenue and earnings in the third quarter, maintaining its strong outlook for AI demand. The stock ended almost 11% higher, while Samsung jumped 9%.
US chipmakers also bounced higher on Tuesday, though the focus today will be on Big Tech earnings, as Microsoft and Google parent, Alphabet, report their Q3 results after Wall Street’s closing bell.
Any updates on capex spending, rising expenses and earnings guidance will be closely watched, as investors continue to punish stocks that they deem are becoming too risky from AI overspend, as seen with Meta. The Facebook and Instagram owner announced on Tuesday that it will issue new shares valued at $97.5 billion to help finance its AI investment, deepening Meta stock’s three-week rout.
US futures are mixed today.
Oil futures snap two-day slide
Rising oil prices are likely dampening some of the positive sentiment amid fresh tensions in the Middle East.
Houthi rebels said they carried out an attack on a major Saudi oil refinery on Tuesday, reviving worries about supply disruptions.
Meanwhile, the Wall Street Journal is reporting that American officials have warned Arab nations in the Gulf to prepare for a short but intense military campaign against Iran after the US midterm elections.
WTI oil futures are back above $100 a barrel today and Brent is back above $115, recouping some of this week’s losses.
EBC Markets Briefing | Wall St stunned by Brazil's status quo vote
Crypto recovers as Fed decision looms
Dollar Firms and Oil Rebounds Ahead of Fed Decision
FOMC Today, ECB Tomorrow — Will GOLD Break Above $4,160 or Fall Below $3,950?
EBC Markets Briefing | Chinese stocks at critical crossroads as earnings season unwinds
Fed Rate Decision in Focus as Currencies React to Inflation and Policy Divergence | 28th October, 2026
FOMC and Month-End: How FX Hedging Flows Can Move Currency Markets