






Yields push higher

OVERNIGHT
Equity markets were mostly lower in the Asia region as investors digested yesterday’s decision by the Bank of Canada to raise interest rates by 25bp to 4.75% after having paused in the prior two policy meetings. Most analysts expected no rate change. Earlier this week, Australia’s central bank also raised interest rates by 25bp to 4.10%. Economic data overnight showed a bigger than expected upward revision to Japan’s Q1 GDP growth to 2.7%q/q (annualised) from the prior estimate of 1.6%. Despite that, the Nikkei 225 index posted a second daily decline, reversing some of the sharp gains in recent weeks.
THE DAY AHEAD
The UK RICS residential market survey for May was released overnight. The results, based on the responses of chartered surveyors, show further signs of gradual recovery in activity and prices towards a more stable outlook. The net balance for prices rose to -30% from -39%, the highest since November, while new buyer enquiries were at a one-year high. However, RICS said that stubbornly high inflation and higher interest rates could reduce demand. There are no other significant UK releases until next week’s monthly labour market and GDP reports ahead of the following week’s inflation and the Bank of England policy update.
In the Eurozone, Q1 GDP growth is expected to be downgraded to flat (0.0%q/q) from the earlier estimate of 0.1%q/q. That follows the recent downward revision in German Q1 growth to 0.3%q/q compared with the previous estimate of 0.0%, and it suggests Europe’s largest economy did fall into a technical recession after all. Despite a German technical recession and Eurozone stagnation, the ECB is still likely to raise interest rates again next week to apply further downward pressure on inflation which remains too high.
US weekly jobless claims may provide further insights into the state of the labour market. Initial claims are forecast to have edged up to 235k in the latest week and overall seem to be offering evidence of some moderate softening of the labour market. Separately, this week’s May ISM services survey pointed to somewhat weaker output growth than forecast. Last Friday’s labour market report, however, was surprisingly strong in terms of jobs growth (+339k in May). Overall, though, the broad evidence may be enough for a Fed ‘pause’ in next week’s policy update, although another hike remains a risk.
Overnight (early Friday), China will release its latest consumer and producer price inflation data for May, with markets looking for further indications of the degree to which the initial rebound in economic activity after the lifting of Covid restrictions is petering out. Annual CPI inflation is forecast to be 0.2% (vs 0.1% in April) and PPI inflation is expected to remain deeply negative at -4.3% (vs -3.6%).
MARKETS
US Treasury and gilt yields rose yesterday after the Bank of Canada’s decision to resume raising interest rates. Next week’s Fed decision will be closely watched, with markets attaching about a 1/3 probability of another 25bp hike. GBP/USD briefly touched 1.25 yesterday before drifting back down.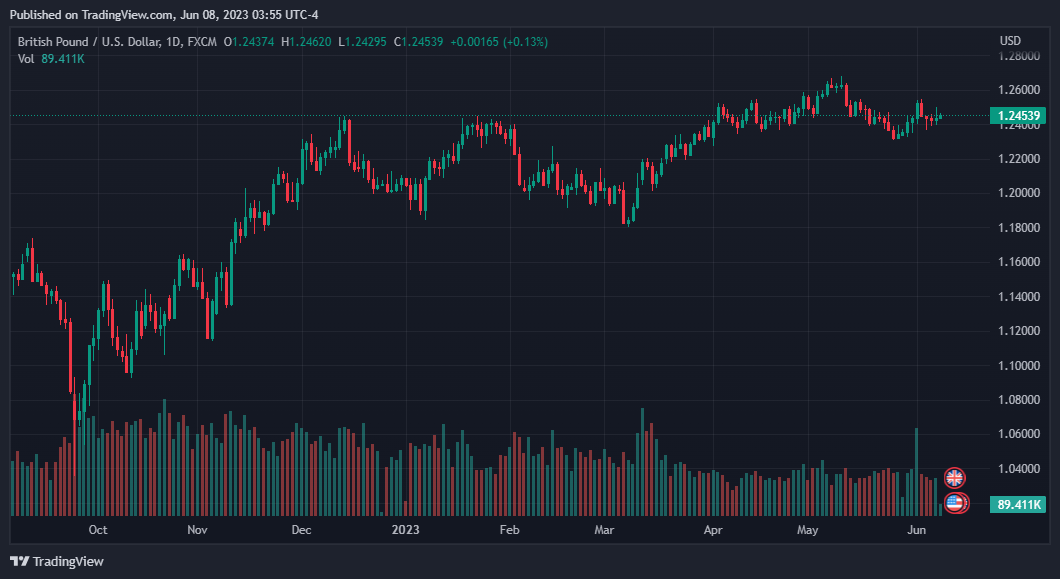


US Payrolls in Focus as Wall Street Rout and Falling Yields Cap the Dollar | 6th November, 2026

The dollar saves the day

Tech Stocks Lead US Selloff Ahead of Payrolls

GBPUSD bull run: Can the pair smash through 1.3565?

Democrats' Midterm Victory Sends Dollar and Oil Lower

US Midterm Elections: Analyzing Fiscal Deficits, Treasury Yields, and the Greenback

US Midterm Results Weigh on the Dollar as Central Bank Policy Divergence Builds | 4th November, 2026






