Oil jumps again, lifting yields but weighing on stocks; dollar steady

Oil supply outlook deteriorates again
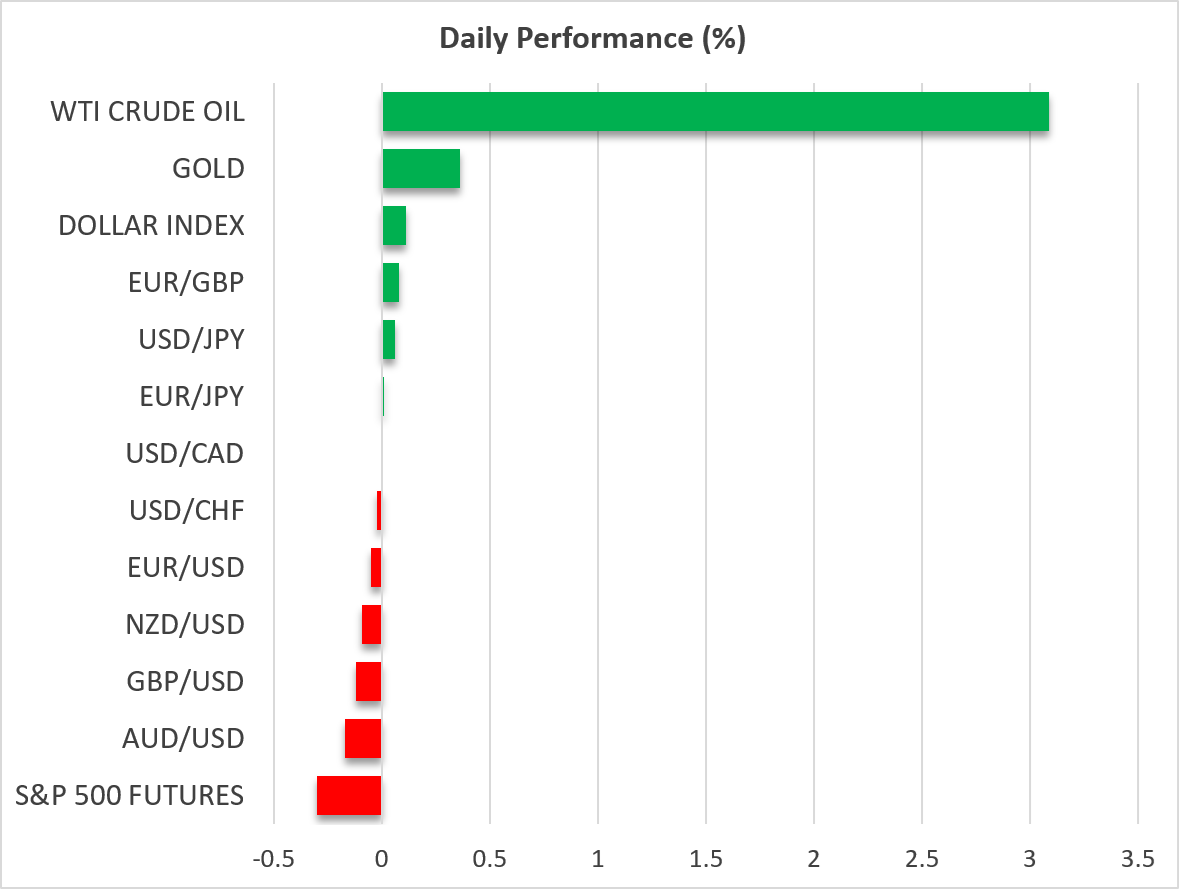
Oil prices headed higher on Thursday, more than reversing Wednesday’s decline, amid renewed worries about supply disruptions in the Middle East. Despite increasing reports that oil exports from the Gulf have returned to pre-war levels, thanks largely to a shadow fleet of vessels operating along the Strait of Hormuz, attacks on oil and gas tankers by Iran’s Revolutionary Guard have risen in October, hitting the highest number since the start of the conflict.
There are also doubts about how much of the 400 million barrels of strategic oil reserves that were agreed to be released in March have made it to the market, even as G7 nations agreed on Friday to pump a further 100 million barrels. It’s likely that the latest amount includes unreleased volumes from the March pledge.
On the bright side, the International Energy Agency (IEA) has said its members will accelerate the release of their stockpiles.
Trump ponders new Iran strikes
Yet, these aren’t the only clouds hanging over the supply outlook. According to the US magazine The Atlantic, President Trump is considering fresh attacks on Iran before next month’s midterm elections. The Pentagon has reportedly been asked by the White House to draw up options for striking Iran within the next month, although no decision has been made.
Adding to the negative headlines, a hurricane headed towards the Gulf of Mexico looks set to temporarily halt oil production from the region. All this is pushing up oil futures today, with WTI and Brent crude futures surging by around 4.0%.
It didn’t take much to drive WTI back above $90 a barrel and Brent back above $100, ending the brief relief enjoyed at the start of the week.
Yields climb but euro stays calm
Unsurprisingly, bond yields are on the up on Thursday, though the benchmark 10-year yields have yet to surpass their recent highs. The US 10-year Treasury yield scaled a new 24-year high of 5.36% early on Wednesday before falling back. French yields are creeping higher again but remain below 5%, for now.
France’s budget proposal for 2027 received a lukewarm response by the markets, as investors wait to see whether the government will be able to secure enough votes in the National Assembly to pass it.
The latest political drive to tackle the soaring budget deficit in France, both from the government as well as the main opposition party, National Rally, has helped to steady the euro. However, the near-term bias for the single currency clearly remains bearish, as the European Central Bank is more likely at this point to turn cautious about hiking rates further than the Fed is should the debt jitters in bond markets worsen.
The euro is currently trading around $1.1188, while the US dollar is modestly firmer against a basket of currencies, including the yen, which was last quoted at 158.20 per dollar.
Fed minutes flag year-end hike
Aside from the greenback benefiting somewhat from its safe-haven attributes this week, there was further support yesterday from the minutes of the Fed’s September policy meeting.
Whilst there were no major surprises from the minutes, they reinforced the Fed’s intention to hike rates further this year. However, the path from thereon is less certain as policymakers appear split about the extent to which higher inflation will become a problem.
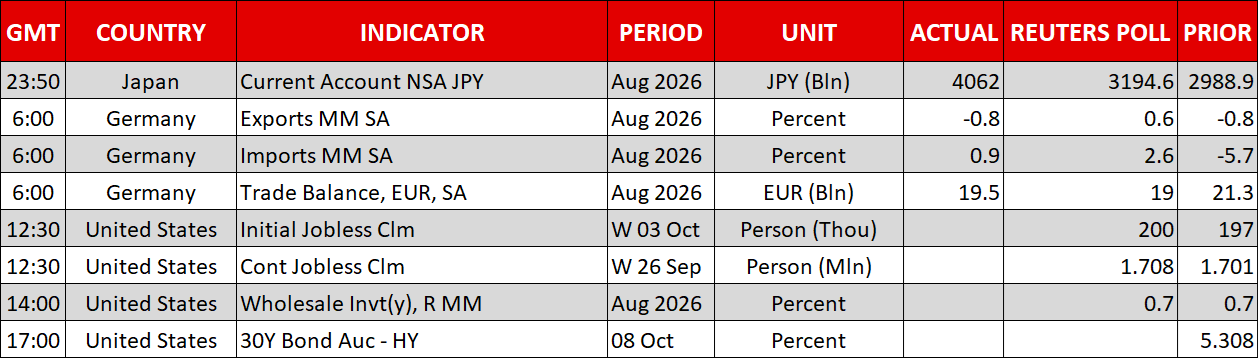
But for now, investors are sticking to their glass half-full view after slashing their October rate hike bets following Friday’s soft jobs report and after yesterday’s auction for 10-year Treasury notes was met with solid demand. The focus later today will be on the 30-year auction, as well as possible comments on monetary policy by Fed Governor Christopher Waller.
Gold off lows but Wall Street slips
Gold is inching higher ahead of those events, despite government bond yields moving in a similar direction. Yesterday’s selloff in precious metals was probably a little overdone, hence, today’s recovery. But the near-term risks are still tilted to the downside, so even though gold has reclaimed the $4,100 handle today, it could soon be testing $4,000 again.
Equity markets are also being weighed by higher bond yields and the spike in oil prices. The S&P 500 finished Wednesday’s session 0.2% lower after Tuesday’s record high, and the Nasdaq 100 declined a similar amount.
Futures are in the red today, as apart from the darker geopolitical landscape, there are some renewed concerns around AI investment just days before the Q3 earnings season fully kicks off.
SpaceX, Broadcom and Oracle are all seeking new financing to fund their latest AI investments, adding to the market angst amid the rise in long-term borrowing costs.

EBC Markets Briefing | Aussie dollar propped up by US mid-term election uncertainty

Gold Edges Higher as Dollar Weakens Ahead of US Midterm Results
Gold/Silver & Gold/Platinum Ratios: Deconstructing the Metals Sell-Off Divergence
GBPUSD Edges Towards 1.3463 as Traders Brace for the Bank of England Decision
Weak NZ Jobs Data Keeps NZDUSD Under Pressure
Gold buying by central banks has hit its highest rate since 2024.
Daily Technical Analysis: Gold Reclaims $3,900 After Hitting Its Lowest Level Since October 2025