Dollar gains amid hawkish Fed commentary and rising geopolitical tensions

Fed’s Hammack and Middle-East developments fuel the dollar
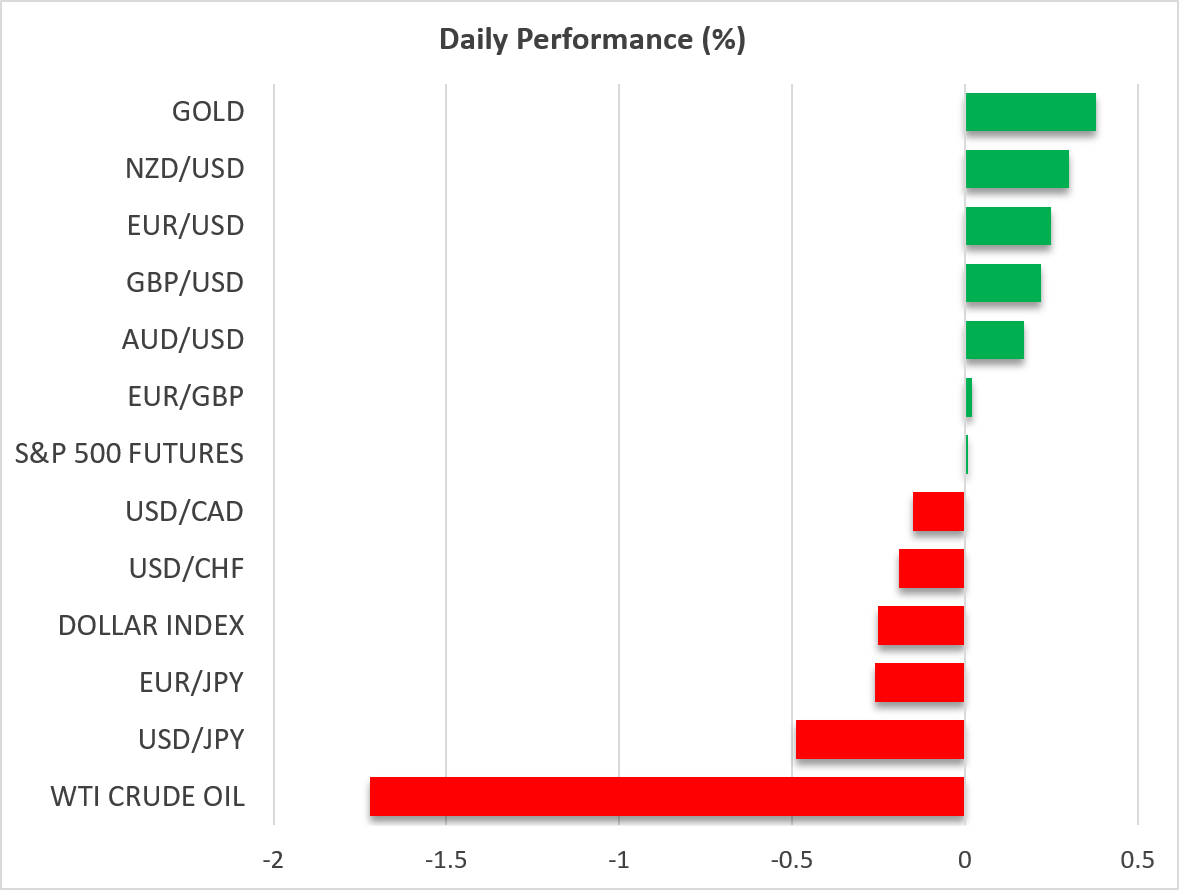
The US dollar strengthened against all its major peers on Monday, driven by hawkish Fed commentary and renewed tensions in the Middle East. Today, the greenback is pulling back, perhaps as traders are adjusting their positions ahead of the resumption of Treasury trading today and the US CPI data tomorrow.
Cleveland Fed President Beth Hammack sounded hawkish yesterday, warning that inflation expectations could become less anchored if policymakers delay in taking action and suggested that the neutral rate may be higher than previously estimated.
Her comments came as oil prices rebounded amid new tensions and strikes in the Middle East and Ukraine. With the reopening of the Strait of Hormuz becoming a far-fetched dream once again and Russia carrying out strikes on Ukraine, including damages to a thermal power plant in Kharkiv, thereby violating the proposed energy ceasefire, oil prices rebounded, intensifying inflation fears once again.
Having said all that though, investors’ expectations about the future course of the Fed’s actions have not been impacted. Market participants still assign a 20% chance of an October hike, fully pricing in the move for December. By the end of 2027, a total of 80bps worth of hikes is baked into the cake.
More Fed speak on the agenda ahead of tomorrow’s CPIs
Today, two more Fed officials will step onto the rostrum: Richmond Fed President Thomas Barkin and Boston Fed President Susan Collins. It will be interesting to see whether they share Hamack’s hawkish views or lean towards those of Vice Fed Chair Jefferson and New York Fed President Williams, who have suggested that the Committee should not rush into pressing the hike button too soon.
As for tomorrow’s CPI inflation data, both the S&P Global and ISM price-related subindices suggest that the risks may be tilted to the upside. Therefore, hotter-than-expected prints could add more fuel to the dollar’s engines, even if they don’t significantly boost the chances of an October hike. They could add more basis points worth of rate hikes for next year.
RBA could hike once again, BoJ expected to hike but yen fails to capitalize
Elsewhere, the minutes of the latest RBA meeting revealed that policymakers believed the upside inflation risks identified earlier had already materialized or started building, leaving the door open to another rate increase if inflation proves more persistent than expected. The probability of another rate hike before the turn of the year continues to hover near 50%. A strong employment report on Thursday could take that probability higher.
The International Monetary Fund (IMF) said today that the Bank of Japan (BoJ) will likely raise interest rates gradually toward a neutral setting, despite an expected slowdown in growth.
The yen is gaining some ground against the dollar today, but the overall picture remains negative. A couple of weeks ago, investors were pricing in 100bps worth of additional rate hikes by the end of 2027. Now the number has dropped to 90bps.
With Prime Minister Takaichi insisting on fiscal spending and calling for the BoJ to keep interest rates low, it may be hard to envision a more hawkish Bank than currently expected. After all, Takaichi has already appointed two doves when she had the opportunity – those members dissented the latest hike – and she could appoint two more next summer, when the term of two ultra-hawks ends.
Even if Japanese authorities decide to intervene again soon, any setbacks in dollar/yen are likely to provide renewed buying opportunities.
Wall Street trades mixed ahead of bank earnings
On Wall Street, both the S&P 500 and the Nasdaq closed slightly in the red on Monday, with only the Dow Jones adding some gains. Perhaps the reason why there was no material decline following Hammack’s remarks was the anticipated start of the bank earnings season later today. What’s more, trading was less informative because the US Treasury market was closed for Columbus Day.
JPMorgan, Goldman Sachs, Citigroup and Wells Fargo are all due to report today, followed by Bank of America and Morgan Stanley on Wednesday. The key question for bank earnings may be how severely tightening financial conditions amid rising yields have weighed on credit demand.


US Midterms: Early Democratic Senate Wins Sink Dollar and Drag Futures Lower
EBC Markets Briefing | Aussie dollar propped up by US mid-term election uncertainty

Gold Edges Higher as Dollar Weakens Ahead of US Midterm Results
Gold/Silver & Gold/Platinum Ratios: Deconstructing the Metals Sell-Off Divergence
GBPUSD Edges Towards 1.3463 as Traders Brace for the Bank of England Decision
Weak NZ Jobs Data Keeps NZDUSD Under Pressure
Gold buying by central banks has hit its highest rate since 2024.